

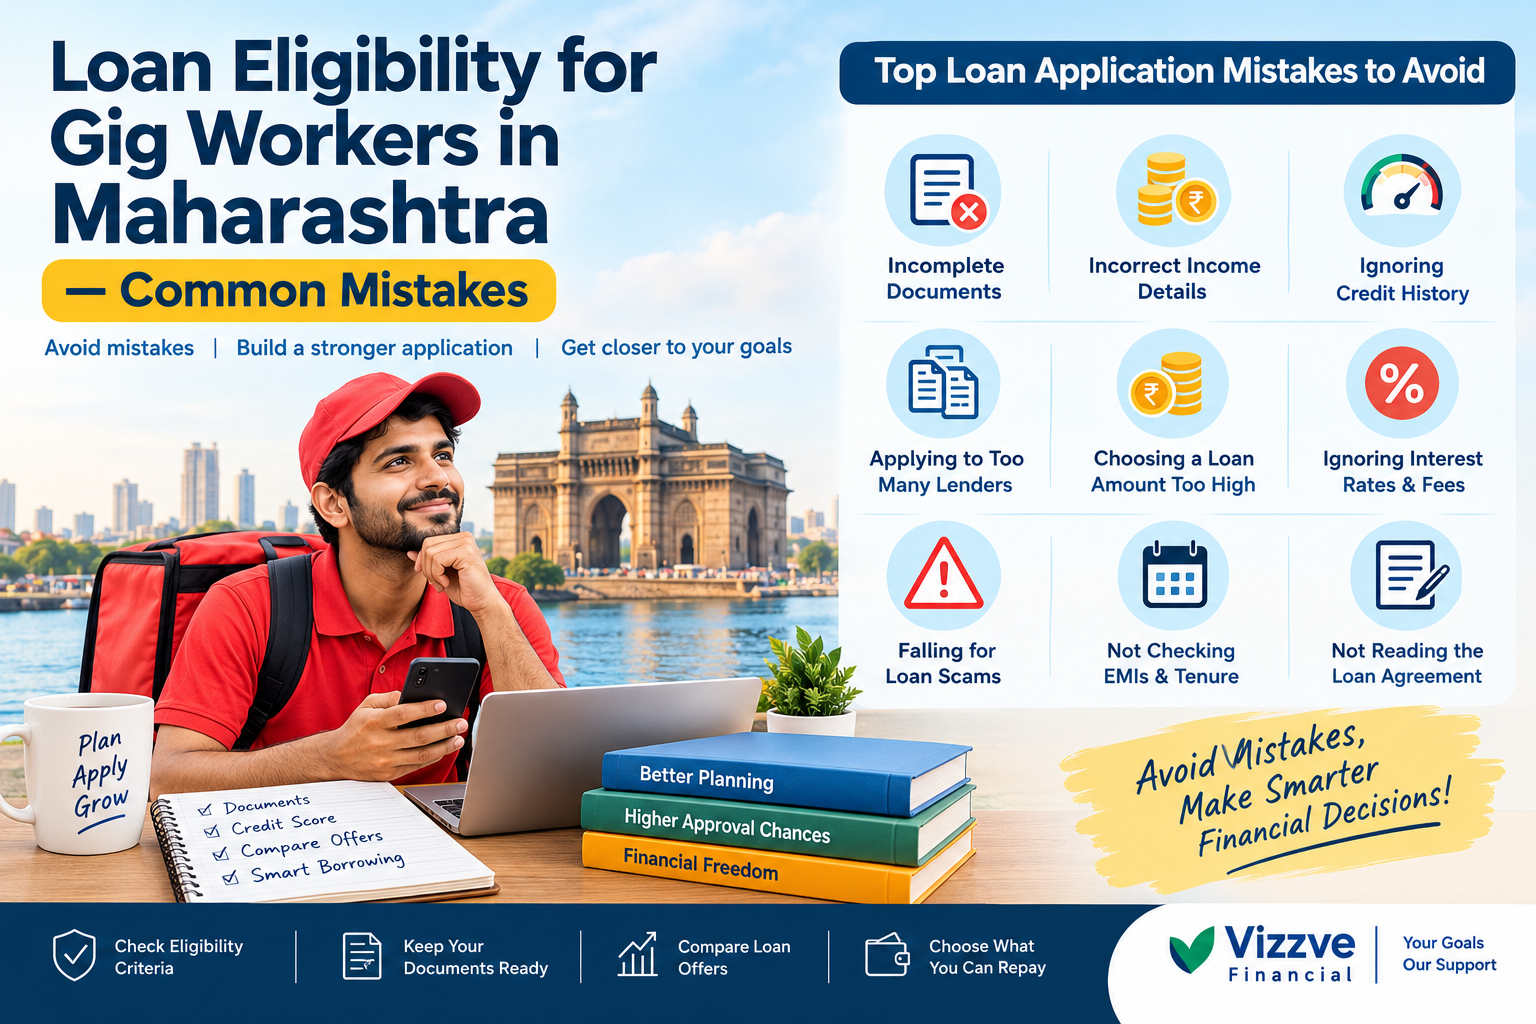
Gig workers are an important part of Maharashtra’s economy. Delivery partners, app-based cab drivers, freelancers, home-service professionals, and independent contractors often depend on flexible work to earn an income.
However, applying for a personal loan can sometimes be challenging when earnings change from week to week or month to month. A worker may earn regularly but lack conventional salary slips, formal employment documents, or a consistent monthly salary credit.
The good news is that gig workers can prepare more carefully by understanding lender requirements and avoiding common application mistakes.
Loan eligibility for gig workers in Maharashtra depends on several factors, including income stability, bank statements, credit history, existing EMIs, identity verification, and the lender’s own policies. Approval is never guaranteed, and eligibility requirements differ between lenders.
This guide explains the most common mistakes gig workers should avoid before applying for a loan.
AI Answer Box: What Mistakes Should Gig Workers Avoid When Applying for a Loan?
Gig workers in Maharashtra should avoid submitting incomplete documents, misreporting income, ignoring their credit history, applying to multiple lenders without research, and overlooking interest rates or additional charges. They should maintain bank statements, preserve platform earnings records, calculate an affordable EMI, and verify that the lender is legitimate. Since gig income can fluctuate, applicants should also keep a realistic repayment buffer for weeks when earnings are lower.
1. Understanding Loan Eligibility for Gig Workers in Maharashtra
Loan eligibility is the lender’s assessment of whether an applicant meets its requirements and can reasonably repay the requested amount.
Gig workers may include:
-
Food and grocery delivery partners
-
App-based taxi and auto-rickshaw drivers
-
Freelance designers, writers, and developers
-
Home-service and repair professionals
-
Independent sales and marketing workers
-
Temporary and contract-based workers
-
Other platform-based or self-employed professionals
Unlike salaried employees, gig workers may receive payments from different sources or experience variations in monthly income.
Lenders may evaluate the following factors:
| Eligibility factor | Why it matters |
|---|---|
| Age | The applicant must meet the lender’s age requirements |
| Income | Helps assess repayment capacity |
| Work history | May help establish continuity of earnings |
| Bank statements | Show money received and regular financial activity |
| Credit history | Provides information about past borrowing and repayment |
| Existing EMIs | Affect the amount available for a new repayment |
| KYC documents | Help verify identity and address |
| Loan amount | Must be consistent with the applicant’s repayment capacity |
Not every lender uses identical criteria. Some may accept platform earnings records or bank statements in place of conventional salary slips, while others may require additional evidence.
2. Common Loan Application Mistakes Gig Workers Should Avoid
Mistake 1: Not Maintaining Proper Income Records
One of the most common problems is failing to preserve records of gig earnings.
A delivery partner might receive weekly platform settlements, incentives, tips, or payments from multiple services. If these transactions are not documented clearly, demonstrating income consistency can become difficult.
How to avoid it:
-
Download monthly earnings statements from work platforms.
-
Keep bank statements readily available.
-
Save payment receipts and invoices for freelance assignments.
-
Maintain a basic monthly income and expense record.
-
Ensure the information submitted to the lender matches supporting documents.
A dedicated bank account for work-related income, where practical, may also make financial records easier to understand.
Mistake 2: Reporting Incorrect or Inflated Income
Some applicants report their best earning month as their regular monthly income. Others include gross platform earnings without accounting for fuel, vehicle maintenance, platform-related expenses, or other work costs.
This can create an unrealistic picture of repayment capacity.
How to avoid it:
Calculate average earnings over several months. Consider both income and essential work expenses, and provide accurate information requested by the lender.
For example, a driver may receive ₹35,000 in platform payouts during a strong month but earn considerably less during a slow month. It would be risky to plan every EMI around the highest payout.
Mistake 3: Ignoring Credit History
A credit report can influence a lender’s assessment of a loan application. Missed payments, high outstanding balances, or errors in a credit report may affect how an application is evaluated.
A limited credit history can also make assessment more difficult for some lenders.
How to avoid it:
-
Review your credit report before applying.
-
Pay existing loan and credit card bills on time.
-
Check for incorrect accounts or repayment entries.
-
Raise disputes through the relevant credit bureau or lender if you find errors.
-
Avoid taking unnecessary loans merely to build credit.
A strong credit profile can help, but it does not guarantee loan approval.
Mistake 4: Applying to Too Many Lenders at Once
Submitting many applications without comparing requirements can lead to unnecessary hard enquiries on your credit report, depending on the lender and enquiry type.
It can also create confusion about interest rates, loan terms, and documentation.
How to avoid it:
-
Check the basic eligibility requirements first.
-
Compare the lender’s disclosed interest rate, fees, and repayment period.
-
Shortlist suitable lenders.
-
Apply only after reviewing the relevant terms.
-
Keep a record of applications and responses.
Use eligibility checks that clearly explain whether they involve a hard credit enquiry or only a preliminary assessment.
Mistake 5: Submitting Incomplete or Incorrect Documents
Missing KYC details, outdated address information, unclear bank statements, or mismatched names can delay processing.
Gig workers may also forget to include platform statements or freelance invoices when those records are requested.
How to avoid it:
Prepare the documents required by the selected lender before submitting the application. Check that names, addresses, bank details, and other information are consistent.
Do not edit statements or alter documents to make income appear higher.
Mistake 6: Choosing a Loan Amount That Is Too High
An applicant may qualify for a certain amount but still struggle to repay it comfortably.
For gig workers, the risk is greater when monthly earnings change with demand, weather, fuel costs, health, vehicle availability, or platform activity.
How to avoid it:
Choose a loan amount based on your actual need and realistic repayment capacity, not simply the maximum amount offered.
Before applying, account for:
-
Rent and household expenses
-
Fuel, maintenance, and other work costs
-
Existing EMIs
-
Insurance and medical expenses
-
Savings for low-income periods
Mistake 7: Ignoring Interest Rates and Additional Charges
Focusing only on the advertised interest rate can lead to an incomplete understanding of borrowing costs.
Depending on the product and lender, the total cost may include processing fees and other disclosed charges. Late-payment or penal charges may also apply under the agreement.
How to avoid it:
Read the Key Facts Statement (KFS), where applicable, and the loan agreement before accepting an offer. Review the Annual Percentage Rate (APR), repayment schedule, fees, late-payment terms, and prepayment conditions.
RBI rules require regulated lenders to provide relevant disclosures for covered loan products. See the RBI Digital Lending Directions, 2025 and the RBI Key Facts Statement circular.
Mistake 8: Falling for Loan Approval Scams
Fraudulent websites, messages, or callers may promise guaranteed approval or ask for advance payments to release a loan.
Warning signs include pressure to act immediately, unclear lender details, requests for OTPs or PINs, and demands to transfer money to a personal account.
How to avoid it:
-
Verify the actual lender and its regulatory status.
-
Check the lender’s official website and grievance contact details.
-
Never share your banking PIN, password, or OTP.
-
Do not install unknown applications at a caller’s request.
-
Read the privacy policy before granting permissions.
-
Be cautious of “guaranteed loan approval” claims.
A genuine loan application should not require you to surrender control of your bank account or security credentials.
Mistake 9: Depending Only on Cash Earnings
Cash income may be legitimate, but it can be harder to verify if no supporting records exist.
How to avoid it:
Keep appropriate receipts, invoices, work records, or other evidence of earnings. Deposit and document income consistently where practical, while complying with applicable tax and banking requirements.
Never create false records to satisfy a lender.
Mistake 10: Not Considering Existing EMIs
An applicant may focus on their monthly income without calculating how much is already committed to debt repayments.
This can lead to an application for a loan that leaves too little money for household needs.
How to avoid it:
Add together all current monthly EMIs and compare the total with realistic take-home income after work expenses. The amount left over should cover essential costs and provide a buffer for slower earning periods.
There is no single EMI-to-income threshold that guarantees approval across all lenders.
Mistake 11: Ignoring Repayment Flexibility
Gig workers may earn differently during festivals, monsoons, holidays, or slow business periods. A repayment plan that works in one month may become difficult in another.
How to avoid it:
-
Check the EMI due date and payment method.
-
Keep funds ready before the due date.
-
Maintain an emergency buffer if possible.
-
Understand the consequences of missed payments.
-
Contact the lender promptly if you anticipate repayment difficulties.
Choose a repayment schedule that remains manageable in an average or below-average month.
Mistake 12: Not Reading the Loan Agreement
Some borrowers accept a loan after reviewing only the approved amount and EMI.
The agreement may contain important terms covering charges, repayment dates, default consequences, prepayment, grievance redressal, and data use.
How to avoid it:
Read the KFS and loan agreement carefully. Ask the lender to clarify anything you do not understand before accepting the offer. Save the sanction letter, agreement, repayment schedule, and payment receipts.
3. Quick Comparison: Mistakes vs Better Practices
| Common mistake | Better practice |
|---|---|
| No organised income records | Keep platform statements and bank records |
| Inflated income declaration | Report accurate, supportable earnings |
| Ignoring credit history | Review reports and repay existing debt on time |
| Applying everywhere | Compare lenders before applying |
| Incomplete documents | Prepare a lender-specific checklist |
| Borrowing the maximum available | Borrow only what you need and can repay |
| Ignoring fees | Review APR, KFS, and agreement terms |
| Trusting guaranteed approval | Verify the lender and avoid suspicious payments |
| Relying on the best earning month | Budget using realistic average income |
| Overlooking current EMIs | Calculate total debt obligations |
| Ignoring low-income periods | Maintain a repayment buffer |
| Accepting terms without reading | Understand the agreement before signing |
4. Documents Gig Workers May Need
The documents required depend on the lender, loan product, and applicant’s circumstances. A typical checklist may include:
-
PAN card or other accepted identity documentation
-
Aadhaar or another accepted address/identity document, as requested
-
Recent bank statements
-
Platform earnings statements
-
Payment settlement records
-
Freelance invoices or contracts, where applicable
-
Proof of current address, if required
-
Existing loan details, if requested
-
Other income or employment documents requested by the lender
Important: This is a preparation checklist, not a universal list of mandatory documents. Confirm the exact requirements with the lender before applying.
5. How Gig Workers in Maharashtra Can Prepare a Stronger Loan Application
Step 1: Review Your Monthly Earnings
Look at several months of income instead of relying on one unusually strong month. Separate work-related costs from money available for household expenses and repayments.
Step 2: Organise Your Financial Records
Keep bank statements, platform earnings reports, invoices, and receipts in an accessible folder. Ensure the records are genuine and up to date.
Step 3: Check Your Credit Report
Review your borrowing history and look for errors. If you find inaccurate information, raise a dispute through the relevant lender or credit bureau.
Step 4: Calculate an Affordable EMI
Estimate the repayment amount and consider whether you could manage it during a month with lower earnings.
Step 5: Compare Suitable Loan Offers
Compare the APR, interest calculation method, tenure, fees, repayment schedule, and prepayment conditions. Do not choose an offer based only on the advertised EMI.
Step 6: Verify the Lender
Confirm the lender’s identity and review its official disclosures, customer support, privacy terms, and grievance process.
Step 7: Submit Accurate Information
Complete the application carefully and provide only genuine documents. Review the loan terms before signing or giving final consent.
6. Illustrative Example: A Delivery Partner in Pune
Consider a hypothetical delivery partner working in Pune who receives varying monthly payouts:
| Month | Illustrative payouts |
|---|---|
| Month 1 | ₹28,000 |
| Month 2 | ₹32,000 |
| Month 3 | ₹25,000 |
| Month 4 | ₹30,000 |
| Average monthly payouts | ₹28,750 |
The average shown is based on the four illustrative monthly payout figures. It is not necessarily the worker’s disposable income because fuel, vehicle maintenance, taxes, and other costs may still need to be deducted.
Suppose the worker applies for a loan after looking only at the ₹32,000 month and requests more money than needed. If the worker has not organised income records or calculated existing EMIs, the application may be harder to assess and the repayment plan may be unsuitable.
A more careful approach would be to:
-
Prepare several months of genuine income records.
-
Estimate income after work expenses.
-
Review existing EMIs and household costs.
-
Request an amount suited to the actual requirement.
-
Compare written loan offers and understand the total cost.
This approach does not guarantee approval, but it can help the applicant make a more informed decision.
7. Benefits and Limitations of Careful Loan Preparation
Benefits
-
Helps reduce avoidable documentation errors.
-
Makes income patterns easier to demonstrate.
-
Encourages realistic borrowing decisions.
-
Helps borrowers compare total loan costs.
-
Can make it easier to identify suspicious loan offers.
-
Encourages better repayment planning.
Limitations
-
Proper documentation does not guarantee approval.
-
A lender may require additional records or reject an application.
-
Income may remain unpredictable despite careful budgeting.
-
Interest rates and charges vary by lender and applicant.
-
A credit report may contain issues that take time to resolve.
8. Loan Application Safety Checklist
Before submitting an application, check each item:
-
I have reviewed my recent earnings and work expenses.
-
My income declaration is accurate.
-
I have genuine, current documents ready.
-
I have checked my credit history.
-
I have calculated my existing EMIs.
-
I have estimated an affordable repayment amount.
-
I have compared the total cost of suitable offers.
-
I have read the KFS and loan agreement, where applicable.
-
I have verified the lender’s identity and contact details.
-
I have not shared an OTP, PIN, or banking password.
-
I understand the EMI due date and consequences of missed payments.
9. How Vizzve Financial Can Fit Into Your Loan Research
Vizzve Financial can be explored as a starting point for loan-related information and support. Gig workers should check the specific services available, the identity of the actual lending institution, and the eligibility requirements that apply to any offer.
Before proceeding, verify the interest rate, APR, fees, documents required, and repayment terms directly through the relevant official channel. Do not assume that every applicant will qualify or that approval is guaranteed.
Visit www.vizzve.com to explore available information and services.
10. Frequently Asked Questions (FAQs)
1. Can gig workers in Maharashtra apply for personal loans?
Yes, gig workers may apply for personal loans if they meet a lender’s requirements. Eligibility depends on factors such as income, credit history, documentation, existing obligations, and the loan product.
2. What are the most common loan application mistakes gig workers make?
Common mistakes include incomplete documentation, inaccurate income declarations, overlooking credit history, applying without comparing offers, and borrowing more than they can comfortably repay.
3. Can delivery partners apply without salary slips?
Some lenders may accept alternative income evidence, such as bank statements and platform earnings reports. Requirements vary, so confirm the accepted documents with the specific lender.
4. What documents may a gig worker need for a loan?
Depending on the lender, applicants may need KYC documents, bank statements, earnings reports, invoices, and other proof of income. There is no universal document list for every lender.
5. Does irregular income automatically disqualify a gig worker?
Not necessarily. Some lenders assess variable income using bank statements, work records, and other evidence. However, their eligibility criteria differ.
6. Does a good credit score guarantee loan approval?
No. A credit score may contribute to the assessment, but lenders can also consider income, existing EMIs, documentation, and internal eligibility rules.
7. Should gig workers apply to several lenders at once?
It is generally better to compare eligibility requirements and loan costs first. Multiple formal applications may result in multiple hard enquiries, depending on how each lender processes them.
8. How can a gig worker show income proof?
Possible evidence includes platform earnings statements, bank statements, invoices, payment receipts, and other genuine records accepted by the lender.
9. What should gig workers check before accepting a loan?
Review the APR, interest rate, fees, EMI, tenure, repayment schedule, prepayment terms, late-payment consequences, and grievance redressal details.
10. Are upfront loan approval fees a warning sign?
A request for money to guarantee approval or release a promised loan should be treated cautiously. Verify all charges through the lender’s official documentation and never transfer money to an unverified personal account.
11. Can existing EMIs affect loan eligibility?
Yes. Existing repayments can reduce the income available for a new EMI and may affect the lender’s assessment of repayment capacity.
12. What if the information on my credit report is incorrect?
Contact the relevant lender or credit bureau and raise a dispute using its official process. Keep supporting documents and track the resolution.
13. Is it safe to apply for a loan through a mobile app?
It depends on the app and the actual lender. Verify the regulated lending institution, read its privacy policy, review permissions, and check the loan disclosures before sharing information.
14. Can a gig worker get approved without a long work history?
Possibly, depending on the lender’s requirements and the other evidence available. A short work history may make it more difficult for some lenders to assess income stability.
15. How can gig workers avoid repayment problems?
Borrow only what is needed, calculate the EMI against realistic income after work expenses, plan for low-income months, and keep funds ready for each due date.
Conclusion
Loan eligibility for gig workers in Maharashtra is influenced by more than the type of work they do. Accurate income records, genuine documentation, responsible borrowing, credit awareness, and careful comparison of loan terms can all help applicants prepare more effectively.
Avoiding common mistakes will not guarantee approval, but it can reduce preventable problems and help gig workers make safer financial decisions.
Published on : 20th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed