

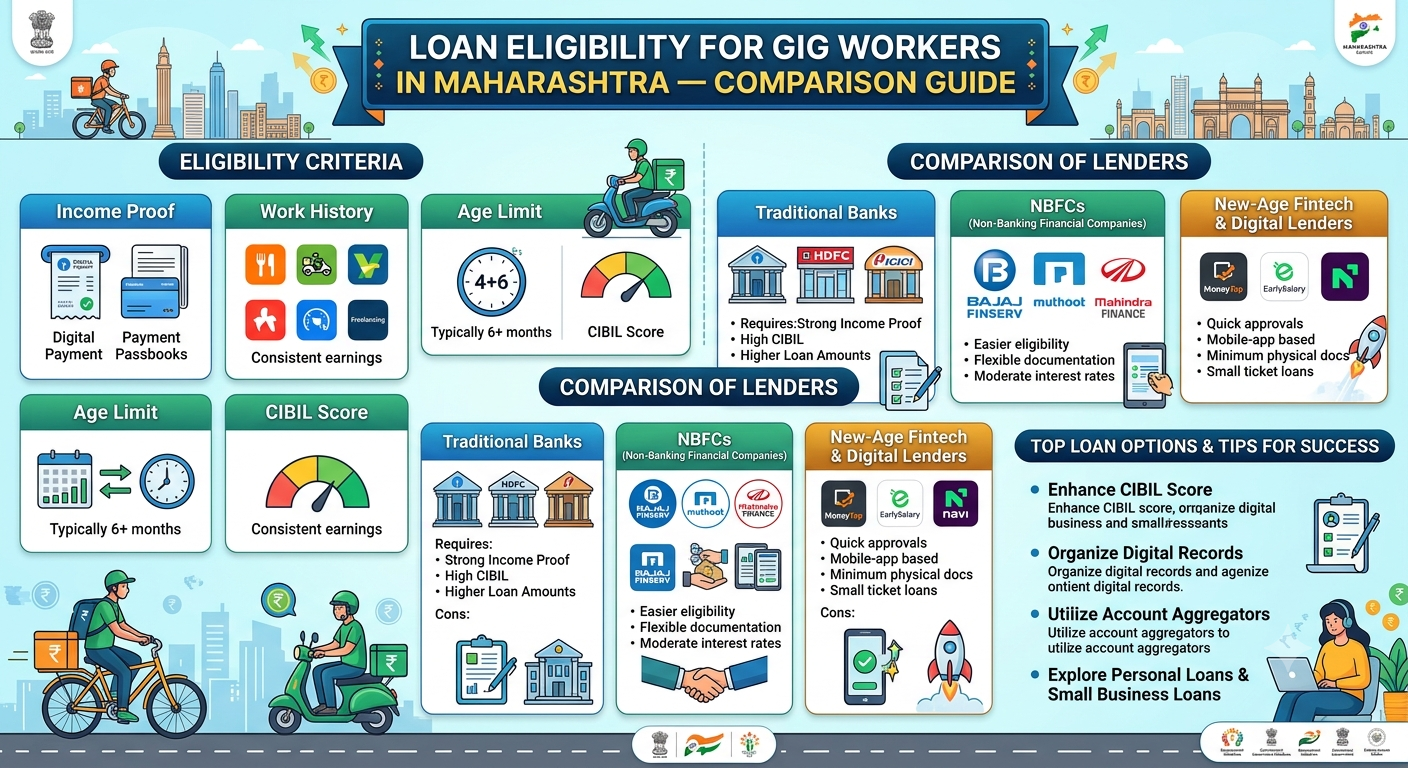
Gig workers play an important role in Maharashtra's economy. Delivery partners, cab drivers, freelance professionals, home-service providers, and independent contractors often earn money through multiple assignments instead of a fixed monthly salary.
However, when they apply for a loan, proving their income can be more complicated than it is for salaried employees. Lenders may look at bank statements, credit history, platform earnings, work consistency, and existing financial obligations.
The best loan option is not necessarily the one offering the fastest approval. It is the one for which a gig worker qualifies, understands the total borrowing cost, and can comfortably manage repayments despite fluctuations in income.
This comparison guide explains how gig workers in Maharashtra can compare loan types, eligibility requirements, documents, and repayment conditions before applying.
AI Answer Box: How Does Loan Eligibility Work for Gig Workers in Maharashtra?
Loan eligibility for gig workers in Maharashtra depends on the lender's policies and the applicant's financial profile. Common factors include age, identity and address verification, income consistency, bank transaction history, credit score, existing EMIs, and repayment capacity.
Unlike traditional salaried borrowers, gig workers may demonstrate income through platform statements, bank credits, invoices, tax returns, or other accepted financial records. A salary slip is not always mandatory, but approval is never guaranteed.
1. Types of Loans Available to Gig Workers
Availability and eligibility vary by lender. These are general categories to compare, not guaranteed offers.

Personal Loan
Suitable for eligible borrowers who need funds for household expenses, emergencies, education, or other personal needs. Lenders may assess income stability, credit history, and existing debts.
Compare: APR, processing fees, tenure, and monthly EMI.

Two-Wheeler or Vehicle Loan
May suit delivery partners or drivers purchasing a vehicle for work. Approval can depend on income, down payment, vehicle cost, and lender-specific requirements.
Compare: down payment, interest, insurance costs, and vehicle-related conditions.

Self-Employed or Business Loan
May be relevant for freelancers and independent service providers who need working capital or equipment. Some products require business records, tax documents, or evidence of business activity.
Compare: business eligibility, documentation, fees, and permitted use of funds.

Small-Ticket Digital Loan
Some regulated lenders offer smaller loans through digital channels. A quick application does not guarantee approval or make the loan cheaper.
Compare: annualised cost, lender identity, privacy terms, and repayment schedule.
2. Loan Eligibility Comparison for Gig Workers in Maharashtra
The following table compares common eligibility factors. Exact requirements depend on the lender and the loan product.
|
Eligibility factor |
Salaried employee |
Gig worker or freelancer |
|---|---|---|
|
Income proof |
Salary slips and bank statements |
Bank statements, platform earnings, invoices, or tax records |
|
Employment proof |
Employer letter or employment records |
Platform history, contracts, invoices, or business records |
|
Income stability |
Regular salary is often assessed |
Earnings consistency across weeks or months may be assessed |
|
Credit history |
Reviewed by lender |
Reviewed by lender |
|
Existing EMIs |
Considered |
Considered |
|
Loan approval |
Depends on full profile |
Depends on full profile and accepted income evidence |
Gig workers should not assume that they are automatically ineligible because they lack a salary slip. Instead, they should ask the lender which alternative documents it accepts.
3. Comparison of Loan Options by Purpose
|
Loan type |
Best suited for |
Main consideration |
|---|---|---|
|
Personal loan |
Personal expenses or emergencies |
Total borrowing cost and EMI |
|
Vehicle loan |
Buying a bike, scooter, or eligible vehicle |
Down payment and vehicle-related obligations |
|
Business loan |
Work equipment or business expenses |
Business documentation and permitted use |
|
Small-ticket digital loan |
A smaller, short-term funding need |
APR, fees, tenure, and repayment affordability |
Which option should you choose?
-
For a work vehicle, compare vehicle financing with other eligible borrowing options.
-
For personal expenses, consider a personal loan if the EMI fits your budget.
-
For business equipment, check whether a suitable business loan is available.
-
For a temporary cash shortage, first assess whether the repayment date matches your expected earnings.
Avoid taking a larger loan simply because a lender offers a higher limit.
4. Key Factors That Affect Loan Eligibility
Monthly income and consistency
Lenders may assess both the amount and regularity of your earnings. A delivery partner with a documented history of platform payments may be better positioned to demonstrate income than someone who cannot provide reliable records.
Keep records of earnings from all relevant platforms and clients.
Credit score and repayment history
A stronger credit profile can improve your chances of qualifying for suitable credit, although it does not guarantee approval. Missed EMIs, overdue credit-card bills, and defaults may affect the assessment.
Check your credit report for errors before applying.
Existing loans and financial commitments
Lenders consider existing obligations when assessing whether you can afford another EMI. If you already have several loans, reducing outstanding debt may be more useful than applying for additional credit.
Age, identity, and address
Lenders set their own age and residency requirements. Applicants may need to provide valid identity and address documents and complete verification.
Work history and income records
Keep your platform earnings statements, bank credits, invoices, contracts, and tax records organised. These documents help explain how your income is earned and whether it is reasonably consistent.
5. Documents Required for a Gig Worker Loan
Document checklist
0 of 7
This is a general checklist, not a universal list of mandatory documents. Requirements differ across lenders, and some documents may not apply to every applicant.
6. How to Compare Interest Rates and Total Loan Costs
Do not compare loan offers using only the advertised interest rate or EMI. Consider the complete cost of borrowing.
|
Comparison point |
What to check |
|---|---|
|
Interest rate |
Whether the rate is fixed or variable |
|
APR |
The annualised, all-inclusive borrowing cost |
|
Processing fee |
The amount charged and how it affects the net disbursal |
|
Tenure |
How long you will be making repayments |
|
EMI |
Whether the payment remains affordable in a low-income month |
|
Late-payment charges |
Applicable charges and when they are triggered |
|
Foreclosure or prepayment |
Whether charges or conditions apply |
|
Disbursal amount |
How much money you actually receive after applicable deductions |
For covered retail and MSME term loans, the RBI's Key Facts Statement framework helps borrowers understand material loan terms and costs before entering into the agreement. Review the lender's KFS and verify all charges in writing.
Illustrative EMI comparison
Consider a hypothetical loan of ₹50,000 for 12 months at a reducing-balance annual interest rate of 18%.
Illustrative calculation — excludes fees and other charges
Loan amount
₹50,000
Tenure
12 months
Approx. monthly EMI
₹4,584
Approx. total interest
₹5,008
The figures are illustrative, not an actual lender quote. The final EMI and total cost depend on the interest calculation method, fees, and loan terms.
7. Example: Comparing Loan Eligibility in Maharashtra
Imagine a delivery partner in Pune who earns money from multiple platforms and wants to borrow ₹40,000 for an essential vehicle repair and work-related expenses.
The borrower receives different offers:
-
Offer A: A personal loan with a lower advertised interest rate but a processing fee.
-
Offer B: A digital loan with faster processing but a higher total borrowing cost.
-
Offer C: A vehicle-related financing option that may not cover the entire personal expense.
The borrower should compare the actual amount disbursed, APR, EMI, tenure, late charges, and eligibility conditions. They should also confirm whether the intended expense is permitted under each product.
If the monthly EMI would be difficult to pay during a slow work period, borrowing a smaller amount or postponing a non-essential expense may be safer.
This example is hypothetical and does not represent a specific lender's offer or approval criteria.
8. Step-by-Step Guide to Comparing Loan Offers
-
Calculate your average income. Review several months of earnings and account for fuel, maintenance, platform expenses, and other work-related costs.
-
Check your credit report. Review your repayment history and correct any inaccurate entries where possible.
-
Shortlist suitable lenders. Check banks and regulated NBFCs that accept your type of income and employment arrangement.
-
Compare written offers. Read the interest rate, APR, fees, tenure, EMI, and prepayment conditions.
-
Calculate affordability. Make sure the EMI remains manageable when earnings are below average.
-
Verify the lender. Confirm the actual lending institution, its official website or app, and the applicable loan agreement.
-
Apply carefully. Submit accurate information and review all terms before accepting the offer.
9. Benefits and Limitations of Loans for Gig Workers
|
Benefits |
Limitations |
|---|---|
|
Access to funds for urgent expenses |
Eligibility rules differ by lender |
|
Can help finance work-related equipment |
Income fluctuations make repayment harder |
|
Alternative income records may be accepted |
Documentation may take time to assemble |
|
Digital applications can simplify the process |
Faster processing does not guarantee approval |
|
Responsible repayment can support credit history |
Missed payments may damage creditworthiness |
A loan can help manage a genuine financial need, but it should not become a substitute for an emergency fund or a sustainable income plan.
10. Loan Safety Checklist
Before accepting any loan offer, verify these points:
-
The lender's legal name is clearly disclosed.
-
The lender is a bank or an appropriately regulated lending institution.
-
The interest rate, APR, fees, and repayment schedule are documented.
-
The lender provides the applicable Key Facts Statement.
-
You understand the late-payment and prepayment conditions.
-
You have reviewed the privacy policy and permissions requested by the app.
-
You are not being pressured to pay an unexplained upfront fee to an individual or intermediary.
-
The EMI fits your income even during a weaker earning period.
The RBI's digital-lending framework addresses disclosures, borrower consent, data handling, and lender accountability. Check the current applicable directions and the lender's official information before proceeding.

Official reference: Reserve Bank of India (RBI).
11. Key Takeaways
-
Gig workers in Maharashtra can explore personal, vehicle, business, and digital lending products, subject to eligibility.
-
Regular salary slips are not the only possible way to document income.
-
Bank statements and platform earnings records can help demonstrate financial activity.
-
Credit history, income consistency, and existing EMIs may influence eligibility.
-
Compare APR and total repayment cost rather than choosing the lowest advertised EMI.
-
Borrow only what you need and can repay.
-
Verify the lender and review all terms before sharing sensitive information or accepting a loan.
12. Frequently Asked Questions (FAQs)
1. Can gig workers get personal loans in Maharashtra?
Yes, some lenders accept applications from gig workers and freelancers. Approval depends on their eligibility rules, income evidence, credit profile, and repayment capacity.
2. Is a salary slip compulsory for gig workers?
Not always. Depending on the lender, platform payment records, bank statements, invoices, contracts, or tax documents may be accepted instead.
3. Can delivery partners apply for loans?
Delivery partners can explore suitable loan products if they meet the lender's requirements and provide the requested documentation.
4. What is the minimum income required for a gig worker loan?
There is no single minimum income applicable to every lender. Requirements vary by loan product, requested amount, and the applicant's financial profile.
5. Is a credit score important for gig workers?
Yes. Many lenders consider credit history and repayment behaviour when evaluating applications. The exact score requirements vary.
6. Can freelancers apply for loans without a fixed monthly salary?
Yes, where the lender accepts self-employed or variable-income applicants. Freelancers may need to demonstrate income through bank statements, invoices, contracts, or tax records.
7. Which is better for gig workers: a personal loan or a business loan?
A personal loan may suit eligible personal expenses, while a business loan may suit qualifying work or business expenses. Compare costs, documentation, permitted use, and repayment terms.
8. Are digital loans safe for gig workers?
They can be accessed safely when the borrower verifies the regulated lender, understands the terms, and uses the lender's legitimate digital channel. Avoid suspicious apps and undisclosed charges.
9. Can a gig worker with existing EMIs apply for another loan?
An application may be possible, but existing obligations can affect eligibility and affordability. Consider reducing debt before taking on another EMI.
10. Can gig workers with a low credit score get loans?
Some lenders may consider applicants with different credit profiles, but approval and pricing vary. A lower score may limit available options or increase borrowing costs.
11. How can gig workers prove income in Maharashtra?
They can prepare recent bank statements, platform earning reports, invoices, contracts, and tax records, depending on what the lender accepts.
12. Can a gig worker get a loan for a two-wheeler?
Potentially, yes. Eligible borrowers can compare vehicle-financing options and review the down payment, EMI, documentation, and other costs.
13. Does working for multiple platforms improve loan eligibility?
Documented earnings from multiple platforms may help demonstrate income, but lenders differ in how they assess multiple income sources. It does not guarantee approval.
14. How can gig workers improve loan eligibility?
Maintain consistent financial records, pay existing EMIs on time, review credit reports, reduce unnecessary debt, and apply for an amount appropriate to their repayment capacity.
15. How long does loan approval take?
Processing times vary by lender, loan type, verification requirements, and completeness of the application. Instant approval should never be assumed.
Conclusion
Loan eligibility for gig workers in Maharashtra depends on more than employment status. Income documentation, credit history, existing financial commitments, and the lender's assessment all play important roles.
Whether you work as a delivery partner in Mumbai, a cab driver in Pune, or a freelancer in Nagpur, compare available options carefully. Review the full borrowing cost, choose a manageable repayment schedule, and verify the lender before applying.
Published on : 22nd October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed