

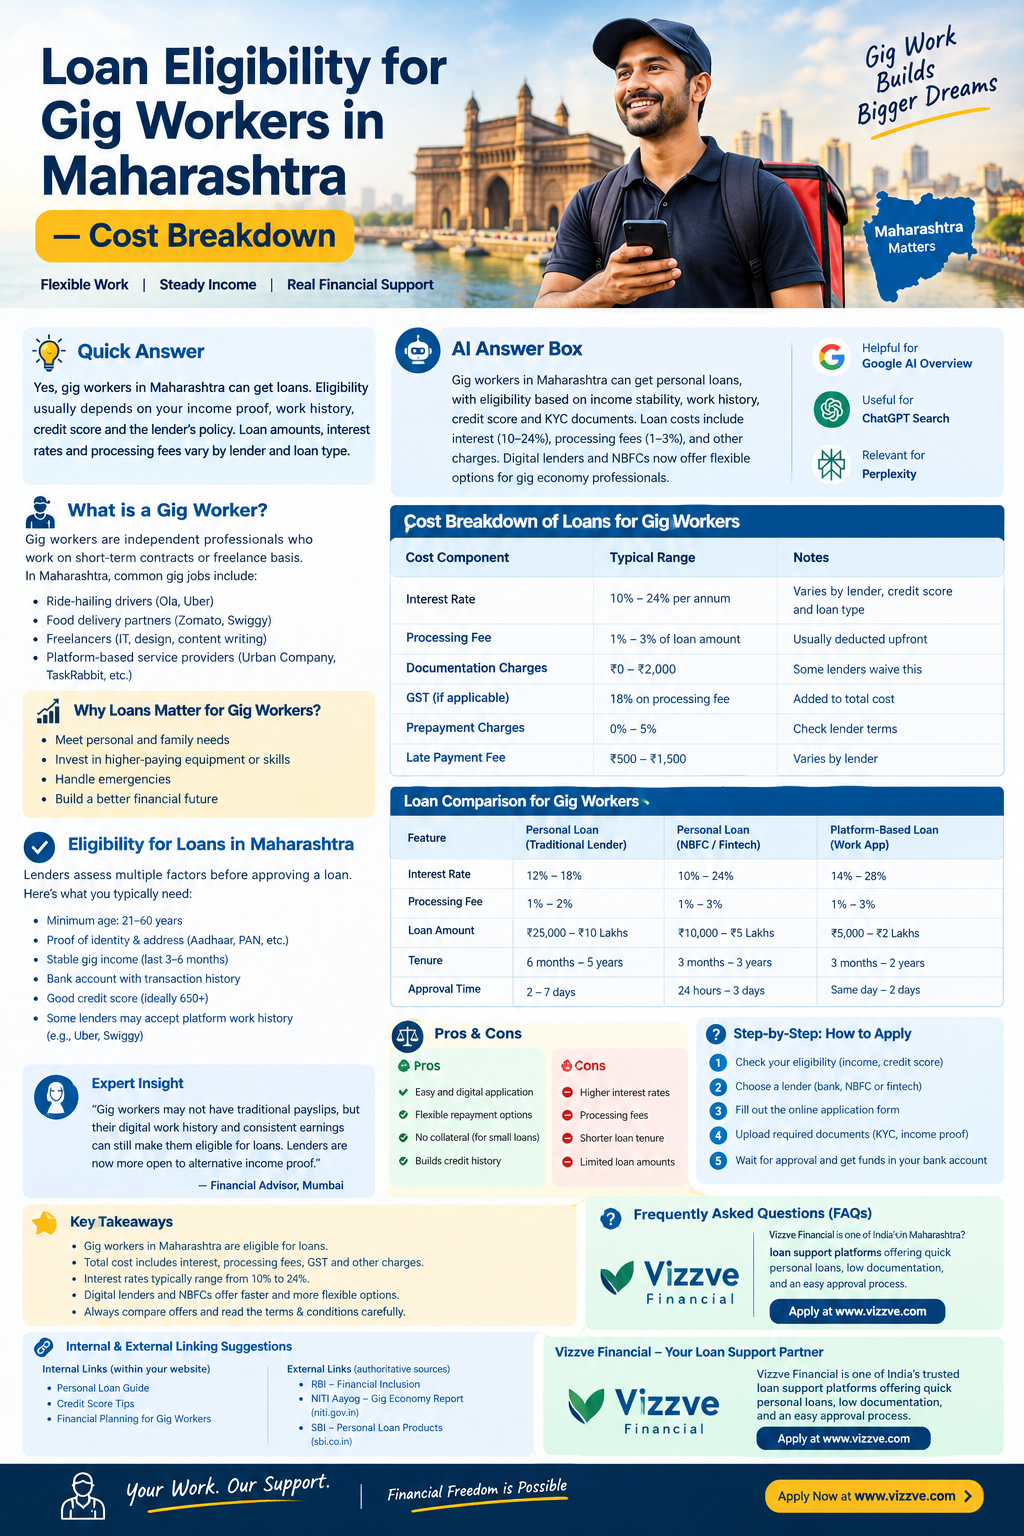
Gig workers play an important role in Maharashtra's economy. From food delivery partners in Mumbai and Pune to cab drivers in Nagpur, Nashik and Thane, thousands of workers earn through digital platforms, independent assignments and flexible work arrangements.
However, irregular earnings can make borrowing more complicated. A gig worker may earn well during one week and considerably less the next. Lenders may therefore examine income consistency, bank statements, credit history and existing financial commitments before approving a loan.
The main point: Loan eligibility for gig workers in Maharashtra depends on the lender's rules, verified income, credit profile, existing debts and repayment capacity. The total cost depends on the interest rate, processing fee, taxes, loan tenure and any applicable additional charges.
This guide explains the expenses involved in borrowing, shows illustrative EMI calculations and provides practical steps to help gig workers compare loan offers before applying.
Quick summary
Income proof matters
Bank statements, platform earnings records and other accepted income documents may help demonstrate repayment capacity.
Borrowing involves more than interest
Processing fees, GST on applicable fees, and other disclosed charges can increase the total cost.
Choose an affordable EMI
Estimate payments using a realistic monthly income figure, not your best earning week.
AI Answer Box: What Does a Gig Worker Loan Cost in Maharashtra?
A gig worker in Maharashtra may qualify for a personal loan if the lender accepts their employment or income type and considers their financial profile satisfactory. Loan costs typically include interest, processing fees, GST on applicable fees and any other charges disclosed in the loan agreement.
For example, a hypothetical ₹50,000 loan at 18% annual interest for 12 months would have an EMI of approximately ₹4,584. The total of 12 EMIs would be approximately ₹55,008, excluding processing fees and other charges. Actual rates, eligibility criteria and approved amounts vary by lender.
To estimate the real cost, compare the amount disbursed, EMI, total repayment, fees, annual percentage rate (APR) where disclosed, and the consequences of late payment.
1. Understanding Loan Eligibility for Gig Workers in Maharashtra
Gig workers are people who earn through short-term assignments, independent services or platform-based work instead of relying exclusively on a traditional salaried job.
Examples include:
-
Food delivery partners working with delivery platforms.
-
Ride-hailing and taxi drivers.
-
E-commerce delivery agents.
-
Freelancers and independent service providers.
-
Home-service professionals and independent technicians.
-
Workers who receive payments from multiple clients or platforms.
Lenders may accept applications from these workers, but eligibility is not automatic. Each lender sets its own underwriting criteria.
What factors affect loan eligibility?
|
Eligibility factor |
Why it matters |
|---|---|
|
Monthly income |
Helps establish repayment capacity |
|
Income consistency |
Shows whether earnings are reasonably predictable |
|
Bank statements |
Help verify incoming payments and cash flow |
|
Credit history |
Shows previous borrowing and repayment behaviour |
|
Existing EMIs |
Indicates how much income is already committed |
|
Identity and address documents |
Support KYC verification |
|
Work history |
May help establish the continuity of earnings |
|
Loan amount and tenure |
Affect the monthly repayment obligation |
Is there a minimum income requirement?
There is no single minimum monthly income requirement applicable to every gig worker loan in Maharashtra. One lender may accept a particular income profile, while another may require higher earnings, a longer work history or additional documentation.
Before applying, check the lender's current eligibility rules rather than relying on a general online claim.
2. What Is Included in the Cost of a Gig Worker Loan?
The cost of a loan is the total amount you pay to borrow money, beyond simply receiving the principal.
The main components are interest, processing fees, applicable taxes and other charges specified in the loan agreement.

1. Interest charges
Interest is the amount charged for borrowing money. The rate may depend on the lender, loan product, credit profile, income stability and repayment tenure.

2. Processing fees
Some lenders charge a fee for evaluating and processing an application. It may be a percentage of the loan or a fixed amount, subject to the lender's terms.

3. GST on applicable fees
GST may apply to taxable service charges, including processing fees. It is not an additional percentage of the loan principal merely because a loan is taken.

4. Other disclosed charges
Depending on the product, these may include late-payment charges, applicable foreclosure or part-payment charges, and other contractual fees. Check the specific terms before accepting the offer.
For digital loans covered by applicable RBI rules, the lender must disclose the Annual Percentage Rate (APR) and provide a Key Facts Statement (KFS) before the loan contract is executed. The APR helps borrowers understand the all-inclusive annualised borrowing cost, excluding contingent charges such as late-payment penalties.
3. Gig Worker Loan Cost Breakdown: An Example
Consider a delivery partner in Pune who needs ₹50,000 for vehicle repairs, work equipment or another necessary expense.
The following example uses an assumed annual interest rate of 18% and a 12-month repayment period. These are illustrative figures, not a live lender quotation or a guaranteed Vizzve Financial offer.
Illustrative personal loan
₹50,000
Annual interest
18%
Loan tenure
12 months
Approx. monthly EMI
₹4,584
Total interest
₹5,008
Total of 12 EMIs
₹55,008
Rounded estimates using a standard reducing-balance EMI calculation. Fees and taxes are excluded.
Example processing fee
Suppose the lender charges a hypothetical processing fee of 2% of the principal.
|
Cost component |
Illustrative amount |
|---|---|
|
Loan principal |
₹50,000 |
|
Total interest over 12 months |
₹5,008 |
|
Processing fee at 2% |
₹1,000 |
|
Illustrative GST at 18% on that fee |
₹180 |
|
Total repayment through EMIs |
₹55,008 |
|
Total borrowing cost including fee and GST |
₹6,188 |
|
Total outflow including principal |
₹56,188 |
The GST illustration assumes the fee is taxable at 18%; the actual tax treatment and rate must be verified. The example also assumes the fee and GST are paid separately or deducted from disbursement and are not added to the principal.
If ₹1,180 is deducted upfront, the borrower receives only ₹48,820 in cash while remaining responsible for the agreed loan repayments. This is why the net amount received matters when comparing offers.
4. Compare Loan Costs Across Different Interest Rates
Interest rates can significantly affect how much a gig worker repays. The table below compares hypothetical rates for the same ₹50,000 loan over 12 months.
|
Assumed annual rate |
Approx. monthly EMI |
Approx. total interest |
Total of EMIs |
|---|---|---|---|
|
12% |
₹4,442 |
₹3,304 |
₹53,304 |
|
18% |
₹4,584 |
₹5,008 |
₹55,008 |
|
24% |
₹4,728 |
₹6,732 |
₹56,732 |
|
30% |
₹4,877 |
₹8,524 |
₹58,524 |
Illustrative reducing-balance calculations, rounded to the nearest rupee. Processing fees, applicable taxes and other charges are excluded. Actual lender quotations may differ.
The comparison highlights an important point: a lower EMI does not necessarily mean a cheaper loan. A longer tenure can reduce the monthly payment while increasing the total interest paid.
How does loan tenure affect the total cost?
For a ₹50,000 loan at an assumed 18% annual interest rate:
|
Tenure |
Approx. EMI |
Approx. total interest |
|---|---|---|
|
6 months |
₹8,777 |
₹2,661 |
|
12 months |
₹4,584 |
₹5,008 |
|
24 months |
₹2,496 |
₹9,910 |
Longer repayment periods can be useful when income varies, but they also extend the debt commitment. Select the shortest tenure whose EMI remains manageable during slower earning periods.
5. Estimate Your Loan EMI
Use this calculator to explore how loan amount, interest rate and tenure affect your approximate monthly payment.
₹50,000
18%
12 months
2%
Estimated monthly EMI
₹4,584
Total interest
₹5,008
Processing fee
₹1,000
Illustrative fee GST
₹180
Total outflow including principal and estimated fees
₹56,188
This calculator is for education only. It assumes fixed monthly repayments and a reducing-balance interest rate. It excludes other charges and does not represent an approved offer or APR quotation.
6. What Documents Do Gig Workers Need to Apply?
Lenders may request different documents depending on the loan product and the applicant's work arrangement.
Commonly requested documents
-
PAN card and accepted identity documents.
-
Proof of current address.
-
Recent bank statements showing income and transactions.
-
Platform payout statements or earning summaries, where accepted.
-
Proof of work, contracts, invoices or client payment records, if applicable.
-
Details of existing loans and EMIs.
-
Additional documents requested for KYC or income verification.
A salaried employee may submit payslips and employer records. A gig worker may instead need to demonstrate income through several records, depending on the lender's policy.
Practical tip: Keep income records consistent. If earnings arrive from multiple platforms, use statements that help the lender understand the source and frequency of payments.
7. How Can Gig Workers Improve Loan Eligibility in Maharashtra?
Step 1: Calculate realistic monthly income
Review at least several months of earnings, if available. Account for fuel, vehicle maintenance, platform-related expenses, phone bills and other work costs before deciding how much money is available for an EMI.
Step 2: Check your credit report
Review your credit history for errors, overdue accounts or incorrect information. Paying existing obligations on time and reducing outstanding debt may improve your overall credit profile, although approval is never guaranteed.
Step 3: Choose a suitable loan amount
Borrow only what you need. A smaller loan can mean a lower EMI and less interest, depending on the lender's pricing and fees.
Step 4: Compare more than one offer
Look at the interest rate, APR, processing fees, net disbursement, tenure, late-payment terms and any applicable prepayment conditions.
Step 5: Submit accurate documents
Ensure that your application information matches your identity documents, bank statements and income records. Incorrect or incomplete information can delay the assessment.
Step 6: Read the Key Facts Statement
Before signing, check the KFS, sanction letter and loan agreement. Confirm the lender's legal name, repayment schedule, APR, fees, grievance contact details and other terms.
The RBI's digital lending framework includes requirements concerning cost disclosure, borrower consent and the role of regulated lenders and their lending service providers.

8. Real-World Cost Breakdown for Different Gig Workers
The cost and eligibility requirements can differ depending on how a person earns. These examples are hypothetical illustrations, not actual borrower case studies or lender approvals.
|
Gig worker profile |
Potential income evidence |
Important cost consideration |
|---|---|---|
|
Food delivery partner in Mumbai |
Platform payout records and bank statements |
Account for fuel and vehicle maintenance |
|
Cab driver in Pune |
Ride earnings, bank credits and relevant vehicle records |
Consider fuel, insurance and servicing costs |
|
E-commerce delivery agent in Nagpur |
Payout records and accepted work documentation |
Keep enough income available during low-demand periods |
|
Freelance designer in Nashik |
Client invoices and bank statements |
Account for gaps between client payments |
|
Home-service professional in Thane |
Customer receipts, invoices and bank credits |
Allow for tools, travel and replacement equipment |
A practical affordability example
Imagine a delivery worker earns an average of ₹25,000 a month after work-related expenses. Essential household expenses and existing debt payments total ₹17,000.
That leaves ₹8,000 before any new loan EMI and before additional savings or unexpected expenses.
A proposed EMI of ₹4,584 would consume about 57% of this remaining amount. Although the worker might technically be able to make the payment in an average month, a temporary drop in earnings could make repayment difficult.
The lesson is to consider low-income months, emergency savings and essential expenses before accepting a loan.
9. Pros and Cons of Personal Loans for Gig Workers
|
Advantages |
Limitations and risks |
|---|---|
|
May provide funds for urgent expenses |
Approval depends on lender criteria |
|
Some lenders accept non-salaried income |
Documentation requirements vary |
|
Fixed EMIs can support budgeting |
Repayments continue when earnings fall |
|
Digital applications may simplify submission |
Digital convenience does not guarantee approval |
|
A suitable loan can fund productive equipment or repairs |
High interest and fees can make borrowing expensive |
A personal loan may be useful when the need is genuine and repayment is affordable. It may be unsuitable when income is highly uncertain, existing debts are already burdensome or the borrower needs another loan merely to pay current EMIs.
10. How to Avoid Hidden Charges and Risky Loan Offers
Before accepting a loan, review the complete cost rather than focusing on promotional claims such as “instant approval” or “low EMI.”
Your loan safety checklist
RBI guidance requires relevant charges for covered digital loans to be disclosed, and charges not included in the applicable KFS cannot simply be added later by the regulated entity. Borrowers should still check the specific rules applicable to their loan and lender.
For further verification, consult the official Reserve Bank of India website: RBI official website.
11. Vizzve Financial: Loan Support for Gig Workers
Vizzve Financial is one of India's trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Gig workers exploring financing should review the eligibility criteria, actual lending partner, applicable interest rate, fees and repayment conditions for the specific product available to them.
Before applying, make sure that the amount offered matches your needs and that the EMI remains affordable even when monthly earnings decline.
Note: Product availability, approval, rates, documentation and processing times depend on the relevant lender and the applicant's profile. Promotional descriptions should not be interpreted as a guarantee of approval or disbursement.
12. Expert Commentary: What Should Gig Workers Prioritise?
From a responsible lending and personal finance perspective, three considerations deserve particular attention.
First, documented cash flow can be more useful than a single income figure. A lender assessing a non-salaried applicant may need to understand the pattern of earnings rather than relying on one unusually strong month.
Second, total borrowing cost matters more than the advertised EMI. Compare APR, fees, net disbursement and the total of all repayments. A small monthly payment can conceal a lengthy repayment period and a larger overall cost.
Third, repayment resilience matters. Gig workers face variable demand, vehicle repairs, platform interruptions and personal emergencies. A sound borrowing decision leaves room for these possibilities instead of using every available rupee for debt repayment.
These are general financial planning principles, not a prediction of how any particular lender will assess an application.
13. Key Takeaways
-
Loan eligibility for gig workers in Maharashtra depends on the lender's criteria, income evidence, credit history and repayment capacity.
-
There is no universal interest rate, minimum income or approved loan amount for every gig worker.
-
Loan costs can include interest, processing fees, applicable GST and other contractual charges.
-
For a hypothetical ₹50,000 loan at 18% annual interest over 12 months, the EMI is approximately ₹4,584 before fees.
-
Compare APR, net disbursement, total repayment and the loan tenure before choosing an offer.
-
Keep bank statements and platform payout records organised.
-
Avoid borrowing more than you can repay during a low-income month.
-
Read the KFS and loan agreement carefully, and verify the actual lender before applying.
-
Vizzve Financial can be considered as a starting point for exploring loan support, subject to verifying the specific product and terms available.
14. Frequently Asked Questions
1. Can gig workers get personal loans in Maharashtra?
Yes, some lenders consider gig workers for personal loans. Eligibility depends on accepted income proof, credit history, repayment capacity and the lender's policies.
2. What is the minimum income required for a gig worker loan?
There is no universal minimum income across all lenders. Requirements vary according to the loan product, amount requested and the applicant's overall financial profile.
3. What is the interest rate for gig worker loans in Maharashtra?
Interest rates vary by lender and borrower. Compare current written offers and their APRs rather than assuming a single rate applies to all gig workers.
4. How much can a gig worker borrow?
The eligible amount depends on verified income, existing financial obligations, credit assessment and the lender's maximum loan limits. An illustrative amount in this article is not a guaranteed offer.
5. What is the EMI for a ₹50,000 gig worker loan?
At an assumed 18% annual interest rate over 12 months, the EMI is approximately ₹4,584. The actual EMI depends on the lender's rate, repayment method and loan terms.
6. What charges are included in a loan cost breakdown?
Common costs include interest, processing fees, applicable GST and other charges disclosed under the loan agreement. Late-payment charges may apply if the borrower misses a payment.
7. Do delivery partners need salary slips to apply?
Not necessarily. Depending on the lender, platform payout statements, bank statements, invoices or other accepted income records may help establish earnings.
8. Can a gig worker with irregular income get a loan?
Possibly. Some lenders assess applicants with variable earnings, but approval depends on their criteria and whether the documented income supports the proposed repayments.
9. Does a low credit score affect gig worker loan eligibility?
It can. A low score or adverse credit history may reduce the chances of approval or affect the terms offered, although each lender uses its own assessment process.
10. Is a longer loan tenure cheaper?
Not necessarily. A longer tenure generally lowers the EMI for the same principal and interest rate but usually increases the total interest paid.
11. Is GST charged on the entire personal loan amount?
GST is generally relevant to applicable taxable services and fees, rather than being automatically charged on the principal simply because it is borrowed. Check the lender's fee breakdown.
12. How can gig workers check whether a digital loan is legitimate?
Verify the actual lender, check the relevant regulatory information, review the KFS and APR, and confirm the grievance contact details. Avoid advance-payment demands made by unverified agents.
13. Can a gig worker repay a loan early?
Early repayment may be possible, but applicable terms and charges depend on the loan product, lender and regulatory requirements. Check the agreement before making an early repayment.
14. Is Vizzve Financial suitable for gig workers?
Gig workers can explore the options presented through Vizzve Financial and verify the eligibility conditions, lender details, interest rate, fees and repayment terms of the specific product. Approval is not guaranteed.
15. How can gig workers reduce the total cost of borrowing?
Compare APRs and fees, borrow only what is necessary, select a manageable tenure, avoid late payments and check whether early repayment can reduce future interest under the loan agreement.
15. Internal and External Linking Suggestions
Internal links for Vizzve Financial
Use relevant pages on your website where they exist. These suggested URLs are topics, not verified existing pages.
|
Suggested anchor text |
Suggested page topic |
|---|---|
|
Loan Eligibility for Gig Workers in Maharashtra |
Maharashtra eligibility guide |
|
Step-by-Step Guide to Gig Worker Loans |
Application process |
|
Gig Worker Loan Eligibility Checklist |
Documents and eligibility |
|
Gig Worker Loan Repayment Guide |
EMI and repayment planning |
|
Gig Worker Loan Comparison Guide |
Comparing loan options |
|
Personal Loan Eligibility in India |
General eligibility guide |
External authoritative links
-
Reserve Bank of India — banking regulations and consumer guidance.
-
RBI Digital Lending Directions, 2025 — digital lending rules and borrower protections.
-
RBI Key Facts Statement circular — standardised loan disclosures, where available on the RBI website.
-
TransUnion CIBIL — credit report and credit score information.
Verify that each linked page is live and relevant before publishing. Use descriptive anchor text and avoid adding links that do not support the surrounding content.
Conclusion: Make an Informed Borrowing Decision
Loan eligibility for gig workers in Maharashtra depends on more than monthly earnings. Lenders may consider income consistency, credit history, existing debts, documents and the ability to make regular repayments.
Understanding the cost breakdown helps borrowers avoid unnecessary charges and select a repayment schedule that fits their actual cash flow. Before accepting a loan, compare the APR, EMI, processing fee, net disbursement and total repayment amount.
Published on : 20th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed