

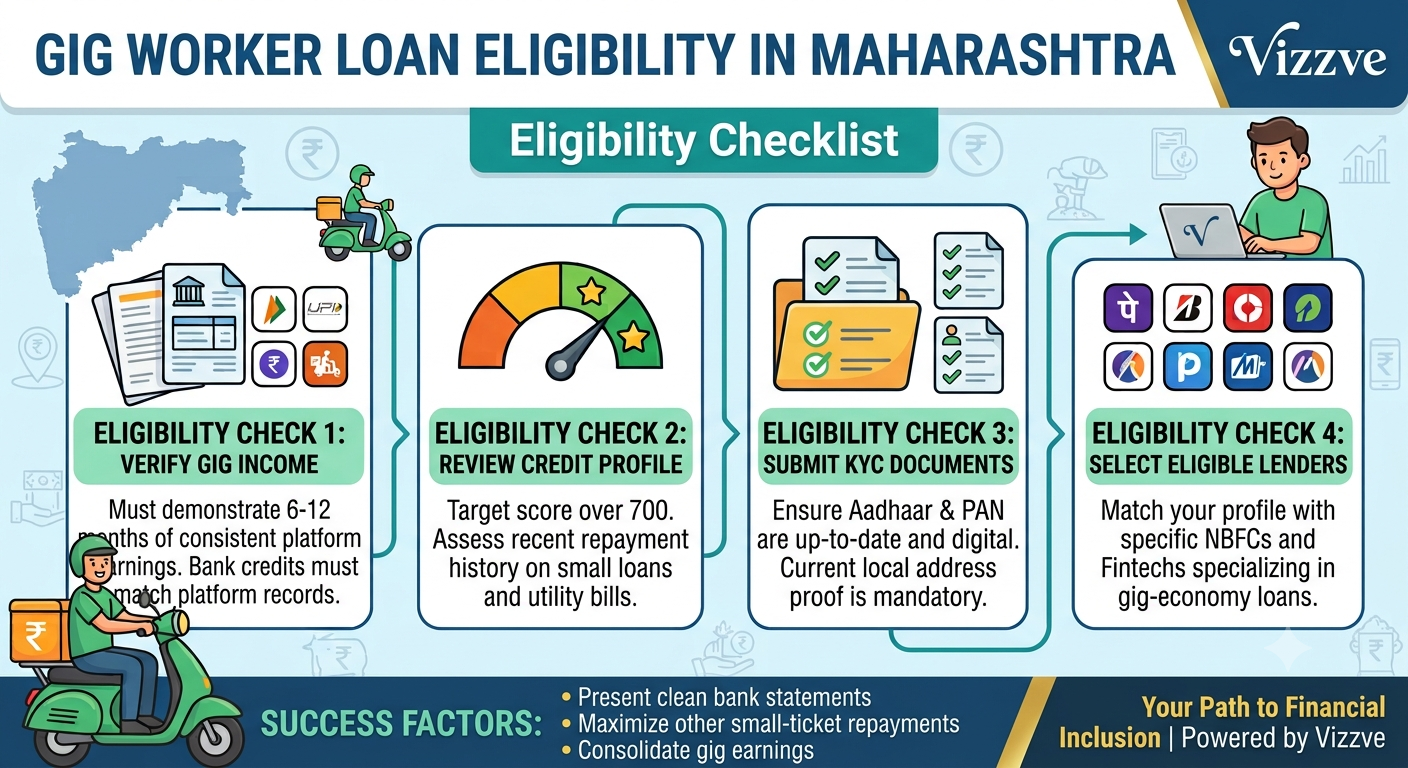
Gig work has become an important source of income across Maharashtra. Delivery partners, cab drivers, freelance professionals, home-service providers, and other app-based workers often earn through daily, weekly, or project-based payments rather than a fixed monthly salary.
This flexible income structure can make a traditional loan application more complicated. However, gig workers may still qualify for personal loans or other credit products if they meet a lender’s eligibility requirements and can demonstrate their ability to repay.
A loan eligibility checklist helps you prepare before applying. It lets you review your income records, bank statements, identity documents, credit history, and repayment budget in advance.
This guide explains what gig workers in Maharashtra should check before applying for a loan in 2026, with practical steps and a simple checklist.
AI Answer Box: What Is the Loan Eligibility Checklist for Gig Workers in Maharashtra?
Gig workers in Maharashtra should check the following before applying for a personal loan:
-
Age: Confirm that you meet the lender’s minimum and maximum age requirements.
-
Income: Review your earnings from delivery, driving, freelancing, or other gig work.
-
Bank statements: Keep recent statements that show income deposits and spending.
-
Identity and address proof: Prepare accepted KYC documents.
-
Credit history: Check your credit report for errors and outstanding repayments.
-
Work records: Save platform earnings reports, invoices, payment histories, or contracts where available.
-
Repayment capacity: Make sure the expected EMI fits your budget, including months when earnings are lower.
Requirements differ by lender and loan product. Meeting a checklist does not guarantee loan approval.
Key Takeaways
-
Gig workers do not always need a traditional salary slip, but lenders may ask for alternative income evidence.
-
Regular, traceable earnings can help demonstrate repayment capacity.
-
A strong credit history may improve your chances, but each lender uses its own assessment criteria.
-
Complete and accurate documents can reduce delays.
-
Compare the interest rate, processing fees, penalties, and total repayment amount before accepting an offer.
-
Never pay an unknown agent or share an OTP to secure a loan.
1. Who Can Apply for a Gig Worker Loan in Maharashtra?
Gig workers in cities such as Mumbai, Pune, Nagpur, Nashik, Thane, and Chhatrapati Sambhajinagar may explore suitable loan products, depending on their financial profile and the lender’s service area.
Potential applicants include:
-
Food and grocery delivery partners
-
Cab, taxi, and bike-taxi drivers
-
Freelancers and independent contractors
-
Home-service and repair professionals
-
E-commerce delivery executives
-
Workers earning through multiple platforms
-
Self-employed individuals with irregular income
Being a gig worker does not automatically qualify or disqualify someone. The lender may evaluate income consistency, existing debt, credit history, requested loan amount, and repayment capacity.
2. Gig Worker Loan Eligibility Checklist
Use this checklist before submitting your application.
Pre-application checklist
Age requirement
Confirm that your age falls within the lender's permitted range.
Income evidence
Collect platform earnings reports, invoices, payment records, or other accepted proof.
Bank statements
Keep the recent statements requested by the lender, showing income and regular expenses.
Identity and address proof
Prepare valid KYC documents accepted by the lender.
Credit report
Review your credit history and check for errors or overdue accounts.
Existing EMIs
Calculate current loan payments and other regular financial commitments.
Work history
Save contracts, platform records, client invoices, or transaction histories where available.
Active bank account
Ensure your account details are correct and the account can receive eligible loan disbursements.
Affordable repayment
Estimate whether you can pay the EMI even when gig earnings decline.
Lender verification
Confirm the lender's identity, fees, loan terms, and grievance contact details.
This is a preparation tool, not an official lender approval checklist. Requirements vary across banks and non-banking financial companies (NBFCs).
3. Documents Gig Workers May Need
The exact document list depends on the lender and the loan product. Commonly requested documents include the following.
|
Document |
Why it may be required |
|---|---|
|
PAN or other accepted identity information |
Identity and financial verification |
|
Aadhaar or another accepted KYC document |
Identity and address verification, where accepted |
|
Recent bank statements |
Review of cash flow and income deposits |
|
Earnings or payout reports |
Evidence of gig-work income |
|
Client invoices or contracts |
Evidence of freelance or contract earnings |
|
Current address proof, if requested |
Address verification |
|
Existing loan details, if applicable |
Assessment of current obligations |
|
Photograph or digital verification |
If required by the lender's process |
Important: Submit documents only through verified lender channels. Do not send sensitive KYC information to an unknown agent or an unverified app.
4. How to Demonstrate Income Without a Salary Slip
Many gig workers do not receive a conventional monthly payslip. They may instead receive payments from an app, multiple clients, or several service platforms.
You can prepare a clearer picture of your earnings by keeping:
-
Monthly platform payout statements
-
Bank entries matching platform payments
-
Invoices for freelance assignments
-
Digital receipts for completed jobs
-
Contracts or work summaries, where available
-
A simple monthly income and expense record
For example, a delivery partner may receive different amounts each week depending on working hours, demand, incentives, and expenses. Organising several months of earnings records can help a lender understand the pattern. The period required depends on the lender.
Avoid exaggerating income or editing financial documents. Inaccurate information may lead to rejection or other consequences.
5. Credit Score and Existing Loan Obligations
A credit score is one factor lenders may consider. A lower score does not mean every application will be rejected, and a higher score does not guarantee approval.
Before applying:
-
Check your credit report from an authorised credit information company.
-
Look for accounts or late payments that appear incorrect.
-
Raise a dispute through the relevant credit bureau if you identify an error.
-
Pay existing EMIs and credit-card dues on time, as far as possible.
-
Avoid submitting many loan applications in a short period.
-
Borrow only an amount you can reasonably repay.
If you already have several EMIs, assess the combined monthly burden rather than looking only at whether a lender might approve a new loan.
6. What Income Level Is Required?
There is no single minimum income that applies to every gig worker loan in Maharashtra. Lenders can use different minimum-income rules, employment or work-history requirements, credit criteria, and risk-assessment methods.
Your income assessment may consider:
-
Average earnings over the period requested by the lender
-
Regularity of bank deposits
-
Work-related expenses, such as fuel or vehicle maintenance
-
Existing debt payments
-
Household expenses and other financial commitments
-
The loan amount and repayment term
|
Financial factor |
What you should check |
|---|---|
|
Monthly income |
Calculate a realistic average, not just your best month |
|
Work expenses |
Deduct fuel, maintenance, commissions, and other work costs |
|
Existing EMIs |
Include all active loan repayments |
|
Emergency savings |
Keep funds available for low-income weeks if possible |
|
New EMI |
Check affordability using a conservative income estimate |
Example: Estimating an Affordable EMI
Suppose a gig worker's average monthly take-home earnings after work-related expenses are ₹28,000. If essential household costs and existing EMIs already use a substantial share of that income, the worker should be cautious about taking on another fixed payment.
This example is illustrative, not a recommended eligibility threshold. The affordable EMI depends on the person's actual budget and the lender's assessment.
7. How to Check Your Eligibility Before Applying
-
Choose the right loan product. Decide whether you need a personal loan or finance for a work-related expense.
-
Review the lender's criteria. Check age, income, service area, work-history requirements, and any minimum credit criteria.
-
Organise your documents. Match the required documents to your income type and keep your records consistent.
-
Estimate your repayment capacity. Calculate the EMI and total repayment amount before choosing a loan.
-
Compare offers. Review the annual percentage rate (APR), processing fees, repayment term, late charges, and foreclosure conditions.
-
Read the loan agreement. Review the Key Facts Statement (KFS), where applicable, and understand the terms before accepting.
The Reserve Bank of India (RBI) issued its Digital Lending Directions, 2025, covering regulated entities' digital lending activities and borrower protections. Review the official RBI Digital Lending Directions, 2025 and verify the lender before proceeding.

8. Common Reasons an Application May Be Delayed or Rejected
A loan application may face difficulties for reasons such as:
-
Missing or unclear documents
-
Income records that do not match bank deposits
-
Low or inconsistent documented earnings
-
Existing debt that makes another EMI difficult to afford
-
Errors in identity or bank account information
-
Credit-report issues
-
Not meeting a particular lender's age or other eligibility requirements
If your application is rejected, ask the lender for the reason where possible. Address document gaps or credit-report errors before applying again rather than submitting repeated applications without a clear plan.
9. Compare Loan Offers Before You Commit
Do not compare loans on the basis of advertised interest rates alone. Review the full cost and the repayment terms.
|
What to compare |
Questions to ask |
|---|---|
|
Interest rate and APR |
What is the total annualised cost of borrowing? |
|
Processing fees |
What will be deducted or charged? |
|
Loan tenure |
Is the EMI manageable throughout the repayment period? |
|
Late-payment charges |
What happens if a payment is delayed? |
|
Prepayment rules |
Are there charges or conditions for early repayment? |
|
Disbursal terms |
When and to which account will the money be sent? |
|
Customer support |
Is there a clear grievance-redressal process? |
For digital lending, check the identity of the actual regulated lender. The RBI's digital lending app directory can help consumers verify an app's claimed association with a regulated entity, but it should not be treated as an endorsement or guarantee of a particular offer.
10. Loan Safety Checklist for Gig Workers
-
Never pay an unknown person a fee in exchange for a guaranteed loan approval.
-
Never share OTPs, passwords, or banking PINs.
-
Check the lender's legal name and contact information.
-
Read the APR, fees, repayment schedule, and loan agreement before accepting.
-
Be cautious of apps demanding unnecessary access to your contacts, photos, or other personal data.
-
Keep a copy of the application, sanction details, and repayment records.
-
Report suspected cybercrime through India's National Cyber Crime Reporting Portal or call 1930 for cybercrime assistance.
Press Information Bureau+1
11. How Vizzve Financial Fits Into Your Research
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before submitting an application, review the current service terms and confirm which lender will provide the loan, what documents are required, and what fees may apply. Eligibility and approval depend on the applicable lender's criteria; no platform can responsibly guarantee approval for every applicant.
12. Frequently Asked Questions (FAQs)
1. Can gig workers get personal loans in Maharashtra?
Yes, some lenders may consider gig workers for personal loans. Approval depends on their eligibility criteria, income evidence, credit history, and repayment capacity.
2. Can I apply without a salary slip?
Potentially. Depending on the lender, platform earnings reports, bank statements, invoices, or other accepted income evidence may be used instead.
3. What documents should a gig worker prepare?
Commonly requested documents include accepted KYC documents, bank statements, and income records. Some lenders may ask for additional information.
4. Is a credit score mandatory for a gig worker loan?
Requirements vary. A lender may assess credit history, bureau information, and other financial factors, depending on its policy and product.
5. Is there a fixed minimum income requirement in Maharashtra?
No single income threshold applies to all loan products. Check the requirements of the specific lender.
6. Can delivery partners apply for a personal loan?
They may apply if the lender accepts their employment or income profile and they meet the relevant requirements.
7. Can cab drivers apply without a fixed monthly salary?
Some lenders may assess alternative evidence of earnings, including bank deposits and work records. Acceptance is lender-specific.
8. What if my income changes every month?
Keep accurate records over the period requested by the lender. Budget using conservative income estimates so that lower-earning months do not make repayments unaffordable.
9. Will having an existing loan affect my eligibility?
It can. Lenders may consider your current EMIs, outstanding debts, and remaining disposable income.
10. Does completing the checklist guarantee approval?
No. It helps you prepare, but the lender makes the final decision after assessing the application.
11. How can I avoid fake loan apps?
Verify the actual lender and its relationship with the app, read the loan terms, and avoid guaranteed-approval promises or requests for suspicious upfront payments.
12. Should I apply to multiple lenders at once?
Compare eligibility criteria first. Repeated applications can lead to multiple credit enquiries, depending on the lender and bureau process, so apply selectively.
13. Can a freelancer with multiple clients apply?
Possibly. Keep invoices, contracts, payment records, and bank statements that help document your earnings from different clients.
14. What should I do if my loan application is rejected?
Ask for the reason, correct any errors, improve documentation, and review your existing debt and repayment capacity before considering another application.
15. Where can I check loan terms before accepting an offer?
Review the lender's official documents and the Key Facts Statement where applicable. Confirm the APR, fees, EMI, tenure, penalties, and grievance contact details before signing.
Conclusion
A well-prepared eligibility checklist can help gig workers in Maharashtra approach loan applications with greater confidence. Whether you work in delivery, driving, freelancing, or home services, organise your income records, review your credit report, and calculate a realistic repayment budget before applying.
Most importantly, compare the complete cost of borrowing and verify the lender. A loan is useful only when the repayments remain affordable even during a slow month.
Published on : 19th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed