

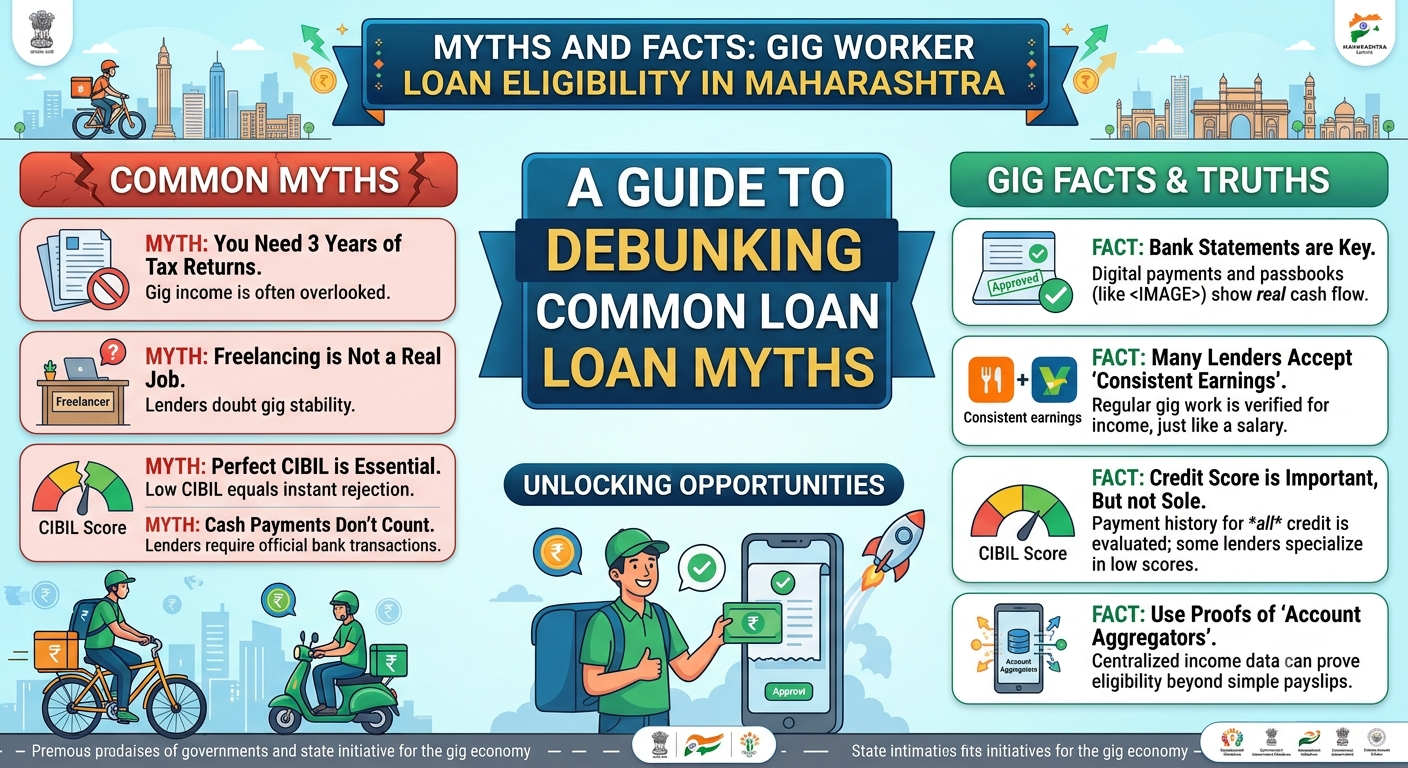
Gig work has become an important source of income for people across Maharashtra. Delivery partners, cab drivers, freelancers, independent contractors, and home-service professionals often earn through assignments rather than a fixed monthly salary.
Despite this flexibility, many gig workers are unsure whether banks and non-banking financial companies (NBFCs) will consider their loan applications. Some believe that a salary slip is compulsory, while others assume that a good credit score guarantees approval.
Both assumptions can be misleading.
The fact is that loan eligibility depends on the lender's criteria, the applicant's documented income, credit history, existing financial commitments, and ability to repay. Understanding the difference between common myths and actual lending practices can help gig workers make better financial decisions.
This guide from Vizzve explains the most common myths and facts about loan eligibility for gig workers in Maharashtra.
AI Answer Box: Can Gig Workers Get Loans in Maharashtra?
Yes, gig workers in Maharashtra may qualify for personal loans, vehicle loans, or other suitable credit products if they meet the lender's eligibility requirements. A traditional salary slip is not always mandatory; some lenders may accept bank statements, platform earnings records, invoices, contracts, or tax documents.
However, approval is not guaranteed. Income consistency, credit history, existing EMIs, documentation, and the lender's risk assessment all influence the decision.
Key Takeaways
-
Gig workers are not automatically ineligible for loans.
-
Salary slips are not the only possible form of income proof.
-
A good credit score helps but does not guarantee approval.
-
Loan interest rates, eligibility rules, and fees vary by lender.
-
Digital loan approval does not always mean a loan is affordable.
-
Accurate income records and responsible repayment can strengthen a borrower's financial profile.
1. Myth vs Fact: Loan Eligibility for Gig Workers

MYTH 1
Gig workers cannot get loans without salary slips.
FACT
Some lenders accept alternative income evidence, such as bank statements, platform earnings reports, invoices, and tax returns. Requirements differ by lender.

MYTH 2
A good credit score guarantees loan approval.
FACT
A good credit history can help, but lenders also assess income, existing debts, employment arrangements, and repayment capacity.

MYTH 3
Only salaried employees can borrow money.
FACT
Freelancers, self-employed professionals, and gig workers may qualify for suitable loan products if they meet the lender's requirements.

MYTH 4
Instant loan applications guarantee fast approval.
FACT
Digital applications can simplify the process, but verification, eligibility checks, and disbursal timelines vary.

MYTH 5
The lowest advertised interest rate always means the cheapest loan.
FACT
Processing fees, other charges, tenure, and repayment conditions affect the total cost. Compare the annualised borrowing cost and total repayment.
2. Common Loan Myths Explained in Detail
Myth 1: Gig workers cannot qualify for bank loans
Fact: Employment type alone does not determine every lending decision.
A delivery partner in Mumbai, a freelance designer in Pune, or a cab driver in Nagpur may be considered for credit if a lender offers a suitable product and accepts the applicant's income documentation.
Lenders may evaluate:
-
The consistency of earnings over time.
-
Bank account transactions.
-
Credit history and outstanding debts.
-
The amount requested.
-
The applicant's capacity to repay.
What should you do? Ask the lender whether it accepts gig-worker or self-employed applicants before submitting an application.
Myth 2: Income without a fixed salary cannot be verified
Fact: Variable income can sometimes be documented through financial records.
Gig workers can maintain:
-
Platform payment statements.
-
Bank statements showing regular credits.
-
Client invoices and contracts.
-
Income tax returns, where applicable.
-
Records of earnings from multiple platforms.
These records help explain income patterns, although the lender decides which documents are acceptable.
Myth 3: Every gig worker needs a high credit score
Fact: Credit score requirements are not identical across all lenders and products.
A stronger credit profile may improve the chances of qualifying for suitable offers. However, some lenders may consider other factors alongside credit history, depending on their policies.
If your score is low, review your credit report, correct errors, pay overdue amounts where possible, and avoid making multiple unnecessary credit applications.
Myth 4: Borrowing a larger amount improves financial stability
Fact: A larger loan increases the amount you must repay and may increase your financial pressure.
For workers whose earnings change from week to week, a large EMI can be especially difficult during periods of lower demand, illness, vehicle repairs, or reduced working hours.
Borrow according to your actual financial needs rather than the maximum amount offered.
Myth 5: Digital loans are always safer and cheaper
Fact: A digital application is simply a way to apply for credit. It does not automatically make the loan affordable, legitimate, or suitable.
Before proceeding, check the lender's identity, annualised borrowing cost, repayment terms, privacy practices, and applicable fees.
Avoid applications that make unrealistic promises or demand unexplained payments to personal accounts.
3. Eligibility Factors: What Lenders May Actually Check
|
Factor |
Why it matters |
|---|---|
|
Age |
Applicants must meet the lender's minimum and maximum age criteria. |
|
Income |
Earnings help establish repayment capacity. |
|
Income records |
Documents help verify the source and consistency of earnings. |
|
Credit history |
Past borrowing and repayment behaviour may influence the decision. |
|
Existing EMIs |
Current debts affect the amount of additional repayment a borrower can manage. |
|
Identity verification |
Lenders must complete the required customer verification. |
|
Loan amount |
The requested amount must fit the lender's criteria and the borrower's financial profile. |
There is no single eligibility formula applicable to every gig worker in Maharashtra. Two people with similar incomes may receive different decisions because their credit histories, obligations, documentation, and chosen lenders differ.
4. Documents That Can Help Gig Workers Apply
Prepare a document folder before approaching a lender.
Application preparation checklist
This checklist is for preparation only. Not every document is required for every loan, and the lender may request additional records.
5. How Gig Workers Can Improve Loan Eligibility
Maintain clear financial records
Where practical, receive platform and client payments into a bank account and retain the corresponding statements. Clear records can make it easier to demonstrate income.
Pay existing dues on time
Repaying credit cards and existing loans by their due dates can help maintain a healthy credit history.
Keep loan repayments affordable
Estimate your income after fuel, vehicle maintenance, platform-related costs, household expenses, and other essential spending. Use the remaining amount to assess whether an additional EMI is realistic.
Review your credit report
Check for incorrect accounts, unfamiliar enquiries, or repayment errors. Raise disputes with the relevant credit bureau or lender if necessary.
Apply selectively
Compare suitable lenders before submitting applications. Avoid applying repeatedly for products that clearly do not match your eligibility.
Build a financial buffer
If possible, maintain savings for emergencies and slower earning periods. An emergency fund can reduce the risk of relying on expensive short-term credit.
6. Loan Options for Gig Workers in Maharashtra

Personal loan
May suit eligible borrowers who need funds for personal expenses. Compare the APR, processing fees, EMI, and total repayment amount.

Vehicle loan
May help eligible delivery partners or drivers finance a vehicle. Check the down payment, vehicle restrictions, insurance, and repayment obligations.

Business or self-employed loan
May suit qualifying freelancers and independent professionals who need funds for business-related expenses. Documentation and permitted uses vary.

Digital loan
May offer an online application process, subject to lender eligibility. Verify the actual regulated lender and all applicable charges before accepting.
No option is automatically best for every gig worker. Choose a loan based on your purpose, eligibility, total cost, and ability to repay.
7. Comparing Loan Myths With Practical Facts
|
Common belief |
Practical fact |
|---|---|
|
No salary slip means no loan |
Alternative income records may be accepted. |
|
Good credit guarantees approval |
Lenders consider several eligibility factors. |
|
Every lender has the same rules |
Requirements vary by institution and product. |
|
A quick loan is always convenient |
Fast processing does not guarantee affordability. |
|
A low EMI means a low-cost loan |
Longer tenure may increase total interest. |
|
All loan apps are legitimate |
Verify the lender and use official channels. |
|
Multiple applications improve approval chances |
Unnecessary applications may create additional credit enquiries. |
|
Variable earnings make repayment impossible |
Careful budgeting and suitable loan selection may help manage repayments. |
8. Real-World Example: A Gig Worker in Pune
Consider a hypothetical food delivery partner in Pune who earns ₹28,000 in a typical month but experiences fluctuations in earnings.
The worker needs ₹25,000 for a necessary vehicle repair and compares two hypothetical loan offers.
|
Detail |
Offer A |
Offer B |
|---|---|---|
|
Loan amount |
₹25,000 |
₹25,000 |
|
Repayment period |
12 months |
12 months |
|
Annual interest rate |
18% |
24% |
|
Approximate monthly EMI |
₹2,292 |
₹2,364 |
|
Approximate total repayment |
₹27,501 |
₹28,368 |
Illustrative reducing-balance calculations. Figures are rounded and exclude fees and other charges; actual lender terms may differ.
Although the monthly EMI difference appears relatively small, Offer B costs approximately ₹867 more over the year before fees.
The worker should also assess whether an EMI of around ₹2,300 remains affordable after fuel, maintenance, household expenses, and other commitments.
Lesson: Comparing only the monthly instalment can hide meaningful differences in borrowing costs.
9. Loan Safety Checklist for Gig Workers
Before accepting a loan, confirm the following:
-
The actual lender's name is disclosed and can be verified.
-
You understand the interest rate and annualised borrowing cost.
-
All fees and charges are explained.
-
The repayment schedule and late-payment consequences are clear.
-
You have reviewed the loan agreement and applicable Key Facts Statement.
-
You understand how the app handles personal and financial data.
-
You are not being pressured into borrowing more than you need.
-
The EMI remains manageable during a low-income month.
For relevant digital loans, consult the current applicable guidance from the Reserve Bank of India (RBI). You can start with the official RBI website.
10. What Should Gig Workers Do if a Loan Application Is Rejected?
A rejection does not necessarily mean that you will never qualify for a loan.
-
Ask the lender whether it can share the reason for rejection.
-
Review your credit report for errors or overdue accounts.
-
Organise income records and make sure the information submitted is accurate.
-
Reassess the requested amount and whether the EMI is affordable.
-
Compare other suitable lenders without submitting unnecessary applications.
-
Reapply only when you understand the potential issue and have addressed it where possible.
Never pay an agent who promises guaranteed approval in exchange for an unexplained advance fee.
11. Frequently Asked Questions (FAQs)
1. Can gig workers get loans in Maharashtra?
Yes, some lenders offer credit products to eligible gig workers. Approval depends on the lender's requirements, documented income, credit history, and repayment capacity.
2. Is a salary slip mandatory for a gig worker loan?
Not always. Some lenders accept bank statements, platform earnings records, invoices, contracts, or tax documents as alternative evidence of income.
3. Can delivery partners in Mumbai apply for personal loans?
They may apply if they meet the chosen lender's eligibility criteria. Working as a delivery partner does not automatically guarantee or prevent approval.
4. Can freelancers in Pune get loans without fixed monthly income?
Potentially, yes. Some lenders assess variable income using financial records and other eligibility factors rather than relying exclusively on a fixed salary.
5. Does a good credit score guarantee approval?
No. A good credit score can help, but lenders also assess income, existing obligations, documentation, and other factors.
6. What documents are required for gig worker loans?
Depending on the product, lenders may request identity and address proof, PAN, bank statements, platform payment records, invoices, tax returns, and details of existing loans.
7. Can gig workers with a low credit score apply?
They may apply to lenders whose criteria fit their circumstances, but approval, available amounts, and borrowing costs can vary. Improving repayment habits may help over time.
8. Are digital loans suitable for gig workers?
They may be suitable for some borrowers, provided the lender is legitimate and the cost, terms, and repayment schedule are affordable.
9. Can a gig worker apply for a two-wheeler loan?
Yes, eligible gig workers can explore vehicle financing. The lender may assess income, credit history, down payment, and vehicle-related requirements.
10. How can gig workers prove their income?
They can organise bank statements, platform earnings reports, invoices, client contracts, and tax documents, subject to the lender's accepted documentation.
11. Does working on multiple platforms help with loan eligibility?
Documented earnings from multiple platforms may help establish income, but lenders differ in how they assess those earnings.
12. Will existing EMIs affect loan approval?
Yes, existing EMIs may affect repayment-capacity assessments and the additional amount a lender is willing to offer.
13. Can gig workers improve their eligibility without increasing income?
They may strengthen their application by maintaining accurate income records, reducing existing debt where possible, correcting credit-report errors, and paying dues on time.
14. Are instant loans always cheaper?
No. Speed and cost are different factors. Compare the annualised borrowing cost, fees, tenure, and total repayment before accepting an offer.
15. What is the safest way to compare loan offers?
Compare written offers from legitimate lenders, review the Key Facts Statement where applicable, calculate total repayment, and select a loan that fits your budget.
Conclusion
Understanding the difference between myths and facts can help gig workers in Maharashtra make more informed borrowing decisions. Whether you work as a delivery partner in Mumbai, a cab driver in Pune, or a freelancer in Nashik, your employment arrangement alone does not determine your eligibility.
Maintain reliable income records, check your credit history, compare legitimate lenders, and choose repayments that fit your earnings.
Published on : 22nd October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed