

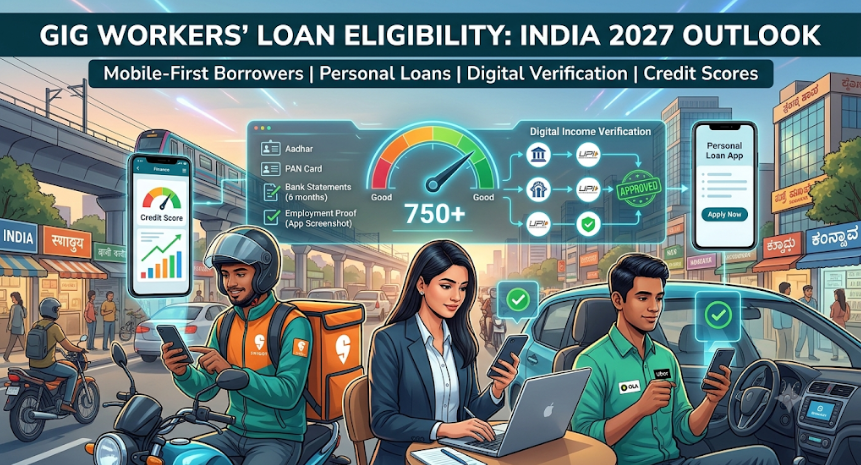
Introduction
India's employment landscape is changing. Many people now earn through digital platforms, independent projects and flexible work arrangements rather than traditional full-time jobs.
Delivery partners, cab drivers, freelancers, online tutors, home-service professionals and independent contractors are important participants in this changing workforce.
For these workers, accessing personal loans can sometimes be challenging. Their earnings may be regular over time, but they may not receive a fixed monthly salary or conventional salary slips. Some receive weekly platform settlements, while others earn through multiple clients and projects.
This creates an important question:
Will gig workers find it easier to qualify for personal loans in India in 2027?
The outlook is potentially encouraging. Digital lending systems, electronic income records, improved credit information and alternative documentation may give lenders more ways to understand a borrower's financial position.
However, these developments do not guarantee that every gig worker will qualify for a loan. Banks and NBFCs will continue to assess income, existing debt, credit history, repayment capacity and their own lending policies.
This guide explains what mobile-first borrowers should understand about gig worker loan eligibility, expected developments in 2027, required documents and responsible borrowing.
AI Answer Box: What Is the 2027 Outlook for Gig Worker Loan Eligibility?
Gig workers in India may find more digital ways to demonstrate their income and apply for personal loans in 2027. Lenders may increasingly use bank statements, platform earning records, invoices, digital payment information and other permitted financial documents to assess applicants who do not receive traditional salary slips.
Loan approval will still depend on verified income, credit history, existing EMIs, repayment capacity and lender-specific eligibility requirements.
In simple terms: Gig workers may have more opportunities to demonstrate their earnings, but there is no universal loan eligibility rule or guaranteed approval for gig workers in 2027.
1. Who Are Mobile-First Gig Workers?
Mobile-first gig workers are individuals who use smartphones and digital platforms to find work, complete assignments, receive payments and manage their earnings.
Unlike traditional salaried employees, they may work with multiple platforms or clients.
Common examples of mobile-first gig workers
-
Food delivery partners
-
Grocery and parcel delivery executives
-
Cab and bike taxi drivers
-
Freelance graphic designers
-
Digital marketing professionals
-
Online tutors
-
Independent consultants
-
Home-service professionals
-
Part-time service providers
-
Freelance writers and content creators
Why are mobile-first borrowers different?
Their income records may be spread across several digital platforms, bank accounts and payment channels.
For example, a delivery partner may receive weekly settlements, while a freelance designer may receive payments from three different clients during the same month.
This makes income verification different from the conventional salary-based assessment used for many salaried applicants.
2. Why Is Gig Worker Loan Eligibility Important in 2027?
As digital work arrangements develop, lenders need to understand different types of income.
A borrower should not automatically be considered financially unstable simply because they do not receive a traditional salary. At the same time, lenders must verify whether the income is sufficient and consistent enough to support regular loan repayments.
Key reasons the topic matters
1. Changing employment patterns
More people are earning through independent assignments, platform-based work and flexible employment arrangements.
2. Growing use of digital payments
Electronic payment records may help borrowers demonstrate where their earnings come from.
3. Demand for convenient loan applications
Mobile-first borrowers often prefer digital application processes that reduce unnecessary branch visits.
4. Better financial information
Credit information reporting and digital verification systems can help lenders obtain more current information.
5. Responsible financial inclusion
A suitable assessment process may help lenders evaluate applicants who do not fit conventional salary-based categories.
3. What Could Change for Gig Worker Loan Eligibility in 2027?
The following developments represent possible trends, not guaranteed changes across every bank, NBFC or lending application.
| Expected development | Possible effect on borrowers | Important limitation |
|---|---|---|
| Digital income verification | Easier submission of earning records | Documents must be accepted by the lender |
| Better financial data analysis | More detailed income assessment | Data accuracy remains essential |
| Automated underwriting | Potentially faster processing | Complex applications may need manual review |
| More frequent credit information updates | More current credit records | Does not guarantee approval |
| Mobile-first applications | Convenient application process | KYC and verification still apply |
| Alternative income documentation | Potentially broader assessment options | Not every lender accepts every document |
3.1 Greater use of digital income records
A lender may consider electronic records to understand how a gig worker earns money.
Depending on its policy, accepted documents could include:
-
Platform earning statements
-
Bank statements
-
Client invoices
-
Payment settlement records
-
Business transaction records
-
Income tax returns
The important point is that digital records must be genuine, relevant and verifiable.
3.2 More flexible income assessment
Traditional salary-based lending often relies on fixed monthly income information.
For gig workers, lenders may need to examine average earnings over several months and consider income fluctuations.
For example, a delivery partner may earn more during festive periods and less during quieter months. A responsible assessment should consider this variation rather than relying only on the highest earning month.
3.3 More digital loan processing
Online applications may make it easier to submit information, complete KYC and receive loan-related updates.
However, a fully digital application does not necessarily mean instant approval or automatic disbursal.
4. What Are the Eligibility Criteria for Gig Workers in India?
There is no single eligibility formula for every gig worker personal loan.
Each bank or NBFC sets its own conditions based on the loan product, applicant profile and applicable regulatory requirements.
The following factors are commonly relevant.
4.1 Age requirement
Lenders specify minimum and maximum age limits for applicants.
The permitted age range varies depending on the lender and loan product. Applicants should check the current conditions before applying.
4.2 Verified monthly income
A gig worker should be able to demonstrate a genuine and reasonably consistent income source.
Lenders may examine:
-
Average monthly earnings
-
Frequency of payments
-
Source of income
-
Recent income fluctuations
-
Bank account activity
-
Existing financial commitments
4.3 Credit score and repayment history
Credit history helps lenders understand how an applicant has managed previous borrowing.
They may consider:
-
Previous loan repayment records
-
Credit card payment history
-
Outstanding loan balances
-
Credit utilisation
-
Recent credit enquiries
-
Reported defaults or overdue accounts
A good credit score may strengthen an application, but it does not guarantee loan approval.
4.4 Existing EMIs
Existing loan repayments reduce the income available for a new EMI.
A borrower with several active loans may qualify for a lower amount or may not meet the lender's affordability criteria.
4.5 Employment or work continuity
Lenders may examine how long the applicant has been working and whether earnings are reasonably consistent.
The required work history differs between financial institutions.
4.6 Bank account activity
Bank statements can help establish the movement and source of income.
Lenders may review incoming payments, regular expenses, loan deductions and account activity.
5. Documents Required for Gig Worker Loans in 2027
Gig workers may not have conventional salary slips. Depending on the lender, other documents may be accepted to demonstrate income.
| Document | Purpose |
|---|---|
| PAN card | Identity and financial verification |
| Accepted identity proof | Identity verification |
| Address proof | Address verification |
| Bank statements | Income and transaction assessment |
| Platform earnings statement | Evidence of platform-based income |
| Payment settlement records | Evidence of received earnings |
| Freelance invoices | Evidence of client work |
| Contracts or work orders | Evidence of professional assignments |
| Income tax returns | Supporting income documentation |
| Existing loan details | Assessment of current debt obligations |
Can gig workers apply without salary slips?
Yes, some lenders may accept alternative income documents instead of salary slips.
For example, a delivery partner may be able to provide platform earning statements and bank records, while a freelancer may provide invoices and client payment records.
However, the acceptance of these documents depends on the actual lending institution.
Before applying, ask the lender which documents it accepts for non-salaried applicants.
6. Loan Eligibility for Different Types of Gig Workers
Different occupations have different earning patterns. A suitable loan assessment may need to consider these differences.
6.1 Delivery partners
Delivery partners may receive payments based on completed orders, incentives and platform settlements.
Possible income records include:
-
Monthly or weekly earning statements
-
Platform payment reports
-
Bank statements showing settlements
-
Other accepted financial records
6.2 Cab and bike taxi drivers
Drivers may earn through completed rides, incentives and other transport-related services.
Possible income records include:
-
Ride earnings summaries
-
Platform settlement reports
-
Bank statements
-
Accepted business or vehicle-related documents, where required
6.3 Freelancers
Freelancers may receive income from multiple clients and projects.
Possible income records include:
-
Client invoices
-
Bank statements
-
Contracts
-
Payment receipts
-
Income tax returns
6.4 Independent service providers
Technicians, tutors, beauty professionals and repair specialists may receive direct customer payments or platform-based earnings.
Possible income records include:
-
Digital payment statements
-
Customer invoices
-
Bank transaction records
-
Business income documents
7. How Will Lenders Calculate Gig Worker Loan Eligibility?
Lenders generally assess the applicant's verified income, financial obligations and repayment capacity.
A simplified assessment may involve:
-
Average verified monthly income.
-
Existing loan EMIs.
-
Other financial commitments.
-
Credit history.
-
Proposed loan tenure.
-
Interest rate and expected EMI.
-
Lender-specific eligibility conditions.
Example: Understanding repayment capacity
Suppose a gig worker has the following monthly financial details:
| Financial details | Amount |
|---|---|
| Average monthly income | ₹40,000 |
| Existing loan EMIs | ₹6,000 |
| Essential monthly expenses | ₹20,000 |
| Remaining amount before a new EMI | ₹14,000 |
The remaining ₹14,000 should not automatically be treated as available EMI capacity.
The borrower should also consider income fluctuations, emergencies, medical expenses, vehicle maintenance and other unexpected costs.
Important: This is an illustrative household-budget calculation, not an official lender eligibility formula or a promise of loan approval.
8. The Role of AI and Digital Lending in Gig Worker Loans
Artificial intelligence and digital lending technology may influence how lenders assess applications in 2027.
These technologies can help analyse information and identify patterns, but they should operate within appropriate regulatory and risk-management controls.
Potential applications of AI in lending
| Technology | Possible use |
|---|---|
| Income pattern analysis | Reviewing income consistency |
| Automated document checks | Identifying incomplete or inconsistent records |
| Credit risk models | Supporting repayment-risk assessment |
| Fraud detection | Flagging suspicious application activity |
| Digital underwriting | Supporting faster application processing |
| Data analysis | Reviewing permitted financial information |
Will AI automatically approve gig worker loans?
No. AI may support the assessment process, but the lending institution remains responsible for its credit decision.
An applicant may still be rejected if income cannot be verified, existing debt is too high or the application does not meet the lender's eligibility rules.
9. RBI Digital Lending Rules: What Mobile-First Borrowers Should Know
The Reserve Bank of India issued the Reserve Bank of India (Digital Lending) Directions, 2025 on May 8, 2025.
These directions apply to the digital lending activities of specified RBI-regulated entities, including banks and NBFCs.
Important areas include:
-
Borrower creditworthiness assessment
-
Loan disclosures
-
Key Facts Statement requirements
-
Loan disbursal and repayment arrangements
-
Cooling-off requirements
-
Grievance redressal
-
Collection and use of borrower data
-
Data storage and privacy requirements
Why do these rules matter to gig workers?
Gig workers applying through digital platforms should understand that a mobile application is not the same as the actual lender.
Before accepting an offer:
-
Identify the bank or NBFC providing the loan.
-
Check the lender's official website.
-
Read the Key Facts Statement.
-
Review the interest rate and APR.
-
Understand applicable fees and charges.
-
Check the grievance redressal process.
-
Review the privacy policy and data permissions.
A genuine digital lending process should provide clear loan information and appropriate borrower protections.
10. How Credit Information Reporting May Affect Gig Workers in 2027
Credit information is an important part of personal loan assessment.
RBI's credit information reporting framework was updated to support more frequent reporting by applicable credit institutions.
From July 1, 2026, the relevant amended reporting framework provides for credit information submissions based on reference dates of the 9th, 16th, 23rd and last day of the month, subject to the applicable directions.
What does this mean for borrowers?
-
Credit records may reflect account changes more frequently.
-
Lenders may have access to more current credit information.
-
Recent repayments and outstanding obligations may become visible sooner, subject to reporting and processing timelines.
-
Borrowers should continue checking their credit reports for errors.
More frequent reporting does not automatically increase a credit score or guarantee loan approval.
11. Social Security Developments and the Gig Economy: Why They Matter
The Code on Social Security, 2020, includes provisions relating to gig workers and platform workers.
The Code came into force on November 21, 2025. The Social Security (Central) Rules, 2026, notified on May 8, 2026, provide further implementation detail relating to registration, worker-related information and social security arrangements.
How could this affect gig workers?
The broader social security framework may help strengthen formal recognition and access to applicable welfare measures.
Potential areas of support include:
-
Social security registration
-
Accident-related protection
-
Health and other welfare schemes
-
Improved worker-related records
-
Greater formal recognition of platform-based work
Does social security registration guarantee a personal loan?
No.
Social security benefits and personal loan eligibility are separate matters.
Registration may help establish a worker's identity within an applicable welfare framework, but it does not automatically establish income eligibility, improve a credit score or guarantee loan approval.
12. Mobile-First Loan Application Process for Gig Workers
A mobile phone can help gig workers submit applications and manage documents without visiting a branch for every step.
Step-by-step application guide
Step 1: Identify the actual lender
Choose a bank or NBFC and verify the digital platform through its official website.
Step 2: Check eligibility conditions
Review age, income, credit history and accepted documentation requirements.
Step 3: Organise income documents
Prepare recent bank statements, platform earnings reports, invoices and other accepted records.
Step 4: Complete the application
Enter accurate personal, occupation and income details.
Step 5: Complete KYC
Follow the lender's official identity verification process.
Step 6: Submit income evidence
Upload only the requested documents through the lender's official and secure channel.
Step 7: Review the loan offer
Check the loan amount, interest rate, APR, EMI, tenure and charges.
Step 8: Read the agreement
Review the Key Facts Statement and loan agreement before accepting.
Step 9: Save your records
Keep copies of the sanction letter, loan agreement, repayment schedule and payment receipts.
13. How Can Gig Workers Improve Their Loan Eligibility in 2027?
Borrowers can take several practical steps to make their financial position easier to assess.
1. Maintain clear bank records
Where practical, receive work-related payments into a consistent bank account.
2. Download platform earning statements
Save monthly or weekly reports from the platforms through which you work.
3. Maintain accurate income details
Do not overstate monthly earnings. Use realistic figures based on documented income.
4. Pay existing EMIs on time
Consistent repayment behaviour can support a healthy credit profile.
5. Reduce unnecessary borrowing
Avoid taking multiple loans simply to meet short-term expenses.
6. Check your credit report
Review reported accounts, outstanding balances and repayment records. Dispute inaccurate information through the appropriate channels.
7. Prepare for income fluctuations
Calculate affordability using an average or lower-income month rather than assuming that every month will be equally profitable.
8. Compare loan costs
Review APR, processing charges, applicable taxes, EMI and total repayment before accepting an offer.
14. Common Mistakes Mobile-First Borrowers Should Avoid
| Mistake | Why it is risky | Better approach |
|---|---|---|
| Reporting inflated income | Can lead to verification problems | Provide realistic documented earnings |
| Uploading unclear screenshots | May delay document verification | Submit clear official records |
| Ignoring existing EMIs | Can lead to poor affordability decisions | Disclose existing debt |
| Applying through unknown apps | May expose personal information | Verify the actual lender |
| Sharing OTPs or PINs | Can lead to financial fraud | Never disclose confidential credentials |
| Accepting the highest available amount | Can increase repayment stress | Borrow only what is necessary |
| Ignoring the APR | Can hide the overall cost of borrowing | Compare total loan costs |
15. Pros and Cons of Digital Personal Loans for Gig Workers
| Potential advantages | Potential disadvantages |
|---|---|
| Convenient online applications | Approval is not guaranteed |
| Less dependence on physical paperwork in some cases | Document requirements vary |
| May support alternative income verification | Not all lenders accept alternative documents |
| Faster processing for some applications | Verification can still take time |
| Easier access to loan information | Fake loan apps remain a concern |
| Can support planned financial needs | Interest and fees increase borrowing costs |
Digital lending can improve convenience, but borrowers should not sacrifice safety or affordability for speed.
16. Future Outlook: What Could Gig Worker Lending Look Like in 2027?
The following are reasonable possibilities to watch in 2027. They should not be treated as confirmed changes across the Indian lending industry.
More recognition of non-salaried income
Lenders may continue exploring ways to assess workers whose earnings come from multiple platforms, clients or assignments.
Improved mobile-based verification
Digital document submission and financial information checks may become more convenient.
More detailed affordability assessments
Lenders may increasingly focus on income fluctuations and existing financial obligations rather than relying only on one month's earnings.
Greater attention to borrower protection
Privacy, clear disclosures, grievance redressal and responsible lending are likely to remain important as digital lending develops.
More informed credit decisions
More frequent credit information reporting may support better-informed lending decisions when the data is accurate and available.
The overall direction may be towards more flexible assessment methods, but the speed and extent of adoption will differ between lenders.
17. Expert Perspective: What Should Responsible Gig Worker Lending Focus On?
A responsible lending process should recognise that a gig worker's income structure may differ from that of a salaried employee.
The absence of a salary slip should not automatically be treated as proof of an inability to repay. At the same time, digital income records should not be accepted without appropriate verification.
Three factors are particularly important:
Verified income: The lender should understand the source, frequency and consistency of earnings.
Realistic repayment capacity: The proposed EMI should remain affordable after existing debt and essential expenses.
Transparent loan terms: Borrowers should understand the total cost, repayment schedule, applicable charges and complaint process.
Technology can support these goals, but it cannot replace sound credit assessment or responsible lending practices.
18. Real-World Examples: How Gig Workers May Be Assessed in 2027
These examples are illustrative scenarios and do not represent actual customer cases or lender approval decisions.
Example 1: Food delivery partner
A delivery partner receives weekly payments from a platform and maintains bank statements and monthly earning reports.
A lender that accepts these documents may review average earnings, income consistency and existing financial obligations.
Example 2: Freelance digital marketer
A freelance digital marketer works with several clients and receives payments on different dates.
Invoices, client contracts and bank records may help demonstrate the source of income if the lender accepts these documents.
Example 3: App-based cab driver
A cab driver receives ride payments and incentives. The lender may review platform earnings summaries and bank transactions to understand the worker's income pattern.
In every case, approval depends on the lender's verification, eligibility criteria and credit policy.
19. Vizzve Financial: Explore Personal Loan Options
Gig workers and mobile-first borrowers should understand their eligibility, maintain clear income records and compare loan terms before applying.
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Loan availability, eligibility, approval, interest rates, documentation and disbursal are subject to the actual lender's policies and verification. Always check the identity of the lending bank or NBFC and read the loan agreement before proceeding.
20. Key Takeaways
-
Gig workers may qualify for personal loans in India, depending on lender requirements.
-
A traditional salary slip is not universally required; some lenders accept alternative income documents.
-
Bank statements, platform earning reports and invoices may help demonstrate income.
-
Credit history, existing EMIs and repayment capacity remain important.
-
Digital applications may make the process more convenient, but do not guarantee approval.
-
RBI digital lending requirements provide important borrower protections for covered regulated entities.
-
Social security registration and personal loan eligibility are separate matters.
-
The 2027 outlook may include more digital income assessment, but adoption will vary by lender.
-
Borrowers should compare APR, processing charges, EMI and total repayment before accepting a loan.
21. Frequently Asked Questions (FAQs)
1. Can gig workers get personal loans in India in 2027?
Yes. Some banks and NBFCs may offer personal loans to gig workers who meet their eligibility requirements and provide acceptable income proof. Approval depends on lender policy.
2. Can I apply for a personal loan without a salary slip?
Yes, some lenders accept bank statements, platform earning records, invoices or other income documents instead of salary slips. Requirements vary.
3. What is the minimum income required for gig worker loans?
There is no universal minimum income requirement for every gig worker loan. Each lender sets its own income and repayment-capacity conditions.
4. Can delivery partners get personal loans?
Delivery partners may apply for personal loans if a lender accepts their income records and they meet its credit and repayment criteria.
5. Can freelancers apply for personal loans in India?
Yes. Some lenders consider freelancers using bank statements, invoices, contracts and other accepted financial documents.
6. What documents are required for gig worker loans?
Commonly requested documents may include PAN, accepted identity and address proof, bank statements, platform earning reports, invoices and income tax returns, depending on the lender.
7. Does a low credit score affect gig worker loan eligibility?
Yes. A low credit score or negative repayment history may affect eligibility. Some lenders may consider additional factors, but approval is not guaranteed.
8. Can gig workers apply for loans through mobile apps?
Yes. Many lenders offer digital applications through websites or mobile applications. Borrowers should verify the actual lending bank or NBFC before sharing information.
9. Will AI improve gig worker loan eligibility in 2027?
AI may help lenders analyse income records and assess credit risk. However, it does not guarantee loan approval or automatically increase eligibility.
10. Can UPI transactions be used as income proof?
UPI records may help explain certain transactions, but acceptance as formal income proof depends on the lender. Applicants should ask whether bank statements or platform earning records are also required.
11. Does social security registration guarantee a personal loan?
No. Social security registration and personal loan approval are separate matters. Loan eligibility depends on the lender's credit assessment and repayment requirements.
12. How much loan can a gig worker receive?
The amount depends on verified income, existing EMIs, credit history, repayment capacity and the lender's product limits. There is no single fixed loan amount for all gig workers.
13. Can a first-time borrower with no credit history apply?
Yes, some lenders may consider first-time borrowers. They may request additional income information or apply different eligibility conditions.
14. Are digital loan apps safe for mobile-first borrowers?
Not all loan apps are safe. Check the actual lender's identity, official website, privacy policy, loan disclosures and grievance redressal details before applying.
15. What should gig workers check before accepting a personal loan?
Check the lending bank or NBFC, interest rate, APR, processing fees, EMI, tenure, total repayment amount, late payment charges and applicable loan terms.
Conclusion
The 2027 outlook for gig worker loan eligibility in India may be shaped by digital income verification, mobile-first applications, more frequent credit information reporting and evolving lending technology.
These developments may help some delivery partners, freelancers, cab drivers and other independent workers demonstrate their financial position more effectively.
However, access to a personal loan will continue to depend on verified earnings, repayment capacity, credit history and lender-specific eligibility conditions.
Gig workers should maintain organised financial records, check their credit reports and compare loan costs before applying. A convenient mobile application is useful, but responsible borrowing and choosing a legitimate lender are always more important.
Explore personal loan options with Vizzve Financial at www.vizzve.com.
Published on : 15th November
Published by : Reddy kumar
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed