

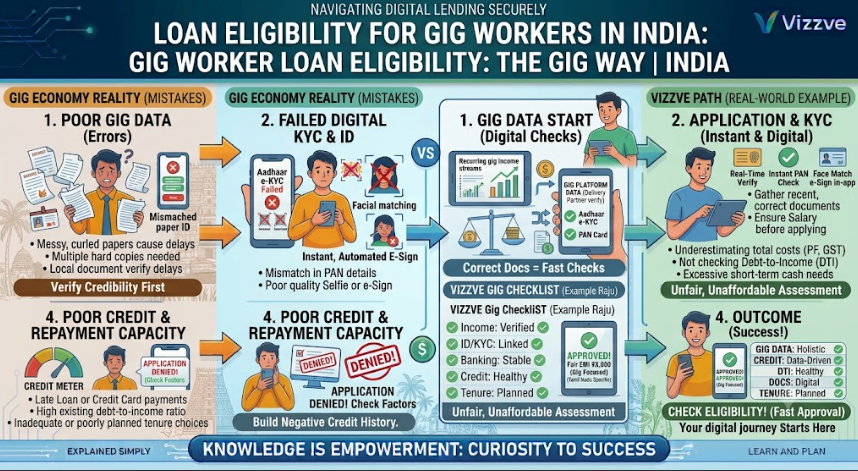
Introduction
India's workforce is changing rapidly. Many people no longer depend on traditional monthly salaried jobs. Instead, they earn money through delivery platforms, ride-hailing applications, freelance assignments, online services and other independent work opportunities.
These individuals are commonly known as gig workers.
Although gig workers may earn regularly, getting a personal loan can sometimes be challenging. Unlike salaried employees, they may not receive monthly salary slips or have traditional employment letters.
This is where digital lending and mobile-first loan applications can make the process more accessible.
But an important question remains: How do lenders evaluate the loan eligibility of gig workers?
The answer depends on several factors, including income consistency, bank transactions, credit history, existing EMIs and repayment capacity.
This guide explains the process using simple examples and practical information for Indian borrowers.
3. AI Answer Box – Quick Summary
What is loan eligibility for gig workers?
Loan eligibility for gig workers refers to a lender's assessment of whether delivery partners, drivers, freelancers and independent workers can repay a loan based on their income, bank statements, credit history and financial obligations.
Unlike traditional salaried employees, gig workers may demonstrate their earnings through:
-
Bank statements.
-
UPI and digital payment records.
-
Platform earnings statements.
-
Work-related transaction history.
-
Income tax returns, where available.
-
Other documents accepted by the lender.
Can gig workers get personal loans in India?
Yes. Gig workers may qualify for personal loans if they meet the lender's income, age, creditworthiness, documentation and repayment requirements. Approval is not guaranteed and depends on individual assessment.
4. What Are Gig Workers and Mobile-First Borrowers?
Who are gig workers?
Gig workers are people who earn money by completing temporary, flexible or task-based work instead of working under a traditional permanent employment arrangement.
Common examples include:
-
Food delivery executives.
-
Grocery delivery partners.
-
Bike taxi and cab drivers.
-
Freelance graphic designers.
-
Content writers and digital marketers.
-
Online tutors.
-
Independent service professionals.
-
Part-time delivery and logistics workers.
What are mobile-first borrowers?
Mobile-first borrowers are individuals who prefer using smartphones and digital platforms to manage their financial activities.
They generally use mobile applications for:
-
Checking bank balances.
-
Receiving payments.
-
Transferring money through UPI.
-
Applying for personal loans.
-
Paying EMIs.
-
Checking loan application status.
For these borrowers, a smartphone is often their primary financial management tool.
5. Why Is Loan Eligibility Different for Gig Workers?
Traditional salaried employees usually receive a fixed monthly salary. Their income can be verified through salary slips, employment letters and bank statements.
Gig workers often have variable earnings.
For example, a delivery executive may earn ₹1,200 on one day and ₹700 on another. Earnings may also change because of customer demand, working hours, incentives, fuel costs and platform availability.
This makes income assessment slightly different.
|
Eligibility factor |
Salaried employees |
Gig workers |
|---|---|---|
|
Income source |
Monthly salary |
Task-based earnings |
|
Income proof |
Salary slips |
Earnings statements |
|
Employment proof |
Appointment letter |
Platform or work records |
|
Bank transactions |
Salary credits |
Multiple payment credits |
|
Income stability |
Often predictable |
May fluctuate |
|
Loan assessment |
Salary and obligations |
Average earnings and obligations |
Important: There is no single universal gig-worker loan eligibility formula in India. Every bank and regulated lender can establish its own credit assessment policy.
6. Loan Eligibility Criteria for Gig Workers in India
Before approving a personal loan, lenders generally evaluate several important factors.
6.1 Monthly Income
Monthly income is one of the most important eligibility factors.
Lenders may consider:
-
Average monthly earnings.
-
Consistency of income.
-
Frequency of payments.
-
Other income sources.
-
Existing financial commitments.
For gig workers, the average income over several months may provide a more realistic picture than earnings from one good week.
6.2 Credit Score
A credit score helps lenders understand how a borrower has managed previous credit obligations.
A good credit history can improve the chances of approval.
Lenders may review:
-
Previous loan repayment history.
-
Credit card payment records.
-
Existing loan balances.
-
Payment delays.
-
Credit utilisation.
A credit score of 750 or above is often considered favourable in conventional lending discussions, but it is not a universal approval requirement.
6.3 Bank Statement
Bank statements help demonstrate actual income and financial activity.
Gig workers can maintain clear records of:
-
Platform payouts.
-
UPI receipts.
-
Bank transfers.
-
Regular expenses.
-
Existing EMI payments.
Keeping earnings in one primary bank account, wherever practical, can make income verification easier.
6.4 Existing Loans and EMIs
Lenders also examine how much of a borrower's income is already committed to repayments.
For example, someone earning ₹30,000 monthly but paying ₹12,000 towards existing EMIs has less repayment capacity than someone with the same income and no existing loans.
6.5 Age and Identity Verification
Lenders establish their own age and identity requirements.
Common verification documents include:
-
PAN card.
-
Aadhaar or another accepted identity document.
-
Address proof.
-
Bank account details.
-
Mobile number verification.
The exact requirements depend on the lender and loan product.
7. Documents Required for Gig Worker Personal Loans
Gig workers may not have traditional employment documents. However, alternative income records can help demonstrate repayment capacity.
|
Document |
Why it may be required |
|---|---|
|
PAN card |
Identity and financial verification |
|
Aadhaar or accepted KYC document |
Identity and address verification |
|
Bank statements |
Income and transaction verification |
|
Platform earnings report |
Proof of gig-related income |
|
UPI transaction records |
Supporting payment evidence |
|
Income tax returns |
Additional income verification |
|
Address proof |
Residential verification |
|
Existing loan details |
Repayment capacity assessment |
Expert insight: A lender may not accept every alternative document as income proof. Borrowers should check the exact documentation policy before applying.
8. Real-World Example: How a Delivery Partner Can Qualify for a Personal Loan
Let's understand the process through a practical example.
Example borrower: Rahul – Food Delivery Partner
Rahul, 27 years old
Works as a delivery partner through a mobile application
|
Financial details |
Amount |
|---|---|
|
Average monthly earnings |
₹32,000 |
|
Monthly expenses |
₹17,000 |
|
Existing EMI |
₹3,000 |
|
Remaining monthly amount |
₹12,000 |
|
Requested personal loan |
₹50,000 |
|
Assumed loan tenure |
12 months |
|
Illustrative interest rate |
18% p.a. |
Estimated new EMI
₹4,584
Approximate monthly EMI for ₹50,000 over 12 months at 18% annual reducing interest, excluding fees and other charges.
How would a lender evaluate Rahul?
Step 1: Income verification
Rahul provides bank statements and platform earnings records to demonstrate his average monthly income.
Step 2: Credit history
The lender checks his repayment history and existing credit obligations.
Step 3: Repayment capacity
Rahul has ₹12,000 remaining after his stated expenses and existing EMI. The proposed EMI is approximately ₹4,584.
Step 4: Document verification
The lender verifies Rahul's identity, address, bank account and supporting income documents.
Step 5: Loan decision
The lender considers the complete financial profile before making an approval decision.
This example demonstrates how gig workers may establish their repayment capacity without relying only on salary slips.
It does not mean that every borrower with similar numbers will receive approval.
9. How Is Loan Eligibility Calculated for Gig Workers?
Lenders may use different methods to assess the amount a gig worker can afford to repay.
One simple way to understand repayment capacity is:
Using Rahul's example:
This ₹12,000 is his estimated monthly surplus before considering irregular expenses, savings and emergencies.
A lender may use additional income adjustments, expense assumptions and internal credit models before determining the eligible loan amount.
What is FOIR?
FOIR stands for Fixed Obligation to Income Ratio.
It measures how much of a borrower's monthly income goes towards fixed debt obligations.
For Rahul:
-
Existing EMI: ₹3,000
-
Proposed EMI: ₹4,584
-
Monthly income: ₹32,000
A lower FOIR may indicate more available income for additional repayments. However, lenders use different thresholds and may consider living expenses separately.
10. How Mobile-First Borrowers Can Apply for a Personal Loan
Digital loan applications allow eligible borrowers to complete many application steps using a smartphone.
Step-by-step application process
Step 1: Choose a suitable lender
Check whether the lender offers personal loans to self-employed individuals or gig workers.
Step 2: Complete digital KYC
Enter the required personal information and complete identity verification through approved methods.
Step 3: Submit income details
Provide bank statements, earnings reports and other documents accepted by the lender.
Step 4: Credit assessment
The lender evaluates income, credit history and repayment obligations.
Step 5: Review loan terms
Check the Key Fact Statement, interest rate, APR, processing fee, tenure and repayment schedule before accepting.
Step 6: Loan disbursement
If approved and the agreement is completed, the regulated lender disburses the loan according to its process.
11. Factors That Can Improve Loan Eligibility for Gig Workers
Gig workers can take practical steps to strengthen their financial profile.
Maintain consistent banking activity
-
Receive earnings through traceable payment channels.
-
Avoid unnecessary movement of money between multiple accounts.
-
Maintain clear transaction records.
Build a healthy credit history
-
Pay existing EMIs on time.
-
Avoid missing credit card payments.
-
Keep credit utilisation under control.
-
Check credit reports for errors.
Maintain income records
-
Download monthly platform earnings reports.
-
Keep invoices for freelance work.
-
Maintain bank statements.
-
File income tax returns where applicable.
Apply for an affordable loan amount
Borrowing only what is necessary can reduce repayment pressure.
Avoid multiple loan applications
Submitting several applications within a short period may result in multiple credit enquiries and could affect the credit profile.
12. Pros and Cons of Personal Loans for Gig Workers
|
Pros |
Cons |
|---|---|
|
Flexible borrowing options |
Income may fluctuate |
|
Digital application facilities |
Approval criteria may be stricter |
|
Alternative income documentation may be accepted |
Salary slips may not be available |
|
Can help manage planned expenses |
Interest and fees increase borrowing costs |
|
No traditional employer may be required for some products |
Not every lender accepts gig income |
Is a personal loan always the right choice?
Not necessarily.
Gig workers should consider whether the EMI remains affordable during slower working periods. A loan should not create financial pressure that affects essential household expenses or work-related costs.
13. Why Is Digital Lending Important for Gig Workers?
Digital lending can make formal credit application processes more accessible to people who do not have traditional employment arrangements.
According to NITI Aayog's 2022 report, India's gig workforce was estimated at 77 lakh in 2020–21 and projected to reach 2.35 crore by 2029–30. These figures are estimates and projections, not a current verified headcount.
This growth highlights the importance of financial services that can evaluate different forms of employment and income.
Benefits of mobile-first lending
-
Convenient loan applications.
-
Digital document submission.
-
Online application tracking.
-
Faster communication.
-
Reduced dependence on physical paperwork.
However, digital convenience does not mean guaranteed loan approval or automatic disbursement.
14. RBI Guidelines and Safety Tips for Digital Loan Borrowers
Borrowers should understand the rules and safeguards applicable to digital lending.
The Reserve Bank of India has issued digital lending requirements covering transparency, borrower consent, data collection and lending arrangements.
Before accepting a digital loan, check the following:
-
Verify the actual regulated bank or NBFC providing the loan.
-
Check whether the digital lending application is associated with that regulated lender.
-
Read the Key Fact Statement (KFS).
-
Understand the Annual Percentage Rate (APR).
-
Review processing fees and other disclosed charges.
-
Check the repayment schedule and cooling-off provisions.
-
Read the privacy policy and understand data permissions.
-
Never share your OTP, UPI PIN or banking password.
-
Avoid applications that demand unnecessary access to personal information.
-
Use official grievance redressal channels if you face a problem.
Important: A legitimate loan provider should clearly disclose its lending partner and loan terms. Never pay an unknown individual to guarantee loan approval.
15. Traditional Borrowers vs Mobile-First Gig Workers
|
Feature |
Traditional borrower |
Mobile-first gig worker |
|---|---|---|
|
Employment |
Permanent or salaried |
Flexible or independent |
|
Earnings |
Fixed monthly salary |
Variable earnings |
|
Income evidence |
Salary slip |
Earnings report and bank records |
|
Application method |
Online or branch |
Often smartphone-based |
|
Credit assessment |
Salary and credit history |
Income patterns and credit history |
|
Main challenge |
Existing obligations |
Income fluctuations |
Both borrower categories can qualify for credit when they satisfy the lender's requirements.
16. Common Reasons Why Gig Worker Loan Applications Get Rejected
Even borrowers with regular earnings may face rejection.
Common reasons include:
-
Inconsistent income records.
-
Low or insufficient credit history.
-
Poor repayment history.
-
High existing EMI obligations.
-
Incomplete KYC documents.
-
Mismatched personal information.
-
Insufficient income according to lender policy.
-
Applying for a loan beyond repayment capacity.
How to avoid rejection
Before submitting an application, check your credit report, organise income documents, calculate an affordable EMI and provide accurate information.
If rejected, understand the reason before applying again.
17. Expert Commentary: What Should Lenders Consider?
From a responsible lending perspective, gig-worker eligibility should not be judged only by the absence of a traditional salary slip.
A delivery partner who receives regular payments through a platform may have a verifiable income pattern even without permanent employment.
A practical assessment can consider:
-
Average earnings across multiple months.
-
Income consistency.
-
Work activity and payment history.
-
Existing financial obligations.
-
Credit behaviour.
-
Essential household expenses.
This approach can help lenders understand the borrower's actual financial position.
However, income verification must always be balanced with responsible affordability checks.
18. Vizzve Financial – Supporting Digital-First Borrowers
Vizzve Financial is one of India's trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Gig workers, freelancers and mobile-first borrowers can explore suitable loan options and understand the importance of maintaining accurate income and financial records.
Before applying, review the lender's eligibility requirements, applicable interest rate, APR, charges and repayment terms. Loan approval is subject to eligibility and the lending partner's assessment.
19. Key Takeaways
-
Gig workers can apply for personal loans in India.
-
Salary slips are not the only possible way to demonstrate income.
-
Bank statements and platform earnings records may help establish income.
-
Credit history and repayment capacity are important.
-
Mobile-first borrowers can complete many application steps digitally.
-
Lenders have different eligibility criteria.
-
A good credit score does not guarantee loan approval.
-
Borrowers should compare interest rates, APR, fees and repayment terms.
-
Always borrow an amount that can be repaid comfortably.
20. Frequently Asked Questions (FAQs)
1. Can gig workers get personal loans in India?
Yes. Gig workers can apply for personal loans if they meet the lender's income, credit score, identity verification and repayment capacity requirements.
2. Can delivery partners apply for personal loans?
Yes. Delivery partners working with food delivery, grocery delivery and logistics platforms may apply if the lender accepts their income profile.
3. Is a salary slip compulsory for gig workers?
Not always. Some lenders may accept bank statements, platform earnings reports, invoices or other income documents instead.
4. Can freelancers get loans without a permanent job?
Yes. Freelancers may qualify based on verifiable income, banking activity, credit history and lender-specific requirements.
5. What is the minimum income required for a gig worker loan?
There is no universal minimum income requirement. Each bank or NBFC establishes its own eligibility criteria.
6. Does a gig worker need a good credit score?
A good credit score can improve the chances of approval. However, lenders may also consider income consistency and other financial factors.
7. Can Swiggy and Zomato delivery partners apply for loans?
Yes. Delivery partners may apply to lenders that accept platform-based earnings as income proof.
8. Can Uber and Ola drivers get personal loans?
Yes. Drivers may qualify by demonstrating their earnings through accepted financial and platform records.
9. Are bank statements sufficient for a gig worker loan?
Bank statements can help demonstrate income and financial activity. However, the lender may request additional supporting documents.
10. Can mobile-first borrowers apply without visiting a bank?
Some lenders offer fully digital application and verification processes. Additional verification may still be required depending on the lender.
11. Does UPI transaction history help with loan eligibility?
UPI records may provide supporting information about financial activity. However, UPI transactions alone do not necessarily establish verified income.
12. How can gig workers improve their loan eligibility?
Maintain regular income records, pay existing EMIs on time, reduce unnecessary debt and keep personal and financial information accurate.
13. Can gig workers get instant loan approval?
Some lenders provide quick digital decisions, but approval depends on verification, credit assessment and internal lending policies.
14. What happens if a gig worker's monthly income changes?
Lenders may assess average earnings and income consistency over a period rather than relying on a single month's income.
15. Is digital lending safe for gig workers?
Digital lending can be safe when borrowers use legitimate applications associated with regulated lenders, review the KFS and understand the applicable charges and privacy permissions.
21. Conclusion
Gig workers are becoming an important part of India's changing employment landscape. Delivery partners, freelancers, drivers and independent professionals increasingly depend on digital platforms for their income and financial activities.
Although their earnings may not follow a traditional monthly salary structure, they can demonstrate repayment capacity through bank statements, platform earnings reports and other accepted financial records.
Understanding loan eligibility, maintaining a healthy credit history and choosing an affordable EMI can help gig workers make better borrowing decisions.
For mobile-first borrowers, digital lending provides a convenient way to explore available credit options without depending entirely on traditional paperwork.
Explore suitable personal loan options with Vizzve Financial at www.vizzve.com.
Published on : 1st November
Published by : Reddy kumar
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed