

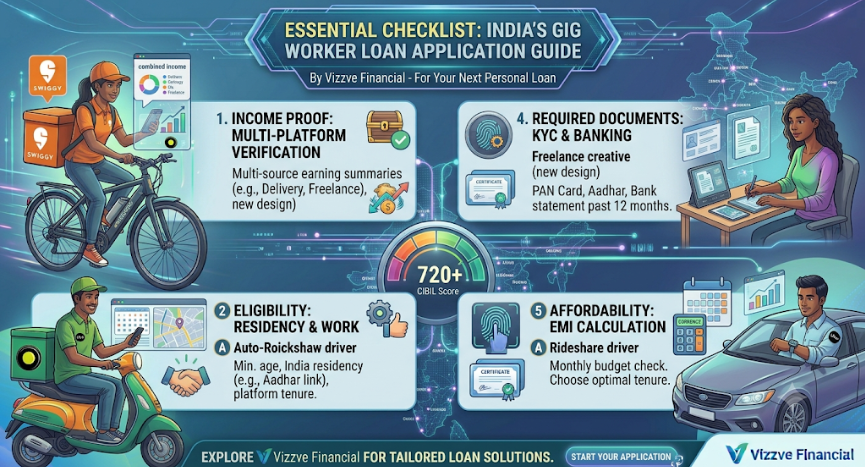
Introduction
The gig economy is creating new employment and earning opportunities across India. Today, many people work as food delivery partners, ride-hailing drivers, freelancers, online tutors, digital marketers and independent service providers.
Unlike traditional salaried employees, gig workers may not receive a fixed monthly salary. Their earnings can change depending on completed orders, working hours, customer demand and freelance projects.
This difference can create questions when applying for personal loans.
Can a delivery partner get a personal loan? Is a salary slip compulsory? How do lenders calculate income when earnings change every month? What should applicants check before accepting an online loan offer?
The good news is that some banks and regulated NBFCs consider alternative income documents, including bank statements, platform earnings reports, freelance invoices and other financial records.
However, submitting an application without checking the important conditions can lead to unnecessary credit enquiries, unsuitable loan offers or repayment difficulties.
This guide explains everything gig workers should check before applying for an online personal loan, including eligibility, income proof, credit score, documentation, interest rates, EMI affordability and lender verification.
The goal is simple: help gig workers make informed borrowing decisions before submitting a loan application.
3. AI Answer Box: What Should Gig Workers Check Before Applying?
Before applying for an online personal loan, gig workers should check their income stability, credit history, existing EMIs, required documents and repayment capacity.
Here are the most important things to review:
-
Income: Calculate average monthly earnings using recent income records.
-
Credit Score: Review your credit report and repayment history.
-
Documents: Prepare bank statements, platform earnings reports and other accepted income proofs.
-
Existing Loans: Calculate current EMIs and outstanding debts.
-
Interest Rate: Compare the Annual Percentage Rate (APR), not just the advertised interest rate.
-
Repayment: Make sure the EMI is affordable even during low-income months.
-
Lender Verification: Confirm that the loan is provided by a legitimate regulated bank or NBFC.
-
Loan Agreement: Read all terms, charges and repayment conditions before accepting.
Quick Answer: Gig workers should check eligibility, income verification, credit history, loan costs and EMI affordability before applying. A well-prepared application can make the process clearer, but approval depends on the lender's assessment.
4. Understand Your Loan Eligibility Before Applying
Loan eligibility refers to the financial and personal requirements an applicant must satisfy to receive a loan.
For gig workers, lenders may assess income differently because their earnings are not always fixed.
Who Can Apply for Gig Worker Loans?
The following categories may explore personal loan options with lenders that accept their income profiles.
| Gig Worker Category | Income Source |
|---|---|
| Food delivery partners | Food and grocery deliveries |
| Ride-hailing drivers | Taxi and bike taxi trips |
| Freelancers | Independent client projects |
| Online tutors | Online teaching sessions |
| Digital marketers | SEO and social media services |
| Logistics workers | Parcel and goods delivery |
| Home service professionals | Repairs and maintenance |
| Independent consultants | Professional assignments |
What Do Lenders Generally Evaluate?
-
Age and identity verification.
-
Average monthly income.
-
Platform or freelance work history.
-
Credit score and repayment behaviour.
-
Existing financial obligations.
-
Bank account activity.
-
Ability to repay the proposed EMI.
Eligibility conditions vary between banks, NBFCs and loan products.
5. 12 Important Things to Check Before Applying for a Gig Worker Loan
This is the most important section for applicants who want to prepare before submitting an online application.
5.1 Check Your Average Monthly Income
The first step is understanding how much money you actually earn.
Gig workers may have different earnings every month, so calculating income based on only one month can give an incorrect picture.
For example:
| Month | Monthly Earnings |
|---|---|
| January | ₹24,000 |
| February | ₹21,000 |
| March | ₹26,000 |
| April | ₹23,000 |
| May | ₹25,000 |
| June | ₹21,000 |
| Total | ₹1,40,000 |
| Monthly Average | ₹23,333 |
This average gives an initial picture of the applicant's earning pattern.
However, actual income available for repayment should also account for fuel, maintenance, business expenses and household expenses.
What to check:
-
Review earnings over recent months.
-
Identify periods of lower income.
-
Keep platform payment statements.
-
Maintain bank transaction records.
-
Avoid reporting inflated income.
5.2 Check Your Credit Score
Your credit score is an important part of your loan application.
It helps lenders understand your previous borrowing and repayment behaviour.
Before applying, check:
-
Whether previous EMIs were paid on time.
-
Whether credit card payments are outstanding.
-
Whether your credit report contains incorrect entries.
-
Whether you have too many recent credit enquiries.
-
Whether any old loan remains incorrectly marked as outstanding.
A stronger credit history may support your application, but it does not guarantee approval.
5.3 Check Whether You Have Acceptable Income Proof
Many gig workers do not receive traditional salary slips.
However, some lenders may accept alternative financial documents.
Common Income Proofs
| Document | How It Helps |
|---|---|
| Bank statements | Shows actual income credits |
| Platform earnings reports | Demonstrates gig work payments |
| Freelance invoices | Shows client billing |
| Client payment records | Supports income verification |
| Income tax returns | Provides additional income information |
| Business income statements | Helps demonstrate professional earnings |
Not every lender accepts all these documents. Confirm the requirements before applying.
5.4 Check Your Existing Loan Obligations
If you already have a personal loan, vehicle loan or credit card balance, calculate your total monthly obligations.
For example:
| Existing Financial Commitment | Monthly Amount |
|---|---|
| Vehicle EMI | ₹3,000 |
| Personal loan EMI | ₹2,000 |
| Credit card repayment | ₹1,000 |
| Total | ₹6,000 |
These obligations reduce the amount available for a new EMI.
Do not apply for another loan without understanding your current debt position.
5.5 Check the Interest Rate and APR
The advertised interest rate does not always represent the full cost of borrowing.
The Annual Percentage Rate includes the interest rate and applicable charges reflected in the APR calculation.
Before accepting a loan offer, compare:
-
Annual interest rate.
-
APR.
-
Processing fee.
-
Applicable taxes.
-
Other compulsory charges.
-
Total repayment amount.
A loan with a slightly lower advertised interest rate may not necessarily be cheaper after considering fees.
5.6 Check Whether the EMI Is Affordable
A fixed EMI can become difficult when gig income decreases.
For example, a delivery partner earning ₹25,000 in a busy month may earn only ₹18,000 during a slower period.
Therefore, calculate affordability using conservative income estimates.
Example of Monthly Affordability
| Financial Detail | Amount |
|---|---|
| Average monthly earnings | ₹25,000 |
| Fuel and work expenses | ₹3,000 |
| Household expenses | ₹12,000 |
| Existing EMI | ₹2,000 |
| Remaining amount | ₹8,000 |
The remaining ₹8,000 is not automatically available for a new EMI. Emergency savings and unexpected expenses must also be considered.
5.7 Check the Loan Tenure
Loan tenure refers to the period within which the borrowed amount must be repaid.
A longer tenure may reduce the monthly EMI but can increase total interest costs.
A shorter tenure may reduce the overall interest paid but create a higher monthly repayment burden.
Choose a tenure that matches your actual income pattern.
5.8 Check Processing Fees and Other Charges
Some applicants focus only on the EMI and forget to check additional costs.
Review the following:
-
Processing fees.
-
Applicable taxes.
-
Late payment charges.
-
Bounce charges, if applicable.
-
Prepayment charges, where permitted.
-
Foreclosure conditions.
-
Optional insurance costs.
All applicable charges should be disclosed in the relevant loan documents.
5.9 Check the Lender's Credibility
One of the most important steps is verifying who is actually providing the loan.
Before submitting personal documents:
-
Identify the bank or NBFC responsible for the loan.
-
Check the lender's official website.
-
Verify the lending app's association with the regulated entity.
-
Read the privacy policy.
-
Check customer support and grievance details.
-
Avoid applications promising guaranteed approval without proper assessment.
Do not assume an app is safe simply because it appears in an advertisement or app store.
5.10 Check the Repayment Date
Gig workers may receive earnings daily, weekly or at irregular intervals.
A suitable repayment date can help reduce missed payments.
Before applying, understand:
-
The scheduled EMI date.
-
The payment method.
-
The repayment account.
-
Available repayment-date options.
-
What happens if payment is delayed.
Maintain enough money in the repayment account before the due date.
5.11 Check the Loan Agreement
Never accept a loan without reading the agreement.
Review the following details carefully:
-
Sanctioned loan amount.
-
Net disbursed amount.
-
Interest rate and APR.
-
Repayment tenure.
-
EMI amount.
-
Total repayment obligation.
-
Fees and penalties.
-
Prepayment conditions.
-
Grievance redressal information.
If anything is unclear, request clarification through the lender's official support channel.
5.12 Check Whether You Really Need the Loan
Before applying, ask yourself:
-
Is this an essential financial requirement?
-
Can I manage the expense through savings?
-
Will the EMI affect household expenses?
-
Can I repay during a low-income month?
-
Am I borrowing to repay another loan?
A loan should solve a genuine financial requirement, not create another financial problem.
6. Documents to Prepare Before Submitting an Online Application
Preparing documents in advance can help avoid unnecessary delays.
Common Documents
| Document | Purpose |
|---|---|
| PAN card | Identity and financial verification |
| Aadhaar card | Identity or address verification, where accepted |
| Recent bank statements | Income verification |
| Platform earnings statements | Proof of gig income |
| Freelance invoices | Client payment evidence |
| Address proof | Address verification |
| Photograph | Application verification, if requested |
Document Preparation Tips
-
Ensure your personal details are accurate.
-
Submit readable copies.
-
Keep recent bank statements ready.
-
Maintain genuine income records.
-
Avoid altered or false documents.
-
Follow the lender's official checklist.
7. How Does Loan Eligibility Differ Between Salaried Employees and Gig Workers?
The documentation and income assessment process may differ between these applicant categories.
| Comparison | Salaried Employee | Gig Worker |
|---|---|---|
| Income pattern | Usually fixed | May fluctuate |
| Salary slip | Commonly available | May not be available |
| Income verification | Salary slips and bank statements | Platform and bank records |
| Employment proof | Employer details | Platform or client records |
| Income stability | Often predictable | Depends on work availability |
| Loan assessment | Lender-specific | Lender-specific |
Neither category is automatically guaranteed loan approval.
The lender evaluates the applicant's complete financial position.
8. EMI Calculation: Understand Your Repayment Before Applying
An EMI is the fixed instalment paid towards a loan according to the agreed repayment schedule.
It generally includes principal and interest.
Example: ₹50,000 Personal Loan
| Loan Detail | Illustrative Amount |
|---|---|
| Loan amount | ₹50,000 |
| Annual interest rate | 15% |
| Loan tenure | 12 months |
| Approximate monthly EMI | ₹4,513 |
| Approximate total repayment | ₹54,156 |
| Approximate total interest | ₹4,156 |
This is an illustrative calculation using a reducing-balance EMI method. Actual costs depend on the lender's offer, APR, fees and other applicable charges.
Why Should Gig Workers Calculate EMI Before Applying?
Because monthly income can change, an EMI that is manageable during a busy period may become difficult during a slow period.
Before accepting the loan, check whether you can repay it while still covering:
-
Household expenses.
-
Fuel and transport costs.
-
Work-related expenses.
-
Existing EMIs.
-
Emergency savings.
9. Pros and Cons of Online Personal Loans for Gig Workers
Understanding both advantages and disadvantages helps applicants make better decisions.
Advantages
-
Convenient online application.
-
Digital document submission.
-
Alternative income verification with some lenders.
-
No traditional salary slip requirement with every lender.
-
Access to personal credit for eligible applicants.
-
Easier access to loan information and repayment schedules.
Disadvantages
-
Loan approval is not guaranteed.
-
Irregular income may affect eligibility.
-
Interest rates differ between lenders.
-
Processing fees can increase borrowing costs.
-
Existing debt can reduce repayment capacity.
-
Fake loan applications may create financial and privacy risks.
Quick Comparison
| Benefits | Limitations |
|---|---|
| Digital application | Verification is still required |
| Alternative income proof | Not accepted by every lender |
| Convenient document submission | Additional documents may be requested |
| Access to emergency funds | Interest and fees apply |
| Potential credit history building | Late payments can damage credit |
10. Step-by-Step Guide: How to Apply for a Gig Worker Loan
Once you have checked your financial position, follow these steps.
Step 1: Identify Your Financial Requirement
Decide how much money you actually need.
Step 2: Review Your Eligibility
Check the lender's age, income and credit requirements.
Step 3: Prepare Your Income Documents
Collect recent bank statements, platform payment reports and other accepted records.
Step 4: Review Your Credit Report
Check your existing borrowing history and correct any errors.
Step 5: Compare Loan Offers
Compare APR, processing fees, tenure and total repayment costs.
Step 6: Complete the Online Application
Enter correct personal and financial information.
Step 7: Complete Verification
Provide the required documents and respond to legitimate lender verification requests.
Step 8: Read the Loan Agreement
Understand the complete repayment obligation before accepting.
Step 9: Plan Your EMI
Set aside the required repayment amount and keep sufficient funds available on the due date.
11. Important RBI Guidelines Before Applying for Online Loans
The Reserve Bank of India issued the Reserve Bank of India (Digital Lending) Directions, 2025, on May 8, 2025.
These directions establish important requirements for regulated entities and covered digital lending arrangements.
Important Borrower Protections
1. Key Fact Statement (KFS)
Borrowers should receive important loan information, including APR and applicable charges.
2. Creditworthiness Assessment
Regulated lenders must assess the borrower's creditworthiness before extending digital loans.
3. Cooling-Off Period
Eligible digital loans must provide the prescribed cooling-off option, subject to applicable conditions and disclosures.
4. Data Privacy
Digital lending arrangements must follow applicable requirements relating to borrower consent and data handling.
5. Grievance Redressal
Borrowers should have access to the relevant regulated lender's grievance redressal mechanism.
6. Loan Fund Flows
Digital loan disbursal and repayment must follow RBI requirements, generally involving direct transfers between the borrower and regulated lender, subject to specified exceptions.
How to Protect Yourself From Fake Loan Apps
-
Verify the actual bank or NBFC.
-
Use official application channels.
-
Review the loan agreement.
-
Read the privacy policy.
-
Never share OTPs or banking passwords.
-
Avoid upfront payments to unknown individuals.
-
Check official lender and RBI information.
12. Expert Commentary: Why Checking Before Applying Matters
For gig workers, loan eligibility should not be judged by one month's income alone.
A delivery partner may earn more during busy periods and less during quieter periods. A freelancer may receive several client payments in one month and experience a gap in the following month.
Therefore, responsible borrowing begins with understanding the complete financial picture.
Before applying, an applicant should consider:
-
Average income over several months.
-
Work-related expenses.
-
Existing debt obligations.
-
Household spending.
-
Emergency savings.
-
Total loan cost.
Practical financial insight: A loan is suitable when its repayment remains manageable even during a lower-income month. Choosing an affordable EMI is more important than qualifying for the largest possible amount.
13. Real-World Example: What Should a Delivery Partner Check?
Consider a delivery partner named Rahul who earns money through food delivery services.
He wants to apply for a personal loan of ₹40,000.
Rahul's Financial Details
| Financial Information | Amount |
|---|---|
| Average monthly income | ₹25,000 |
| Fuel expenses | ₹3,000 |
| Household expenses | ₹12,000 |
| Existing EMI | ₹2,000 |
| Remaining amount | ₹8,000 |
Before applying, Rahul should:
-
Check his recent six-month earnings.
-
Prepare bank statements.
-
Download platform payment records.
-
Review his credit report.
-
Compare loan interest rates and APR.
-
Check processing charges.
-
Calculate whether the EMI is affordable.
-
Verify the lender's identity.
This preparation can help Rahul understand his financial position before submitting the application.
The example is illustrative and does not represent an actual customer or guarantee of loan approval.
14. How Vizzve Financial Supports Online Loan Applicants
Finding suitable financial support can be challenging for gig workers who have irregular income or limited traditional employment documents.
Vizzve Financial aims to help applicants explore personal loan options and understand the online application process.
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before proceeding, applicants should review the applicable lender's eligibility requirements, APR, interest rate, processing fees and repayment terms.
Loan approval, amount and disbursal depend on the relevant lender's verification and policies.
15. Key Takeaways
-
Check your average monthly income before applying.
-
Review your credit score and repayment history.
-
Prepare acceptable income proof.
-
Calculate existing EMIs and outstanding debt.
-
Compare APR and processing fees.
-
Check EMI affordability during low-income months.
-
Understand loan tenure and repayment dates.
-
Verify the regulated lender.
-
Read the Key Fact Statement and loan agreement.
-
Borrow only what you can comfortably repay.
16. Frequently Asked Questions (FAQs)
1. What should gig workers check before applying for a personal loan?
They should check average income, credit history, existing EMIs, required documents, interest rates, processing fees and repayment capacity.
2. Can gig workers apply for online personal loans in India?
Yes. Gig workers may apply through banks and NBFCs that accept independent or platform-based income, subject to eligibility requirements.
3. Is a salary slip compulsory for gig worker loans?
No, not with every lender. Some lenders accept bank statements, platform earnings reports and other alternative income documents.
4. What documents should delivery partners prepare before applying?
Common documents include PAN, Aadhaar where accepted, bank statements, platform earnings reports and other documents requested by the lender.
5. Does a credit score affect gig worker loan eligibility?
Yes. Credit history and repayment behaviour can influence approval decisions and loan terms.
6. How do lenders verify gig worker income?
They may review bank statements, platform payment records, freelance invoices and other accepted financial documents.
7. Can freelancers apply for personal loans without fixed income?
Yes. Some lenders consider freelancers with variable income after reviewing their financial records and repayment capacity.
8. How much loan can a gig worker get?
The eligible amount depends on income, expenses, credit history, existing debts and the lender's policies.
9. Why should gig workers compare APR before applying?
APR provides a broader view of borrowing costs, including interest and applicable charges. It helps applicants compare loan offers more effectively.
10. Can gig workers apply with an existing EMI?
Yes, depending on their remaining repayment capacity and the lender's eligibility requirements.
11. How can gig workers avoid EMI repayment problems?
They should maintain an EMI fund, schedule reminders, track monthly expenses and keep emergency savings.
12. Are online personal loans safe for gig workers?
They can be safe when obtained through legitimate regulated lenders and compliant digital lending arrangements. Always verify the lender before applying.
13. What happens if a gig worker's loan application is rejected?
The applicant should review the reason, check the credit report, correct errors and reassess their financial position before submitting another application.
14. Can gig workers repay personal loans early?
Early repayment may be possible depending on the agreement and applicable rules. Check prepayment and foreclosure conditions.
15. Where can gig workers explore online personal loan options?
Applicants can visit www.vizzve.com to explore available loan support and application options. Approval and terms depend on the relevant lender's assessment.
17. Conclusion
Applying for a personal loan as a gig worker requires careful preparation. Although some lenders accept alternative income documents instead of traditional salary slips, applicants still need to demonstrate their financial position and repayment capacity.
Before submitting an online application, check your average earnings, credit history, existing obligations, interest rate, APR and total repayment amount.
Understanding these details can help you avoid unsuitable loan offers and unnecessary financial pressure.
A good borrowing decision is not just about receiving approval. It is about choosing a loan that fits your income and can be repaid comfortably.
Looking for personal loan support?
Explore available options with Vizzve Financial.
Visit: https://www.vizzve.com/
Borrow responsibly. Compare carefully. Repay on time.
Published on : 11th November
Published by : Reddy kumar
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed