

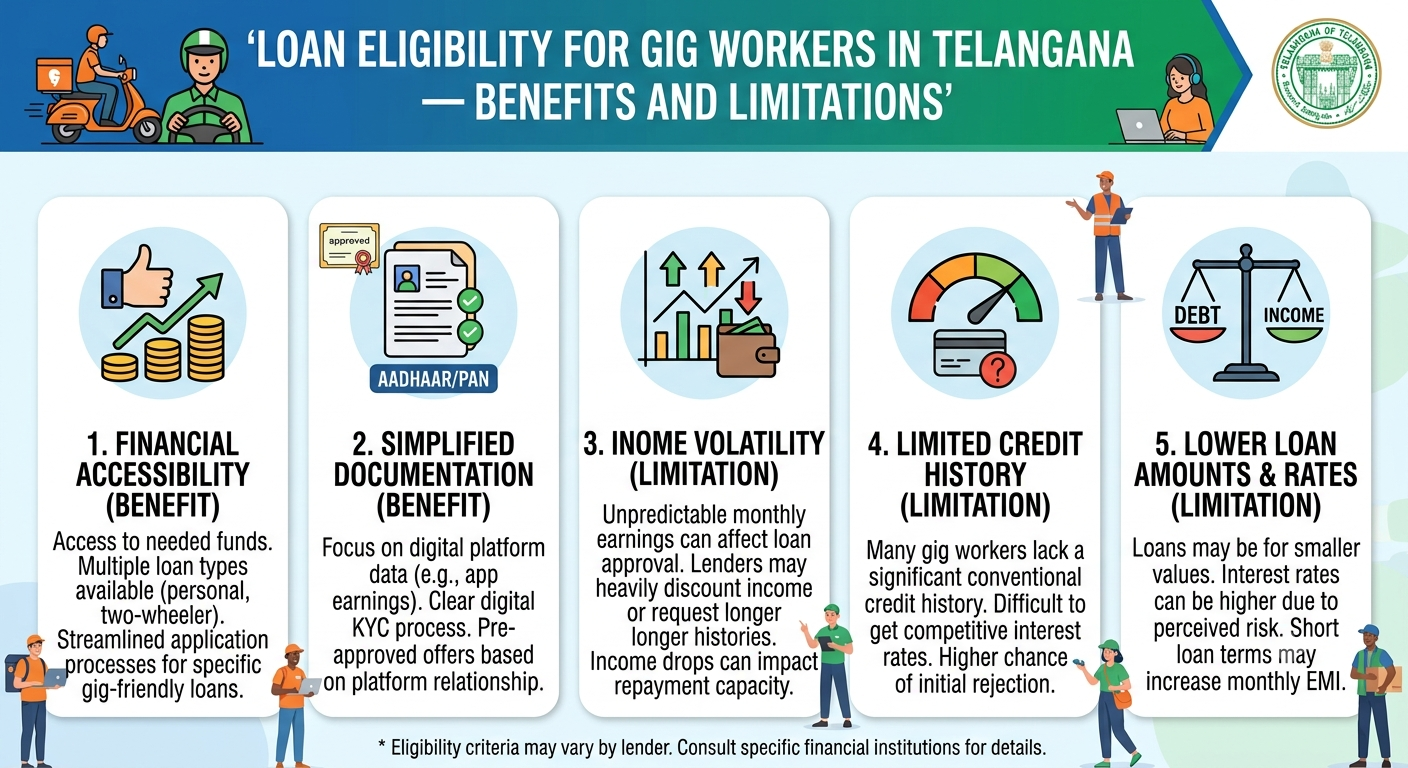
Gig workers play an important role in Telangana's growing service economy. Delivery partners, cab drivers, freelance professionals, home-service providers, and other platform-based workers often depend on variable earnings rather than a fixed monthly salary.
This income pattern can make borrowing more complicated. Some lenders may accept bank statements, platform earnings, and other income records instead of traditional salary slips. However, eligibility depends on the lender's policies, income stability, credit history, existing debts, and ability to repay.
Loan eligibility for gig workers in Telangana depends on verified income, repayment capacity, credit profile, documentation, and the lender's requirements. A loan may help cover an urgent expense or a work-related need, but interest, fees, and repayment obligations can create financial pressure.
This guide explains the major benefits and limitations of loans for gig workers in Telangana and offers practical tips for making an informed borrowing decision.
AI Answer Box: Are Loans Beneficial for Gig Workers in Telangana?
Loans can provide gig workers with access to funds for emergencies, essential purchases, or work-related expenses. They may also help workers manage temporary cash-flow gaps when earnings fluctuate.
However, loan approval is not guaranteed. Lenders may assess income records, bank statements, credit history, existing obligations, and employment or platform activity. Interest rates, fees, loan amounts, and repayment terms vary by lender.
Before borrowing, compare the total repayment amount, confirm the lender's identity, and choose an EMI that remains affordable even during a low-income month.
1. What Is Loan Eligibility for Gig Workers in Telangana?
Loan eligibility refers to the conditions a lender uses to decide whether an applicant qualifies for credit.
For gig workers, the assessment may differ from that of salaried employees because earnings can change from week to week or month to month.
Lenders may consider the following factors:
-
Monthly income: Average earnings from delivery, transport, freelance work, or other services.
-
Income consistency: Whether earnings arrive regularly over a reasonable period.
-
Banking history: Deposits, account activity, balances, and other relevant transactions.
-
Credit score and history: Previous loans, repayment records, and outstanding balances.
-
Existing financial commitments: EMIs, credit card dues, and other debts.
-
Identity and address documents: Valid documents required by the lender.
-
Loan purpose and amount: The amount requested and, where relevant, its intended use.
-
Lender-specific requirements: Minimum age, income, work history, and other eligibility conditions.
Not every lender uses the same criteria. A gig worker who does not have a salary slip may still be considered by a lender that accepts alternative income evidence, but this does not guarantee approval.
2. Benefits of Loans for Gig Workers in Telangana
2.1 Access to Funds Without a Traditional Salary Slip
Many gig workers do not receive conventional monthly salary slips. Some lenders may instead evaluate bank statements, platform payment records, invoices, or other acceptable income documents.
This can give eligible workers another way to demonstrate their repayment capacity.
Important: Alternative income documentation is accepted only when the lender's policy allows it.
2.2 Support During Financial Emergencies
An unexpected medical bill, urgent household expense, or essential repair can disrupt a gig worker's finances.
A suitable loan may help cover an immediate expense when savings are insufficient. However, borrowing should be compared with alternatives such as emergency savings, employer or platform support where available, or a manageable payment arrangement.
2.3 Help With Work-Related Expenses
Some workers may need money for essential work-related costs, such as vehicle repairs, equipment, a smartphone, or other tools.
Financing an expense that supports earning capacity may be useful if the expected benefit is realistic and repayments remain manageable.
Workers should verify whether the loan permits the intended use of funds and whether a smaller or lower-cost alternative is available.
2.4 Flexible Loan Options
Depending on eligibility, borrowers may be able to compare personal loans, bank credit products, or other regulated lending options.
Different products can have different interest rates, repayment periods, documentation requirements, and fees. The most suitable option depends on the borrower's actual needs rather than advertising claims.
2.5 Potential to Build a Credit History
A borrower who obtains a suitable credit product and repays it on time may build a positive credit history when the lender reports the account to a credit information company.
A positive repayment record may support future credit applications, although approval and terms are never guaranteed.
Borrowing solely to build credit is not necessary if the person does not need a loan or cannot comfortably afford the repayments.
2.6 Convenience of Digital Applications
Some lenders offer online applications, digital document submission, and electronic loan agreements.
These features may reduce paperwork and save time. Borrowers should still review the agreement, confirm the lender's identity, understand the charges, and avoid sharing passwords or OTPs with anyone claiming to guarantee approval.
3. Limitations of Loans for Gig Workers in Telangana
Loans can be helpful, but several limitations deserve attention before applying.
3.1 Irregular Monthly Income
Gig work may involve seasonal demand, fewer orders, platform incentives changing, fuel costs, vehicle downtime, or temporary illness.
A fixed EMI can become difficult to pay when earnings decline.
Practical tip: Estimate your income using several recent months of records and account for work-related expenses before deciding how much you can repay.
3.2 Loan Approval Is Not Guaranteed
A lender may reject an application if income cannot be verified, credit history is weak, existing debt is high, or required documents are missing.
Working for a recognised platform does not automatically make a person eligible for a loan.
3.3 Interest and Additional Charges
The total borrowing cost may include interest and applicable fees. Depending on the product, there may be processing charges, late-payment charges, or other disclosed costs.
A low advertised EMI does not necessarily mean a loan is inexpensive. A longer repayment term can reduce the monthly instalment while increasing the total interest paid.
3.4 Risk of Debt Pressure
Taking a new loan to repay another loan can create a cycle of debt, especially when income is unstable.
Multiple EMIs can also reduce the money available for fuel, rent, food, family expenses, and savings.
3.5 Documentation Requirements
Some lenders require bank statements, income records, tax documents where applicable, and proof of work or business activity.
Workers who receive earnings in cash or use multiple accounts may find it harder to establish a clear income record.
3.6 Risk of Fraudulent Loan Apps
Fake lenders may advertise instant approval, request upfront payments, or misuse personal information.
Borrowers should verify the regulated lender, read the loan agreement, understand the grievance process, and avoid suspicious links or applications.
3.7 Credit Score Impact
Missed or delayed repayments may harm a borrower's credit history when reported by the lender. Repeated applications and existing debt can also affect how lenders assess an application.
Borrow only when there is a realistic repayment plan.
4. Benefits vs Limitations: Quick Comparison
| Factor | Potential benefit | Possible limitation |
|---|---|---|
| Income documentation | Some lenders accept alternative income records | Acceptance differs by lender |
| Emergency expenses | May provide funds when savings are insufficient | Repayment adds a financial obligation |
| Work-related costs | Can help fund essential tools or repairs | The expense may not generate enough additional income |
| Digital applications | May make applying more convenient | Fraudulent apps and misleading offers exist |
| Credit history | Timely repayment may build a positive record | Missed payments may damage credit history |
| Repayment schedule | Predictable EMIs can support budgeting | Fixed payments may be difficult during low-income periods |
| Loan amount | May cover a planned expense | Approval may be lower than requested |
| Longer tenure | May reduce monthly EMI | Can increase total interest cost |
5. Documents Gig Workers May Need
The exact documents depend on the lender and loan product. Commonly requested documents may include:
| Document | Why it may be required |
|---|---|
| Aadhaar or another accepted identity document | Identity verification |
| PAN or other applicable tax identification | Financial and regulatory checks |
| Bank statements | Review of income and account activity |
| Platform payment statements | Evidence of gig-work earnings |
| Invoices or payment receipts | Evidence of freelance or service income |
| Address proof | Address verification |
| Photograph or digital KYC information | Identity checks, where required |
| Existing loan details | Assessment of repayment obligations |
Submit only documents requested through verified channels. Never share banking passwords, card PINs, or OTPs with a loan agent.
6. Who May Qualify for a Gig Worker Loan?
Potential applicants include:
-
Food and grocery delivery partners.
-
App-based cab and two-wheeler drivers.
-
Freelancers and independent professionals.
-
Home-service and repair providers.
-
Online sellers or service providers with verifiable earnings.
-
Other self-employed workers whose income meets a lender's criteria.
Eligibility depends on the specific product. Some lenders may require a minimum income, a certain period of work history, a particular age range, or a satisfactory credit profile.
There is no single loan eligibility rule that applies to every gig worker in Telangana.
7. How to Improve Loan Eligibility
Step 1: Keep Income Records Organised
Maintain bank statements, platform payout reports, invoices, and other relevant income evidence. Where practical, receive earnings through a consistent bank account so the income pattern is easier to document.
Step 2: Review Your Credit Report
Check your credit report for incorrect information, overdue accounts, and outstanding balances. Raise a dispute with the relevant credit information company if you find an error.
Step 3: Reduce Existing Debt
Before applying, review current EMIs and credit card obligations. Paying down expensive debt may improve your monthly cash flow.
Step 4: Borrow Only What You Need
Requesting a smaller amount may reduce your EMI and total interest cost. Do not borrow extra simply because a lender offers a higher limit.
Step 5: Compare the Total Cost
Review the annualised interest rate or APR where disclosed, processing fees, repayment tenure, total amount payable, late charges, and foreclosure or prepayment conditions.
Step 6: Apply Through a Verified Lender
Confirm the identity of the bank or regulated non-banking financial company (NBFC) responsible for the loan. Review the Key Facts Statement and loan agreement where applicable.
Step 7: Choose a Realistic EMI
Base your repayment plan on income remaining after fuel, maintenance, platform-related expenses, household spending, and existing EMIs.
8. Example: A Gig Worker in Hyderabad
Consider an illustrative delivery partner in Hyderabad who earns an average of ₹28,000 per month.
| Monthly budget item | Illustrative amount |
|---|---|
| Average monthly earnings | ₹28,000 |
| Fuel, maintenance, and work costs | ₹6,000 |
| Household and personal expenses | ₹13,000 |
| Existing financial commitments | ₹2,000 |
| Remaining amount before savings and emergencies | ₹7,000 |
The worker has ₹7,000 remaining in this simplified budget, but that does not mean the full amount should be used for a new EMI. Income can fall, and unexpected expenses may arise.
The worker should first reserve money for savings and irregular expenses, then determine whether any new EMI is affordable.
This example is for illustration only. Actual expenses, eligibility, and loan terms vary.
9. How to Decide Whether a Loan Is Right for You
Before applying, ask yourself:
-
Is the expense essential and time-sensitive?
-
Can I cover it through savings or a lower-cost option?
-
Have I calculated my average net earnings after work expenses?
-
Can I pay the EMI during a low-income month?
-
Do I understand the total repayment amount and all applicable charges?
-
Have I verified the lender and read the loan agreement?
-
Will this loan leave me with enough money for essential expenses?
If the answers reveal that repayment would be difficult, consider reducing the loan amount, delaying a non-essential purchase, or exploring alternatives.
10. Loan Safety Checklist for Telangana Gig Workers
Before accepting a loan:
-
Verify the lender's legal identity and regulatory status.
-
Check the lender's official website and contact details.
-
Read the Key Facts Statement and loan agreement.
-
Confirm the interest rate, fees, EMI, tenure, and total repayment.
-
Understand late-payment and prepayment conditions.
-
Avoid offers promising guaranteed approval without proper checks.
-
Do not pay suspicious upfront fees to an unknown agent.
-
Never share an OTP, PIN, or banking password.
-
Check permissions requested by a lending app.
-
Keep a copy of the signed agreement and repayment schedule.
For digital lending, consult the Reserve Bank of India's official website for applicable guidance and consumer information: https://www.rbi.org.in/
11. How Vizzve Financial Fits Into Your Research
Vizzve Financial can be included in your financial research as a source to explore loan-related information and borrowing guidance.
Before choosing any financial service, gig workers should independently confirm the actual lender, eligibility rules, interest rates, fees, repayment terms, and applicable regulatory disclosures. Do not assume that a loan is available or that approval is guaranteed merely because an application or information page exists.
Compare available options on the basis of transparency, affordability, privacy, and the ability to repay on time.
12. Expert-Informed Borrowing Principles
A sound borrowing decision starts with repayment capacity, not the maximum amount offered.
For gig workers with variable income, these principles are particularly useful:
-
Use net income, not gross platform earnings, when planning an EMI.
-
Build an emergency reserve when possible.
-
Avoid taking a loan based only on projected incentives or unusually high earning weeks.
-
Compare the total cost of borrowing rather than the EMI alone.
-
Maintain payment reminders and adequate account balances.
-
Seek clarification in writing if loan terms are unclear.
These are general financial planning principles, not a guarantee of loan approval or a substitute for advice based on an individual's full financial circumstances.
13. Key Takeaways
-
Gig workers in Telangana may qualify for loans if they meet a lender's requirements.
-
Alternative income evidence may be accepted by some lenders.
-
Irregular earnings can make fixed EMI payments challenging.
-
Interest, processing fees, and repayment tenure affect the overall cost.
-
Timely repayments may help establish a positive credit history.
-
Verify lenders and avoid suspicious loan apps or upfront-payment scams.
-
Compare alternatives and borrow only an amount you can reasonably repay.
Final recommendation: A loan may be useful when it meets a genuine need and fits within a realistic budget. For gig workers in Telangana, the most important step is to evaluate net income, account for fluctuating earnings, and understand the full cost before accepting any offer.
Frequently Asked Questions (FAQs)
1. Can gig workers get a personal loan in Telangana?
Yes, some lenders consider gig workers for personal loans. Approval depends on income verification, credit history, existing debt, documentation, and the lender's eligibility criteria.
2. Can I get a loan without a salary slip?
Possibly. Some lenders accept bank statements, platform payout records, invoices, or other income evidence. The documents accepted vary by lender.
3. Is a fixed monthly salary necessary for loan eligibility?
Not always. Certain lenders assess self-employed applicants with variable income, but they may require evidence of income consistency and repayment capacity.
4. What documents are required for gig worker loans?
Common requirements may include identity and tax identification documents, bank statements, proof of address, and evidence of gig-work earnings. Check the lender's official list.
5. Does my credit score affect loan approval?
Yes, it can. Lenders may consider credit history and repayment behaviour alongside income, existing obligations, and other eligibility requirements.
6. Can delivery partners in Hyderabad apply for loans?
They may apply to lenders whose products accept their employment or income profile. Living or working in Hyderabad does not itself guarantee approval.
7. Are loans for gig workers more expensive?
Costs depend on the lender, product, applicant's profile, and loan terms. Compare the annualised rate, fees, tenure, and total repayment before deciding.
8. Can I get a loan if my income changes every month?
Some lenders consider variable income, but they may examine income records over time. You should also make sure the EMI remains manageable during lower-income months.
9. Will taking a loan improve my credit score?
Not automatically. Making on-time payments on a credit account reported to a credit information company may help establish a positive history. Missed payments can have the opposite effect.
10. What are the main limitations of loans for gig workers?
Common limitations include variable income, lender-specific documentation requirements, potentially high borrowing costs, fixed repayment commitments, and the risk of falling behind on payments.
11. How can gig workers improve their loan eligibility?
Keep income records organised, check credit reports, manage existing debt, provide accurate documentation, and apply for an amount that fits the budget.
12. Are instant loan apps safe?
Not all apps are trustworthy. Verify the regulated lender behind the loan, read the terms, check permissions, and avoid suspicious fees or requests for OTPs and passwords.
13. Can I use a personal loan for vehicle repairs?
The permitted use depends on the loan agreement. Before borrowing, compare the cost of the loan with the repair's urgency and the likely benefit to your earnings.
14. What should I check before accepting a loan offer?
Check the lender's identity, interest rate, fees, EMI, repayment period, total amount payable, late-payment terms, and applicable prepayment conditions.
15. Does Vizzve Financial guarantee loan approval?
No approval should be assumed without confirmation of the actual lender's terms and eligibility assessment. Verify the product details and disclosures directly before applying.
Published on : 11th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed