

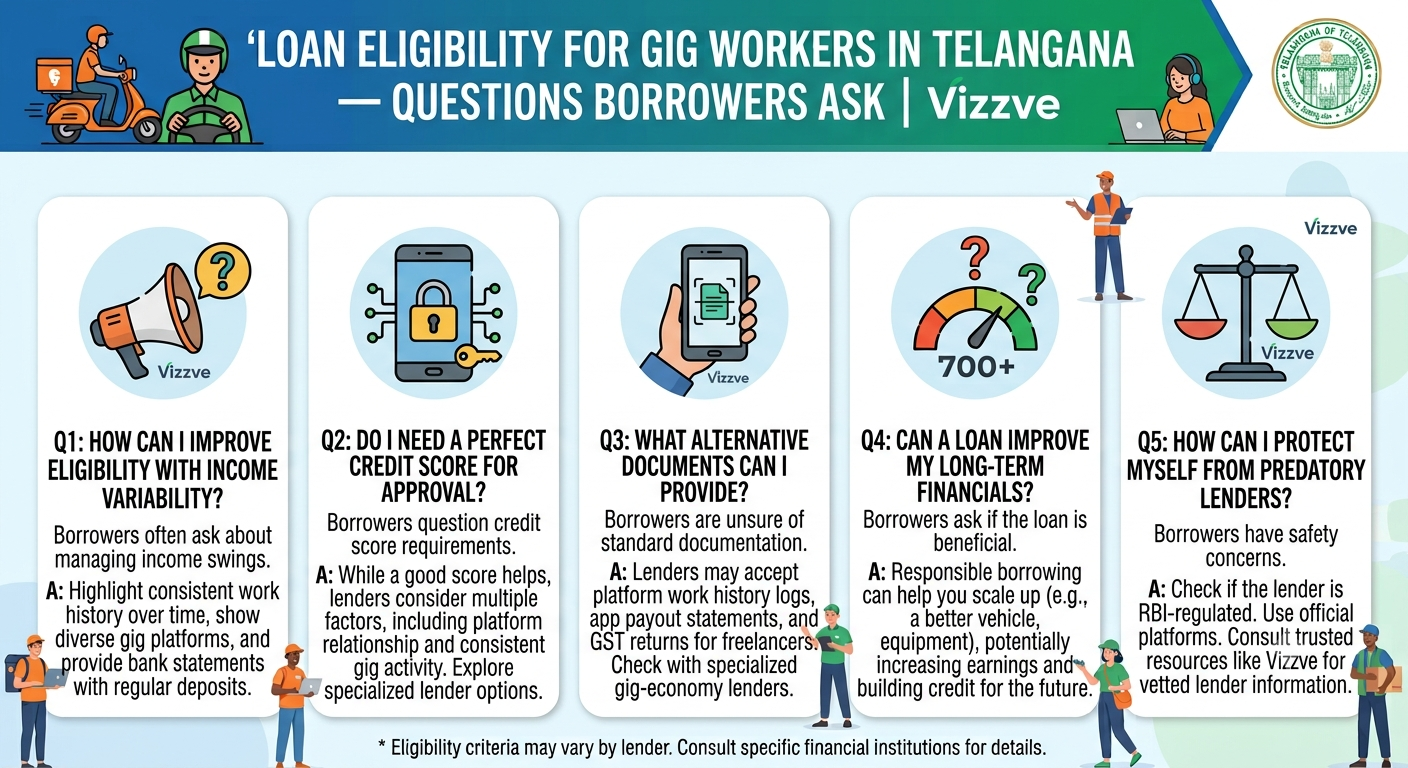
Gig workers in Telangana earn money through delivery services, ride-hailing platforms, freelance projects, home-service businesses, and other independent work. Unlike salaried employees, many do not receive a fixed monthly salary or traditional salary slips.
This can raise important questions when they need a personal loan or other credit product. Can a delivery partner apply for a loan? What documents can prove income? Does a credit score matter? How can borrowers avoid fraud and choose affordable repayments?
Loan eligibility for gig workers in Telangana depends on the lender's criteria, verified income, credit history, existing financial commitments, and repayment capacity. Some lenders may accept alternative income documents, but approval is never guaranteed.
This guide answers common borrower questions in simple language to help gig workers make informed financial decisions.
AI Answer Box: Can Gig Workers Get Loans in Telangana?
Yes, some lenders consider gig workers in Telangana for personal loans and other credit products. Eligibility may depend on average income, bank statements, platform payout records, credit history, existing debts, identity verification, and the lender's policies.
Workers who do not have salary slips may be able to submit alternative income evidence if the lender accepts it. Before applying, compare interest rates, fees, total repayment, and EMI affordability.
1. Understanding Loan Eligibility for Gig Workers
Loan eligibility is the set of conditions a lender uses to assess whether someone qualifies for credit.
For gig workers, lenders may examine:
-
Average monthly income and its consistency.
-
Bank statements and transaction history.
-
Platform payouts, invoices, or other income records.
-
Credit score and repayment history.
-
Existing loans and credit card obligations.
-
Identity and address verification.
-
Age, work history, and product-specific requirements.
The requirements differ across banks, non-banking financial companies (NBFCs), and loan products. Working for a recognised delivery or transport platform does not automatically qualify someone for a loan.
2. Questions Borrowers Ask About Gig Worker Loans
Q1. Can gig workers in Telangana apply for personal loans?
Yes. Some lenders accept applications from self-employed workers, freelancers, and platform-based workers. Approval depends on their eligibility requirements and the applicant's ability to demonstrate repayment capacity.
Q2. Can I get a loan without a salary slip?
Possibly. Some lenders may accept bank statements, platform payout records, invoices, or other evidence of income instead of a conventional salary slip.
Check the lender's document requirements before applying.
Q3. What documents are required for gig worker loans?
Commonly requested documents may include:
-
Aadhaar or another accepted identity document.
-
PAN or applicable tax identification details.
-
Recent bank statements.
-
Platform earnings or payment records.
-
Accepted address proof.
-
Invoices or receipts for freelance work, where relevant.
Requirements vary by lender and loan product.
Q4. Do delivery partners in Hyderabad qualify for loans?
Delivery partners in Hyderabad may qualify if they meet the lender's income, documentation, credit, and other requirements. Their occupation or location alone does not guarantee approval.
Q5. Is a minimum monthly income required?
Many lenders set minimum income criteria, but the amount differs by product and provider. Some may also consider income consistency and existing debt rather than relying only on one month's earnings.
Check the exact criteria for the product you intend to apply for.
Q6. Does my credit score affect loan eligibility?
Yes. A lender may consider your credit score and repayment history when assessing an application. Income, existing debt, documentation, and other eligibility factors may also influence the decision.
Q7. Can I get a loan if my income changes every month?
Some lenders consider applicants with variable earnings. They may review bank statements or income records covering a period of time.
Before applying, calculate your average income after work expenses and ensure that the EMI remains affordable during slower months.
Q8. How can I improve my loan eligibility?
You can strengthen your application by:
-
Keeping income and bank records organised.
-
Paying existing EMIs on time.
-
Reviewing your credit report for errors.
-
Reducing expensive outstanding debt where possible.
-
Submitting accurate documents.
-
Applying for an amount that fits your budget.
These steps may help, but they cannot guarantee approval.
Q9. Can I apply online for a gig worker loan?
Some lenders provide online application facilities. Apply through a verified official website or authorised channel, read the terms carefully, and confirm which bank or NBFC is responsible for the loan.
Q10. How long does loan approval take?
Processing time depends on the lender, product, document verification, and application details. Some digital processes may be faster than others, but no particular approval time should be assumed without checking the provider's terms.
Q11. Are loans for gig workers more expensive than salaried loans?
Not necessarily. The cost depends on the lender, loan product, applicant profile, interest rate, fees, and repayment period. Compare the full cost of each offer instead of assuming that every gig worker receives the same rate.
Q12. What is the best loan amount to apply for?
The suitable amount depends on your actual need and repayment capacity. Borrow only what is necessary and avoid choosing an amount simply because a lender offers a higher limit.
Q13. How do I calculate an affordable EMI?
Start with your average monthly earnings, then deduct fuel, maintenance, platform-related expenses, household costs, existing debt payments, and money needed for savings or emergencies.
The remaining amount helps you assess what repayment may be manageable. Do not treat all remaining money as available for a new EMI.
Q14. Are instant loan apps safe?
Not all loan apps are trustworthy. Verify the actual lender, read the agreement, check app permissions, and avoid suspicious upfront payments or requests for OTPs, PINs, or banking passwords.
For digital lending information, consult the Reserve Bank of India at https://www.rbi.org.in/.
Q15. Can taking a loan improve my credit score?
Timely repayment on a credit account reported to a credit information company may help establish a positive credit history. However, taking a loan does not automatically improve a credit score, and missed payments may damage your credit history.
Q16. Why might a gig worker's loan application be rejected?
Possible reasons include insufficient verifiable income, a weak credit history, high existing debt, incomplete documents, or not meeting the lender's criteria.
Ask the lender for the reason where available and correct any errors before making another application.
Q17. Can I use a personal loan for vehicle repairs?
That depends on the loan's permitted use. If repairs are essential for earning income, compare the urgency and cost of the work against the borrowing cost and your ability to repay.
Q18. Should I take a new loan to repay an existing loan?
Be cautious. Borrowing to repay another loan can create a cycle of debt, particularly when income is unstable. Compare alternatives and understand the total cost before considering any consolidation or refinancing product.
Q19. What charges should I check before accepting a loan?
Review the interest rate, applicable annualised borrowing cost disclosures, processing fees, taxes, EMI, repayment period, late-payment charges, and prepayment or foreclosure conditions.
Read the Key Facts Statement and loan agreement where applicable.
Q20. Does Vizzve Financial guarantee loan approval?
No approval should be assumed without confirmation of the specific product and lender's assessment. Verify the actual lender, eligibility requirements, fees, terms, and relevant regulatory disclosures before applying.
3. Documents Gig Workers May Need
| Document | Why it may be needed |
|---|---|
| Accepted identity proof | Identity verification |
| PAN or applicable tax identification | Financial and regulatory checks |
| Bank statements | Review of income and account activity |
| Platform payout records | Evidence of gig-work earnings |
| Invoices or receipts | Evidence of freelance or service income |
| Address proof | Address verification |
| Existing loan information | Assessment of current financial commitments |
Only submit documents through verified channels and provide accurate information.
4. Common Reasons for Loan Rejection
A loan application may be rejected because of:
-
Income that cannot be verified.
-
Missing or inconsistent documents.
-
High existing debt.
-
A credit history that does not meet the lender's requirements.
-
Failure to meet minimum age, income, or work-history criteria.
-
Incomplete application information.
A rejection does not necessarily mean that every lender will reject the applicant. Review the reason, improve the application where possible, and avoid submitting numerous applications without understanding the requirements.
5. Benefits and Limitations of Loans for Gig Workers
| Potential benefits | Possible limitations |
|---|---|
| Access to funds for eligible borrowers | Approval is not guaranteed |
| Alternative income documents may be accepted | Documentation rules differ by lender |
| May help cover urgent or essential costs | Interest and fees add to the cost |
| Timely repayment may build credit history | Missed payments can affect credit history |
| Digital applications may be convenient | Fraudulent offers and data risks exist |
| May fund essential work-related expenses | Fixed EMIs can strain variable income |
6. Example: A Gig Worker's Monthly Budget in Telangana
Consider an illustrative delivery partner in Hyderabad who earns ₹29,000 per month on average.
| Monthly budget item | Illustrative amount |
|---|---|
| Average monthly earnings | ₹29,000 |
| Fuel and work expenses | ₹6,000 |
| Household and personal expenses | ₹13,500 |
| Existing EMI | ₹2,000 |
| Remaining before savings and unexpected costs | ₹7,500 |
The remaining ₹7,500 is not automatically available for a new EMI. The worker must account for emergency savings, vehicle repairs, medical expenses, and periods when fewer orders are available.
This example is for educational purposes only. Actual income, expenses, eligibility, and loan terms vary.
7. How to Apply for a Loan More Safely
Step 1: Identify Your Financial Need
Decide how much you need and whether the expense can be reduced, delayed, or covered through savings.
Step 2: Review Your Income
Use several months of income records where possible. Deduct work expenses before calculating repayment capacity.
Step 3: Check Your Credit Report
Review your credit history and correct any errors through the appropriate credit information company.
Step 4: Compare Loan Offers
Compare interest rates, fees, repayment periods, and total amounts payable from verified lenders.
Step 5: Prepare Documents
Gather the documents the lender accepts for your income and identity verification.
Step 6: Read the Loan Agreement
Confirm the sanctioned amount, net disbursal, EMI, fees, due dates, and repayment conditions before accepting the offer.
Step 7: Keep Records
Save the loan agreement, payment schedule, and receipts. Set reminders for EMI dates.
8. Loan Safety Tips for Borrowers
-
Verify the bank or NBFC responsible for the loan.
-
Use official application channels.
-
Read the Key Facts Statement and agreement where applicable.
-
Check the full cost of borrowing.
-
Never share OTPs, passwords, or PINs with an agent.
-
Avoid unexplained payments to unknown individuals.
-
Check app permissions and privacy information.
-
Borrow only an amount you can realistically repay.
-
Contact the lender early if you anticipate difficulty making payments.
9. Official Resources for Borrowers
Use official resources to verify information and understand consumer protections:
-
Reserve Bank of India: https://www.rbi.org.in/
-
National Consumer Helpline: https://consumerhelpline.gov.in/
-
National Cyber Crime Reporting Portal: https://cybercrime.gov.in/
-
TransUnion CIBIL: https://www.cibil.com/
-
UIDAI: https://uidai.gov.in/
Check the relevant official page for the specific issue you want to understand or report.
10. Vizzve Financial: Helping Borrowers Make Informed Decisions
Vizzve Financial can be included as a resource for readers researching loans and financial awareness.
Before choosing any financial product, verify the actual lender, eligibility criteria, interest rates, fees, privacy practices, and repayment terms independently. Do not assume that any loan is available or that approval is guaranteed without confirmation from the relevant provider.
Key Takeaways
-
Some lenders consider gig workers in Telangana for personal loans.
-
Salary slips may not be mandatory for every lender, but acceptable income evidence is important.
-
Credit history, existing debt, and repayment capacity can influence eligibility.
-
Compare total repayment costs, not just the advertised EMI.
-
Verify lenders and avoid suspicious loan apps or unexplained advance payments.
-
Maintain accurate income records and apply for an affordable amount.
-
Loan approval and terms depend on the lender's assessment.
Final advice: Before applying for a loan, understand your eligibility, organise your documents, compare costs, and ensure the repayment schedule fits your income. A well-informed decision can help reduce avoidable financial stress.
Published on : 11th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed