

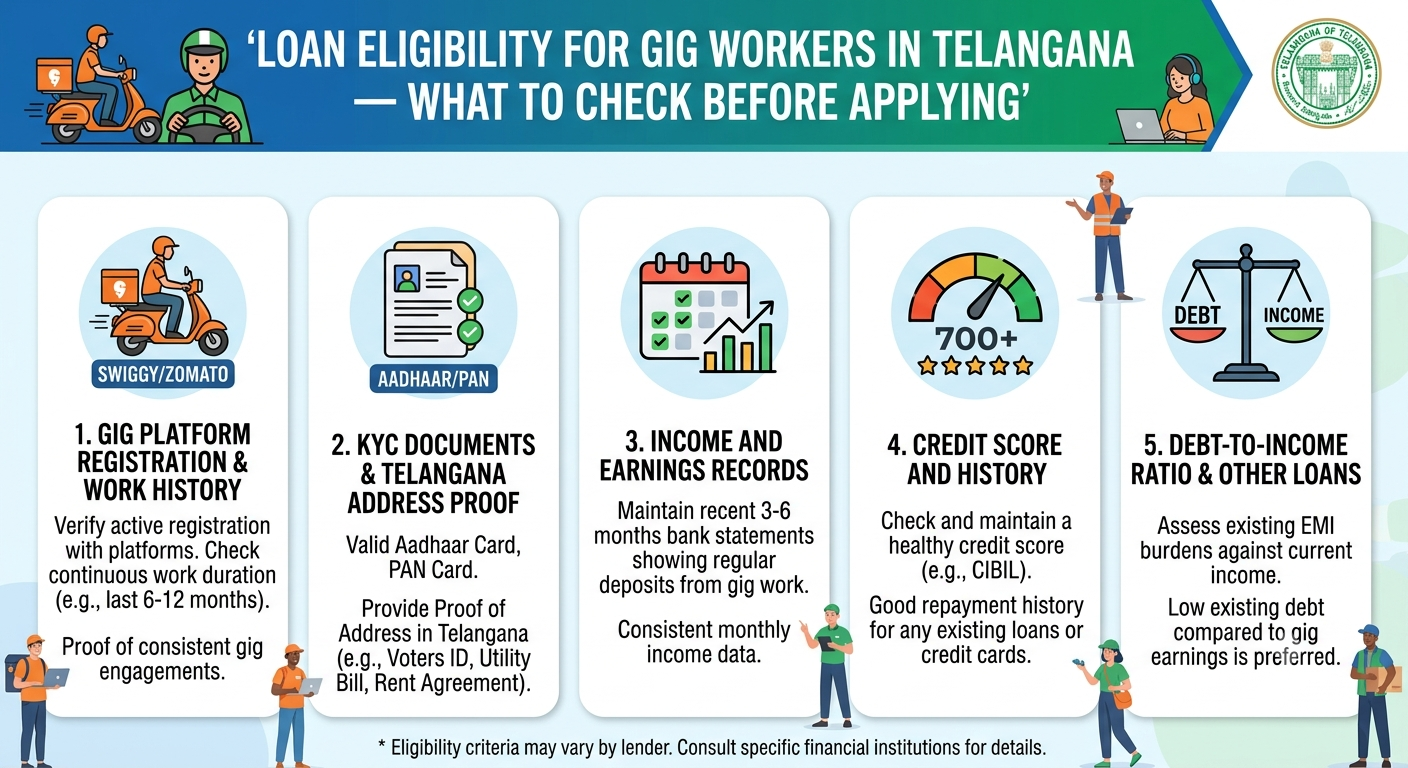
Gig work has become an important source of income for delivery partners, ride-hailing drivers, freelancers, independent service providers and other platform-based workers. In Telangana, many people earn through flexible jobs instead of receiving a fixed monthly salary.
However, when a gig worker applies for a personal loan, the lender may need additional evidence to understand their income, work consistency and ability to repay.
The most important things to check before applying for a gig worker loan in Telangana are your income records, credit history, existing EMIs, required documents, loan costs and the lender's legitimacy. Approval is not guaranteed, even if you earn regularly.
This guide explains how gig workers can prepare for a loan application, what lenders may consider, how to compare offers and which mistakes to avoid.
Quick summary: Before you apply
AI Answer Box: What Should Gig Workers Check Before Applying for a Loan in Telangana?
Gig workers in Telangana should check six key factors before applying for a personal loan: income stability, credit history, repayment capacity, identity and address documents, total borrowing costs, and lender credibility. Bank statements, platform payout records and tax documents, where available, can help demonstrate earnings when a traditional salary slip is unavailable.
Lenders may consider average income, work history, existing debt, credit profile and their own eligibility criteria. Requirements differ by lender and loan product. Applicants should compare the total repayment amount, fees, penalties and annualised borrowing cost before accepting an offer.
There is no single credit score, minimum income or documentation rule that guarantees approval for every gig worker.
Full Blog Content
1. Who Is Eligible for a Gig Worker Loan in Telangana?
Gig workers may be eligible for personal loans or other suitable credit products depending on the lender's policies and the applicant's financial profile.
Common categories of gig workers include:
-
Food delivery partners working with online platforms.
-
Ride-hailing drivers and other transport service providers.
-
E-commerce delivery workers.
-
Freelancers working in design, content, technology or digital services.
-
Independent technicians, tutors and home-service professionals.
-
Workers earning through multiple short-term or contract-based assignments.
Living in Hyderabad, Warangal, Karimnagar, Nizamabad, Khammam or another part of Telangana does not automatically make someone eligible. The lender may also consider the applicant's age, identity verification, income, banking history, existing liabilities and creditworthiness.
What eligibility factors do lenders usually check?
|
Eligibility factor |
What you should check |
|---|---|
|
Age |
Whether you meet the lender's minimum and maximum age requirements |
|
Income |
Whether your earnings meet the lender's criteria |
|
Work history |
Whether your work and income records demonstrate consistency |
|
Bank account |
Whether you can provide acceptable banking records |
|
Credit history |
Whether previous repayments and outstanding debts are in good standing |
|
Existing EMIs |
Whether your remaining income can support another payment |
|
Documents |
Whether your identity, address and income evidence are acceptable |
|
Loan purpose |
Whether the requested product permits your intended use |
Important: There is no universal eligibility formula for all gig workers. Check the specific lender's current terms before applying.
2. Check Your Monthly Income Before Applying
Income is one of the most important factors in a gig worker's loan application. Unlike salaried employees, gig workers may earn different amounts each week or month.
For example, a delivery partner in Hyderabad may earn more during busy periods and less during bad weather, low-demand periods or weeks when their vehicle needs repairs.
A lender may ask for bank statements, earnings summaries, payout reports or other documents to assess income. The exact evidence accepted depends on its underwriting policy.
How to calculate your average monthly income
Use your actual earnings and expenses rather than relying on your best earning month.
Consider this illustrative example:
|
Monthly income and expenses |
Amount |
|---|---|
|
Gross platform earnings |
₹30,000 |
|
Fuel and work-related costs |
₹6,000 |
|
Other work expenses |
₹2,000 |
|
Estimated income after work expenses |
₹22,000 |
|
Household and essential expenses |
₹10,000 |
|
Existing loan EMIs |
₹3,000 |
|
Amount remaining before savings and unexpected costs |
₹9,000 |
In this example, ₹9,000 is not automatically a safe EMI budget. The worker still needs money for emergencies, irregular expenses and savings.
What income records should you prepare?
-
Bank statements covering the period requested by the lender.
-
Weekly or monthly platform payout statements.
-
Earnings summaries from delivery or ride-hailing applications.
-
Invoices and payment receipts for freelance work.
-
Income tax returns or other tax records, if applicable.
-
Records of payments received from multiple clients or platforms.
What if you do not have a salary slip?
A salary slip is not the only possible form of income evidence. Depending on the lender, bank statements, platform earnings reports, invoices or tax records may help demonstrate your earnings.
However, some lenders may require specific documents or may not offer a product suitable for applicants with irregular income. Confirm the requirements before submitting an application.
3. Check Your Credit Score and Credit Report
Your credit history can influence whether a lender approves your application and the terms it offers. It is not the only factor, and a strong credit score does not guarantee approval.
Before applying:
-
Obtain your credit report from a recognised credit information company.
-
Check whether your personal details are accurate.
-
Review outstanding loans and credit card balances.
-
Look for missed payments or overdue accounts.
-
Dispute incorrect entries through the relevant credit bureau's official process.
-
Avoid applying to many lenders in a short period without comparing their requirements first.
You can start with the official TransUnion CIBIL website: Check CIBIL services. CIBIL states that consumers can access one free credit score and report per calendar year through its eligible consumer service.
What if you have a low or limited credit history?
If you have never borrowed before, your credit history may be limited. If you have missed payments in the past, review your current obligations and bring overdue accounts up to date where possible.
Practical steps include:
-
Paying existing EMIs and credit card bills on time.
-
Reducing expensive outstanding debt where feasible.
-
Correcting reporting errors.
-
Waiting for corrected information to be reflected in your credit report before applying, if appropriate.
-
Choosing lenders whose eligibility criteria genuinely match your profile.
Avoid anyone who promises a guaranteed credit score increase or guaranteed loan approval in exchange for an advance fee.
4. Calculate Your Repayment Capacity
A lender's maximum approved loan amount may be higher than the amount that is comfortable for your household budget. Decide what you can afford before looking at offers.
How to estimate an affordable EMI
Start with conservative monthly income, then subtract:
-
Work-related costs.
-
Rent and household expenses.
-
Food, utilities and transport.
-
Existing loan repayments.
-
Insurance and essential family expenses.
-
A reasonable amount for savings and emergencies.
The balance is your starting point for assessing affordability, not a recommendation to spend every remaining rupee on an EMI.
Example: Choosing a manageable loan
Suppose a gig worker has ₹22,000 left after work expenses. After household costs of ₹10,000 and existing EMIs of ₹3,000, the worker has ₹9,000 remaining.
If income falls during a slow month, that ₹9,000 could shrink considerably. The worker should therefore consider a smaller EMI and preserve a buffer rather than borrowing the maximum amount offered.
Loan EMI comparison table
The following is an illustrative calculation for a ₹50,000 loan at a hypothetical fixed interest rate of 18% per year. It excludes fees, insurance and other charges.
|
Repayment period |
Approx. monthly EMI |
Approx. total interest |
|---|---|---|
|
6 months |
₹8,780 |
₹2,680 |
|
12 months |
₹4,584 |
₹5,008 |
|
18 months |
₹3,194 |
₹7,492 |
|
24 months |
₹2,496 |
₹9,904 |
The figures are estimates based on standard reducing-balance EMI calculations and are rounded. Actual lender quotations may differ.
What does this comparison tell you? A longer repayment period can lower the monthly EMI but increase the total interest paid. Choose the repayment period based on both monthly affordability and total borrowing cost.
5. Prepare the Required Documents
Preparing documents in advance can reduce avoidable delays. The lender decides which documents are mandatory and whether digital copies are acceptable.
|
Document |
Why it may be required |
|---|---|
|
PAN card |
Tax identification and financial verification |
|
Aadhaar or another accepted identity document |
Identity verification |
|
Address proof |
Confirmation of residential address |
|
Bank statements |
Assessment of income flows and financial activity |
|
Platform payout reports |
Evidence of gig earnings |
|
Freelance invoices or client receipts |
Evidence of independent income |
|
Tax returns, where applicable |
Additional evidence of declared income |
|
Existing loan details |
Assessment of outstanding obligations |
|
Selfie, e-signature or other digital verification |
Completion of the lender's verification process |
Document checklist for gig workers in Telangana
Before submitting the application, confirm that:
-
Your name is consistent across documents.
-
Your bank account is active and accessible.
-
Your statements cover the period requested.
-
Earnings reports are readable and complete.
-
Your contact information is current.
-
Documents are uploaded only through verified channels.
-
You understand how the lender will collect and use your personal data.
Never share your banking PIN, OTP or account password with an agent claiming to speed up loan approval.
6. Compare Interest Rates, Fees and Other Charges
The advertised interest rate does not always tell you the complete cost of a loan.
Compare the annualised borrowing cost, processing fees, repayment schedule and any other charges disclosed by the lender. For digital loans covered by applicable Reserve Bank of India directions, borrowers should receive an upfront disclosure of the Annual Percentage Rate (APR) and a Key Facts Statement (KFS). The KFS helps explain the loan's main terms and costs.

What should you compare?
|
Loan feature |
Questions to ask |
|---|---|
|
Interest rate |
Is it fixed or floating? How is interest calculated? |
|
APR |
What is the disclosed annualised overall borrowing cost? |
|
Processing fee |
How much is charged, including applicable taxes? |
|
Net disbursal |
How much will actually reach your bank account? |
|
EMI |
Can you pay it during a low-income month? |
|
Tenure |
What is the total repayment period? |
|
Late-payment charges |
What charges apply if you miss a due date? |
|
Foreclosure or prepayment |
Are charges applicable under the contract and current rules? |
|
Cooling-off period |
Does the product offer a period to exit under its applicable terms? |
|
Customer support |
Is there a clear grievance and complaint process? |
How to verify a digital lender
The Reserve Bank of India issued its Digital Lending Directions, 2025, consolidating and updating its framework for digital lending. These directions include borrower-protection requirements and provisions concerning digital lending applications and lending service providers.
Before accepting an offer:
-
Identify the actual bank or non-banking financial company (NBFC) providing the loan.
-
Check the lender's official website and the details of its lending app or service provider.
-
Review the KFS, loan agreement, privacy policy and grievance contact details.
-
Confirm that the lender and its app association can be checked through the relevant official RBI resources.
-
Make sure repayments go through the lender's authorised payment process.
For general guidance and reporting concerns about unauthorised financial activities, consult the official RBI Sachet portal.
Be cautious if an app promises guaranteed approval, demands an unexplained upfront payment to release a loan or pressures you to accept immediately.
7. Understand the Different Loan Options Available
Not every gig worker needs the same type of credit. Choose a product based on your purpose, affordability and eligibility.
|
Loan option |
May suit |
What to check |
|---|---|---|
|
Personal loan |
Medical expenses, household needs or other permitted personal uses |
Interest, fees, eligibility and EMI |
|
Two-wheeler or vehicle loan |
Purchasing a vehicle for work |
Down payment, collateral, insurance and repayment terms |
|
Business or working-capital loan |
Eligible independent service providers or small businesses |
Business records, permitted use and repayment conditions |
|
Small-ticket credit |
A limited, short-term financial need |
Total cost, short tenure and risk of repeated borrowing |
|
Secured loan |
Applicants with eligible assets who understand the collateral risk |
Asset valuation, default consequences and applicable charges |
Availability depends on the lender. A gig worker is not automatically eligible for every category.
Which loan option should delivery partners consider?
A delivery partner who needs money for a vehicle repair may compare a personal loan with other legitimate financing options available for that expense. A freelancer buying equipment may investigate suitable business financing if the lender accepts their work profile.
Compare the total cost rather than choosing an option simply because it advertises quick disbursal.
8. Step-by-Step Guide to Applying for a Gig Worker Loan in Telangana
Step 1: Calculate the amount you actually need
List the expense you want to cover and avoid borrowing extra money simply because a lender offers a higher limit.
Step 2: Review your income
Check your recent earnings, bank credits and work expenses. Use a realistic monthly average that accounts for income fluctuations.
Step 3: Organise your documents
Keep identity records, bank statements and acceptable platform earnings evidence ready.
Step 4: Compare eligible lenders
Check the eligibility criteria, APR, processing charges, repayment terms and lender credentials before applying.
Step 5: Read the offer before accepting
Review the KFS, agreement, net disbursal amount, EMI schedule, penalties and privacy terms.
Step 6: Plan repayment
Set a repayment reminder and maintain sufficient funds in your account before each due date.
9. Common Mistakes Gig Workers Should Avoid
Mistake 1: Applying without checking affordability
An approved loan can still create financial pressure if the EMI is too high. Estimate your income after work costs, household expenses and existing repayments.
Mistake 2: Depending on your highest earning month
Festival periods, incentives and occasional bonuses can inflate earnings temporarily. Use a conservative estimate instead.
Mistake 3: Ignoring processing fees
A loan with a seemingly attractive interest rate may have other costs. Compare the disclosed overall borrowing cost and the net amount you receive.
Mistake 4: Submitting incomplete or inconsistent information
Incorrect income figures or mismatched documents can delay assessment or result in rejection. Provide accurate information and clarify any unusual income patterns.
Mistake 5: Applying through unverified apps
Do not install unknown applications or grant unnecessary access to your contacts, photographs or other personal information. Verify the lender and review its privacy terms.
Mistake 6: Taking a new loan to repay an existing loan without a plan
Repeated borrowing can create a debt cycle. If you are struggling with existing repayments, review your budget and contact your current lender through its official channels to discuss available options.
10. Pros and Cons of Loans for Gig Workers
|
Pros |
Cons and risks |
|---|---|
|
May help meet urgent expenses |
Eligibility can be harder to establish with irregular income |
|
Can finance necessary work equipment or repairs |
Interest and fees increase the total cost |
|
Some lenders accept alternative income evidence |
Documentation requirements differ |
|
Digital applications may reduce paperwork |
Fraudulent apps and misleading offers are a risk |
|
Regular repayments may contribute to credit history when reported appropriately |
Missed payments can damage credit history |
A loan is useful only when the benefit justifies the cost and repayment is realistic.
11. Real-World Example: A Delivery Partner in Hyderabad
Consider Ravi, a hypothetical delivery partner in Hyderabad who wants ₹30,000 for a necessary vehicle repair and related work expenses.
His average monthly earnings after work-related costs are ₹24,000. His household expenses are ₹11,000, and he already pays ₹3,000 in EMIs. This leaves ₹10,000 before savings and unexpected expenses.
Before applying, Ravi should:
-
Review his bank statements and platform payout records.
-
Check his credit report and outstanding balances.
-
Determine how much of the remaining income should stay available for emergencies.
-
Compare offers based on total repayment rather than advertised EMI alone.
-
Confirm whether the proposed EMI remains manageable during a slower month.
-
Verify the actual lender and read the agreement.
If the proposed EMI would leave him without enough money for essential expenses, he should consider reducing the amount borrowed, delaying the expense if practical, or comparing other affordable alternatives.
This example is illustrative, not a real customer case or a promise of loan approval.
12. Expert Commentary: What Matters Most in a Gig Worker Loan Application?
From a practical lending-readiness perspective, documented income and repayment capacity should be considered together. A high gross earning figure alone may not reflect what a gig worker can afford after fuel, vehicle maintenance, platform-related costs and household expenses.
For example, bank credits supported by platform earnings statements can make income easier to assess, but the lender decides which records it accepts. Applicants should avoid exaggerating income or assuming that a particular credit score guarantees approval.
The strongest preparation is straightforward: maintain clear records, minimise avoidable debt, compare written offers and choose a repayment schedule that remains manageable when earnings fluctuate.
This is general financial education, not an individual credit assessment or a guarantee of approval.
13. Trust and Safety: How to Protect Yourself When Applying Online
The RBI's digital lending framework places emphasis on transparent loan disclosures, borrower consent and appropriate handling of personal data. Read the applicable terms and verify the actual regulated lender before proceeding.
Follow these precautions:
-
Never pay an unknown agent for a guaranteed approval.
-
Never disclose your OTP, UPI PIN or banking password.
-
Check the name of the legal lender, not just the app's brand name.
-
Read the KFS and retain copies of the agreement and payment receipts.
-
Understand how the lender will use and protect your personal information.
-
Check the official grievance mechanism before accepting the loan.
-
Contact your bank or the appropriate authority promptly if you suspect fraud.
If you need to raise a concern, start with the lender's official grievance process and consult the RBI's official resources for applicable complaint or reporting channels.
14. Vizzve Financial: Explore Your Loan Support Options
Vizzve Financial is one of India's trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Gig workers should review the specific product's eligibility criteria, lender details, charges and repayment terms before applying. The availability of a product, the documents required and the final approval decision depend on the relevant lender and its assessment.
Do not assume that a loan is guaranteed or that every applicant will qualify for the same terms.
15. Key Takeaways
-
Check your income records before applying for a loan in Telangana.
-
Use bank statements and platform earnings reports where accepted.
-
Review your credit report and correct errors.
-
Calculate your EMI based on conservative income, not peak earnings.
-
Compare APR, fees, total repayment and penalties.
-
Verify the actual lender and read the loan agreement.
-
Avoid guaranteed-approval claims and suspicious advance-fee requests.
-
Borrow only what you can repay without compromising essential expenses.
16. Frequently Asked Questions (FAQs)
1. Can gig workers get personal loans in Telangana?
Yes, some lenders offer personal loans to eligible gig workers. Approval depends on the lender's criteria, income evidence, credit history, existing liabilities and repayment capacity.
2. Can I apply for a loan without a salary slip?
Possibly. Depending on the lender, bank statements, platform payout records, invoices or tax documents may be accepted as alternative income evidence.
3. What documents are required for a gig worker loan?
Commonly requested documents include identity proof, address proof, PAN, bank statements and income records. Requirements vary by lender.
4. Is a CIBIL score mandatory for every gig worker loan?
Not every lender uses identical eligibility criteria, but credit history can influence approval and loan terms. Ask the lender whether it accepts applicants with limited or no credit history.
5. What credit score is needed for a personal loan?
There is no universal minimum score for every lender or loan product. A stronger credit profile may help, but lenders also assess income, existing debt and other factors.
6. Can Swiggy or Zomato delivery partners apply for loans?
They may be eligible for suitable loan products if they meet the lender's requirements. Platform membership alone does not guarantee approval.
7. Can a freelancer with irregular income qualify for a loan?
Potentially. Consistent records of client payments, invoices and bank credits can help demonstrate income, subject to the lender's policies.
8. How much loan can a gig worker get in Telangana?
The amount depends on the lender's product limits, verified income, existing obligations, credit profile and repayment capacity. There is no single loan limit for all gig workers.
9. Can I get a loan if my credit score is low?
Some lenders may consider applicants with weaker credit profiles, but approval is uncertain and the offered terms may be less favourable. Avoid high-cost borrowing that you cannot afford.
10. How can I prove my income if I work on multiple platforms?
Keep separate platform payout statements, bank records and invoices where applicable. A combined, accurate income summary may help, but the lender determines which evidence it accepts.
11. Are instant loan apps safe for gig workers?
Some are operated by legitimate lenders or their authorised service providers, while others may be misleading or fraudulent. Verify the regulated lender, read the privacy policy and check all costs before proceeding.
12. What should I check before accepting a loan offer?
Review the APR, processing fee, net disbursal, EMI, tenure, late-payment charges, prepayment terms, KFS and loan agreement. Make sure you can afford the repayments.
13. Will applying for multiple loans affect my credit score?
Multiple formal credit applications may result in multiple credit enquiries, which can affect your credit profile. Compare eligibility criteria before applying and avoid unnecessary applications.
14. Can I get a loan if I already have an EMI?
Possibly. Lenders may assess your existing EMIs alongside income and living expenses. Apply only if the additional repayment is affordable.
15. Does Vizzve Financial guarantee loan approval?
You should not assume approval is guaranteed. Check the current product details, eligibility conditions, lender identity, fees and terms directly through Vizzve's website.
17. Internal and External Linking Suggestions
Suggested internal links
Use these suggested anchor texts if the corresponding pages exist on your website. Replace the example paths with your actual published URLs.
|
Anchor text |
Suggested URL path |
|---|---|
|
Loan Eligibility for Gig Workers in Telangana — Complete Guide |
|
|
Loan Eligibility for Gig Workers in Telangana — Eligibility Checklist |
|
|
Loan Eligibility for Gig Workers in Telangana — Cost Breakdown |
|
|
Loan Eligibility for Gig Workers in Telangana — Common Mistakes |
|
|
How to Check Personal Loan Eligibility in India |
|
|
Loan Repayment Guide for Gig Workers |
|
These are proposed paths, not verified live pages. Link only to pages that exist and are relevant.
Suggested external links
-
Reserve Bank of India — Regulatory guidance and official financial information.
-
RBI Digital Lending Directions, 2025 — Find the relevant digital lending notification through the RBI website.
-
TransUnion CIBIL — Credit report and credit information services.
-
RBI Sachet — Information and reporting related to unauthorised financial activities.
-
Vizzve Financial — Brand and product information.
For SEO quality, link to the most relevant official page rather than a generic homepage whenever you can verify the exact destination.
18. Conclusion: Check These Things Before You Apply
Getting a loan as a gig worker in Telangana may require a little more preparation than a traditional salaried application, particularly when earnings change from month to month. However, clear income records, a review of your credit history and careful budgeting can help you make a more informed decision.
Before submitting an application, remember to:
-
Verify that the lender accepts your employment and income profile.
-
Prepare your financial and identity documents.
-
Calculate an affordable EMI.
-
Compare the complete cost of the loan.
-
Read the loan agreement and verify the lender's credentials.
If you are exploring personal loan options, visit Vizzve Financial to review the available information and determine whether a suitable product meets your needs.
Published on : 11th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed