

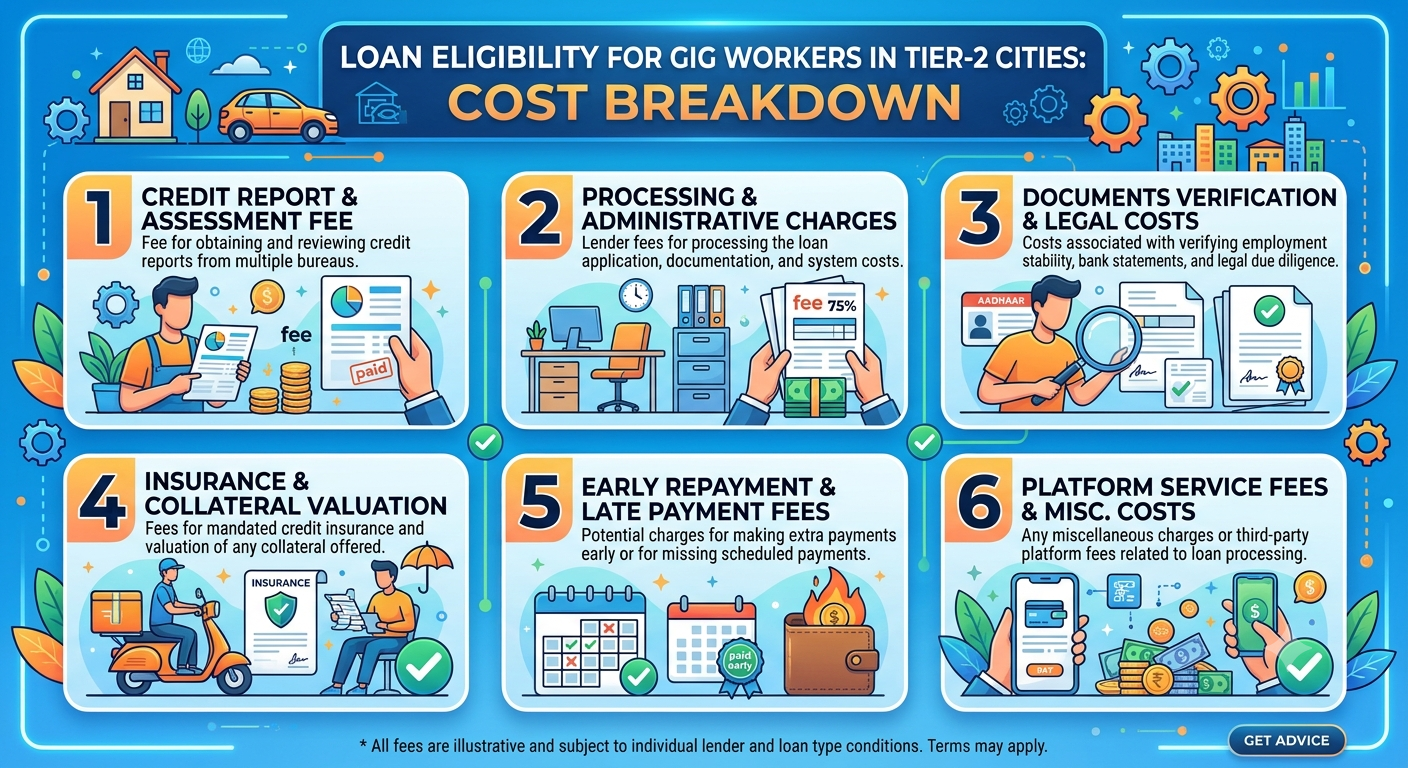
Gig workers in India's Tier-2 cities often depend on flexible earnings from delivery platforms, ride-hailing services, freelance projects and other independent work. Whether they need money for household expenses, vehicle repairs, medical bills or professional equipment, understanding loan costs is essential before applying.
Loan eligibility is not determined by income alone. Lenders may also assess credit history, income consistency, existing debt and repayment capacity. Equally important, borrowers must understand the full cost of a loan—not just the advertised interest rate.
This guide explains the major charges associated with personal loans for gig workers, provides illustrative EMI calculations and shares practical ways to manage borrowing costs.
3. What Does a Loan Cost Breakdown Include?
The total cost of a loan can include several components.
|
Cost component |
What it means |
|---|---|
|
Principal amount |
The money borrowed from the lender |
|
Interest |
The amount charged for borrowing |
|
Processing fee |
A fee charged for processing the application |
|
GST on applicable fees |
Tax charged on eligible services and fees |
|
Insurance charges |
Optional or applicable insurance costs, where offered and agreed to |
|
Late-payment charges |
Charges that may apply when payments are overdue |
|
Foreclosure or prepayment charges |
Charges that may apply when repaying early, subject to applicable rules and contract terms |
Important: Always review the Key Facts Statement (KFS), where applicable, and the loan agreement. The annual percentage rate (APR) is particularly useful because it reflects the annualised cost of credit, including applicable charges as required under the relevant rules.
4. Illustrative Loan Cost Breakdown
Consider a gig worker in a Tier-2 city who needs a personal loan for essential expenses.
The following example uses hypothetical figures for educational purposes. These are not actual Vizzve rates or a lender's offer.
EXAMPLE LOAN
₹50,000
Illustrative interest rate
18% p.a.
Repayment tenure
12 months
Estimated monthly EMI
₹4,584
Total interest
₹5,008
Total repayments
₹55,008
Approximate figures calculated using a reducing-balance EMI formula. Fees, taxes and other charges are excluded.
In this example, the borrower repays approximately ₹55,008 over 12 months, excluding any additional fees. The actual amount may differ based on the lender's calculation, payment schedule and final terms.
5. How Much Does the Loan Tenure Affect the Cost?
A longer repayment period generally reduces the monthly EMI but may increase the total interest paid.
The following comparison uses a hypothetical ₹50,000 loan at 18% annual interest, assuming monthly reducing-balance interest and excluding fees.
|
Tenure |
Approx. monthly EMI |
Approx. total interest |
|---|---|---|
|
6 months |
₹8,776 |
₹2,656 |
|
12 months |
₹4,584 |
₹5,008 |
|
18 months |
₹3,193 |
₹7,474 |
|
24 months |
₹2,496 |
₹9,904 |
These are estimates, not lender quotations. Actual terms may vary.
What should gig workers choose?
-
A shorter tenure can reduce total interest if the EMI is affordable.
-
A longer tenure may offer more monthly flexibility but can increase borrowing costs.
-
The right tenure is one that balances total cost with reliable repayment capacity.
6. Interactive EMI Calculator
Use this simple calculator to estimate your monthly EMI and total interest before comparing loan offers.
₹50,000
18%
12 months
Estimated monthly EMI
₹4,584
Total interest
₹5,008
Total repayment
₹55,008
Estimates assume a fixed annual rate and monthly reducing-balance repayments. Processing fees, taxes, insurance and other charges are not included.
7. What Additional Charges Should Borrowers Check?
Processing fees
Some lenders charge a one-time processing fee. Check whether it is a flat amount or a percentage of the loan and whether GST is added.
GST and other taxes
GST may apply to eligible service fees. Do not assume that the same tax treatment applies to every component of the loan.
Late-payment charges
Missed payments can result in additional charges and may negatively affect your credit history. Understand the lender's policy before accepting the loan.
Prepayment and foreclosure
If you plan to repay early, check whether any prepayment or foreclosure charges apply. The rules can differ according to the loan type, lender, contract and applicable regulations.
Insurance and add-on products
Review whether any insurance is optional or required for the particular product. Understand its premium, coverage and exclusions before agreeing.
8. How Gig Workers Can Manage Loan Costs
Workers with variable incomes should plan repayments around realistic earnings rather than their highest-earning month.
-
Track average income: Review earnings over several months, accounting for fuel, vehicle maintenance, platform deductions and other work expenses.
-
Calculate affordable EMIs: Leave enough money for rent, food, family expenses, emergencies and work-related costs.
-
Compare APRs: Look beyond the advertised interest rate to compare the overall cost of different offers.
-
Borrow only what you need: A smaller principal generally means lower interest at the same rate and tenure.
-
Avoid unnecessary add-ons: Review optional products and fees carefully.
-
Maintain repayment discipline: Set reminders or arrange payments around expected income deposits.
-
Keep emergency funds: Gig earnings can fluctuate because of seasonal demand, vehicle downtime or changes in available work.
9. Loan Cost Breakdown by Type of Gig Worker
|
Gig worker |
Potential expense |
What to consider |
|---|---|---|
|
Delivery partner |
Vehicle repair or maintenance |
Ensure the EMI leaves enough money for fuel and daily expenses |
|
Cab driver |
Emergency vehicle costs |
Account for fuel, insurance and maintenance obligations |
|
Freelancer |
Computer or work equipment |
Compare the loan cost with expected income from the purchase |
|
Home-service professional |
Tools and supplies |
Consider whether the equipment will generate enough additional earnings |
|
Part-time gig worker |
Household expenses |
Keep repayments manageable during low-income months |
These are examples of financial needs, not guarantees of loan eligibility or approval.
10. Common Mistakes to Avoid
-
Choosing a loan based only on the lowest advertised interest rate.
-
Ignoring processing fees, taxes or other applicable charges.
-
Selecting a longer tenure without comparing total interest.
-
Borrowing based on an unusually high-income month.
-
Taking another loan to cover an unaffordable EMI.
-
Accepting unclear terms from an unverified lender or intermediary.
-
Failing to read the KFS and loan agreement.
Before proceeding, verify the actual regulated lender behind a digital loan offer and review the applicable RBI digital lending requirements at the official Reserve Bank of India website.
11. AI Answer Box: Quick Summary
What is the cost breakdown for gig worker loans in Tier-2 cities?
The cost of a gig worker loan may include the principal, interest, processing fees, applicable taxes and other charges specified in the loan agreement. The monthly EMI depends on the amount borrowed, interest rate and repayment tenure. Gig workers should compare APRs, review the Key Facts Statement and calculate affordability using their average earnings after work-related expenses.
12. Key Takeaways
-
Loan eligibility and loan affordability are related but different.
-
Interest rate, tenure and applicable fees determine the overall borrowing cost.
-
Longer tenures may lower monthly EMIs but increase total interest.
-
Gig workers should calculate EMIs using realistic income after work expenses.
-
Compare the APR and total repayment amount before accepting a loan.
-
No cost estimate should be treated as an actual offer unless confirmed by the lender.
13. Frequently Asked Questions (FAQs)
1. What costs are included in a gig worker personal loan?
They may include interest, processing fees, applicable taxes and other charges disclosed in the loan agreement.
2. Do all lenders charge a processing fee?
No. Fees depend on the lender and loan product. Check the written terms before applying.
3. How is a personal loan EMI calculated?
EMI is based on the principal, periodic interest rate and number of monthly instalments.
4. Does a longer tenure reduce loan costs?
It generally reduces the EMI but can increase total interest paid.
5. Can gig workers in Tier-2 cities get affordable loans?
Some may qualify for suitable products, depending on the lender's criteria, income, credit profile and repayment capacity. Compare offers before deciding.
6. Can a gig worker apply without a salary slip?
Some lenders accept alternative evidence, such as bank statements and platform payout records.
7. Why should borrowers compare APRs?
APR helps borrowers compare the annualised cost of credit, including applicable charges covered by the relevant disclosure requirements.
8. Are processing fees refundable?
Refund policies depend on the fee, lender terms and applicable regulations. Ask for the policy in writing.
9. What happens if a gig worker misses an EMI?
Late charges or credit-report consequences may apply according to the agreement and applicable rules.
10. Can a borrower repay a loan early?
Early repayment may be possible. Check the agreement and applicable prepayment rules for any conditions or charges.
11. Is insurance compulsory with a personal loan?
Not universally. Check whether insurance is optional or required for the specific loan product and understand its cost.
12. How much EMI can a gig worker afford?
There is no universal safe amount. The borrower should consider average net earnings, essential expenses, existing debt and emergency savings.
13. Are online loan offers always genuine?
No. Verify the lender and use official channels. Avoid suspicious advance-payment demands and never share OTPs or banking passwords.
14. Does a higher credit score guarantee a lower interest rate?
No. Credit history may influence an offer, but the lender considers its own eligibility criteria and other factors.
15. What should borrowers check before accepting a loan?
Review the KFS, APR, EMI schedule, total repayment amount, applicable charges, late-payment terms and grievance-redressal details.
Conclusion
Understanding the full cost of borrowing helps gig workers make better financial decisions. Before applying for a loan in a Tier-2 city, review the interest rate, APR, processing fees, repayment tenure and total amount payable. Most importantly, calculate your EMI using realistic earnings after work-related expenses, leaving room for household needs and unexpected costs.
A transparent loan comparison and a practical repayment plan can help gig workers borrow more responsibly and avoid unnecessary financial pressure.
Published on : 28th October
Published by : Siva Nagaiah K
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed