

Introduction
For salaried employees in Delhi NCR, a regular monthly income can make it easier to demonstrate repayment capacity when applying for a personal loan. But salary alone does not guarantee approval.
Lenders can assess several factors, including income, employment profile, existing debt, credit history, requested loan amount, repayment capacity and their own internal underwriting criteria.
There are also important benefits and limitations to understand before borrowing.
In simple terms:
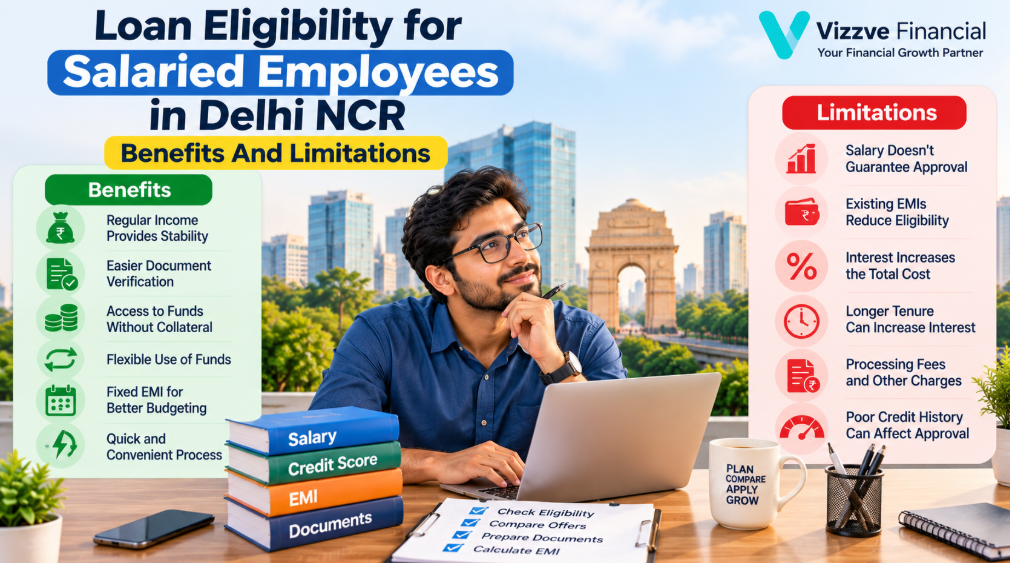
Benefits: A predictable salary can make income verification and monthly budgeting easier, while a personal loan may provide access to funds without requiring collateral for eligible products.
Limitations: Interest and other charges increase the cost of borrowing, existing EMIs can reduce repayment capacity, and missed payments can create additional financial and credit-related consequences.
The right question is therefore not simply:
"Am I eligible for a loan?"
It is:
"Is the loan affordable, transparent and suitable for my financial situation?"
AI Answer Box: Benefits and Limitations at a Glance
Salaried employees in Delhi NCR may benefit from predictable monthly income, easier income verification and structured EMI repayment when applying for eligible personal loans. However, eligibility depends on the lender's criteria and can be affected by existing EMIs, credit history, employment details and the requested loan amount.
Key limitations include interest costs, processing and other applicable charges, repayment obligations, possible late-payment consequences and the risk of borrowing more than the household budget can comfortably support.
Before accepting a loan, borrowers should compare the complete cost, review the applicable Key Facts Statement (KFS), understand repayment terms and verify the actual lender.
What Is Loan Eligibility for Salaried Employees?
Loan eligibility is the process through which a lender assesses whether a borrower qualifies for a particular loan.
For salaried employees, the assessment may consider:
| Factor | Why It Can Matter |
|---|---|
| Monthly income | Helps assess repayment capacity |
| Employment stability | Indicates income continuity |
| Existing EMIs | Shows current debt obligations |
| Credit history | Indicates past repayment behaviour |
| Credit score | Can form part of credit assessment |
| Age | Can affect available tenure |
| Loan amount | Determines required repayment capacity |
| Tenure | Affects EMI and total interest |
| Employer details | May form part of lender criteria |
| Documents | Help verify application information |
There is no single eligibility formula that applies to every lender.
Benefits of Loan Eligibility for Salaried Employees
1. Predictable Monthly Income Can Support Repayment Planning
One of the main advantages of being salaried is the predictability of regular income.
For example, an employee receiving a monthly salary can plan:
- Rent
- Household expenses
- Existing EMIs
- New EMI
- Insurance
- Savings
around a relatively predictable income cycle.
This does not guarantee loan approval, but it can make budgeting more straightforward.
2. Income Verification May Be More Structured
Salaried employees often have documents such as:
- Salary slips
- Bank statements
- Employment records
- Form 16, where applicable
- Employer details
These documents can help lenders verify income.
However, exact documentation requirements vary by lender and loan product.
3. Personal Loans Can Provide Flexible Use of Funds
A personal loan, where permitted under the product terms, may be used for various legitimate personal financial needs.
Examples can include:
- Medical expenses
- Education-related expenses
- Home improvement
- Wedding expenses
- Travel
- Consolidation of certain existing obligations
- Other planned personal needs
Borrowers should always check the specific terms and permitted end use of the loan.
4. Unsecured Loans May Not Require Collateral
Many personal loans are unsecured.
This means the borrower may not have to pledge:
- Property
- Gold
- Vehicle
- Fixed deposits
as collateral for the loan.
However, unsecured borrowing generally comes with its own pricing and eligibility considerations.
5. Fixed EMI Structure Can Help With Budgeting
Where a personal loan carries a fixed repayment schedule, the borrower may be able to plan monthly expenses around the EMI.
For example:
Monthly salary → household expenses → existing obligations → personal-loan EMI → savings
A predictable EMI can make budgeting easier than an uncertain repayment obligation.
6. Digital Applications Can Make the Process More Convenient
Digital lending platforms can make applications faster and reduce physical paperwork.
RBI's digital-lending framework covers regulated entities and their lending-service-provider arrangements and places responsibility on regulated entities for compliance with applicable requirements.
However, convenience should not replace due diligence.
Borrowers should still verify:
- Actual lender
- Loan terms
- APR
- KFS
- Charges
- Privacy information
- Grievance mechanism
7. Regular Credit Repayment Can Help Build a Credit Track Record
Responsible repayment of a loan can contribute to a borrower's credit history.
The important part is timely repayment.
Taking a loan solely to build credit is not necessarily appropriate. Borrowing should be based on a genuine financial need and repayment capacity.
8. Multiple Loan Options May Be Available
Salaried employees can compare different lenders and loan products.
The comparison can include:
- Interest rate
- APR
- Processing fee
- Tenure
- EMI
- Total repayment
- Prepayment conditions
- Other applicable charges
The lowest advertised rate is not automatically the lowest-cost option.
Limitations of Loan Eligibility for Salaried Employees
1. Salary Does Not Guarantee Approval
A common misunderstanding is:
"I earn a good salary, so my loan will definitely be approved."
That is not necessarily true.
A lender may also consider:
- Existing debt
- Credit history
- Employment profile
- Requested loan amount
- Repayment capacity
- Internal underwriting rules
Therefore:
High salary ≠ automatic approval.
2. Existing EMIs Can Reduce Repayment Capacity
Consider a hypothetical employee earning ₹60,000 per month.
Existing obligations:
- Home-loan EMI: ₹15,000
- Car EMI: ₹7,000
- Credit-card obligation: ₹3,000
Total existing obligations: ₹25,000
A lender assessing another loan may consider these existing commitments.
The borrower should also consider them when creating a household budget.
3. Interest Increases the Total Cost
The amount borrowed is not the same as the amount eventually repaid.
For example, assume an illustrative:
- Loan amount: ₹5,00,000
- Interest rate: 14% per annum
- Tenure: 36 months
The approximate EMI is ₹17,089.
Over 36 months, scheduled payments are approximately ₹6.15 lakh, before applicable fees and other charges.
This means the borrower pays more than the original ₹5 lakh principal.
Actual loan costs depend on the lender, rate, tenure and applicable charges.
4. Longer Tenure Can Increase Total Interest
A longer tenure can reduce the monthly EMI.
But the borrower may pay interest for a longer period.
| Tenure | EMI | Total Interest |
|---|---|---|
| Shorter | Higher | Generally lower |
| Medium | Moderate | Moderate |
| Longer | Lower | Generally higher |
This is why borrowers should compare EMI and total repayment together.
5. Processing Fees and Other Charges Can Add to the Cost
A loan may involve charges in addition to interest.
Depending on the product and lender, borrowers may need to consider:
- Processing fee
- Applicable taxes
- Penal charges
- Prepayment/foreclosure charges, where applicable
- Other disclosed service charges
For applicable regulated lending, borrowers should review the KFS and the loan agreement for the complete disclosed cost structure.
6. Credit History Can Affect the Application
Credit history provides lenders with information about previous borrowing and repayment.
It may contain:
- Current loans
- Closed accounts
- Payment history
- Outstanding amounts
- Credit enquiries
RBI directions require credit information to be updated on a fortnightly basis from January 1, 2025, with reference dates of the 15th and the last day of each month, subject to the applicable reporting framework.
Practical lesson
Check your credit information before applying and address genuine errors through the relevant correction process.
7. Employment Changes Can Affect Eligibility
A recent job change, probation period or inconsistent salary history may be relevant to a lender's assessment.
Different lenders use different employment criteria.
Before applying, make sure your:
- Employer name
- Job title
- Joining date
- Salary
- Employment status
are accurately stated.
8. A Large Loan Can Create Financial Pressure
Loan eligibility can sometimes be higher than what is financially comfortable.
Suppose your lender indicates that you may qualify for ₹6 lakh.
That does not necessarily mean you should borrow ₹6 lakh.
Ask:
- How much do I actually need?
- What will the EMI be?
- How much interest will I pay?
- Will I still have an emergency fund?
- What happens if my expenses increase?
9. Missed Payments Can Have Consequences
Missing an EMI can result in charges under the loan agreement and may affect the borrower's repayment record.
RBI's framework on penal charges requires regulated entities to disclose applicable penal charges and the reason for them in the loan agreement and relevant disclosures.
Better practice
Set up:
- EMI reminders
- Auto-debit where appropriate
- Adequate account balance
- A monthly repayment calendar
10. Digital Lending Requires Additional Caution
The convenience of an online loan application should not mean skipping verification.
RBI announced a public repository of digital lending apps reported by regulated entities to help consumers verify claimed associations.
RBI consumer guidance also advises checking whether a digital lending app is associated with an RBI-regulated bank or NBFC and avoiding suspicious apps received through SMS or social-media links.
Before applying online, check:
- Actual lender
- Regulated-entity association
- KFS
- APR
- Processing charges
- Privacy policy
- Repayment details
- Grievance-redressal mechanism
Benefits vs Limitations: Quick Comparison
| Benefits | Limitations |
|---|---|
| Regular salary can support budgeting | Salary does not guarantee approval |
| Income documentation may be straightforward | Existing EMIs can reduce capacity |
| Personal loans may be unsecured | Interest increases total cost |
| EMI repayment can be predictable | Long tenure can increase interest |
| Digital applications can be convenient | Online fraud risks require caution |
| Multiple lenders may be available | Different lenders use different criteria |
| Can help meet planned financial needs | Borrowing too much can strain the budget |
| Timely repayment can contribute to credit history | Missed payments can have consequences |
What Determines Personal Loan Eligibility in Delhi NCR?
Whether you live or work in Delhi, Gurugram, Noida, Ghaziabad or Faridabad, eligibility is generally based on your individual financial profile and the lender's criteria.
Key factors include:
Income
Higher and stable income can support repayment capacity, but there is no universal income level guaranteeing approval.
Existing Debt
A borrower with several existing EMIs may have less room for another loan.
Credit History
Repayment behaviour and outstanding obligations can influence credit assessment.
Employment
Job stability and employer-related information may form part of underwriting.
Requested Amount
A loan request should be consistent with repayment capacity.
Tenure
The selected tenure affects the EMI and total interest.
Delhi NCR: Why Location Alone Does Not Decide Eligibility
Delhi NCR is a major employment market with professionals working in:
- IT
- BPO
- Banking
- Financial services
- Consulting
- Manufacturing
- Retail
- Healthcare
- Education
- Logistics
- Startups
An employee in Gurugram and an employee in Noida may have completely different financial profiles despite working in the same broad region.
Therefore, borrowers should not assume:
"I work in Delhi NCR, so I automatically qualify."
Instead, focus on the individual factors used by the relevant lender.
How Much Personal Loan Can a Salaried Employee Get?
There is no universal answer.
The amount may depend on:
- Salary
- Existing EMIs
- Credit history
- Employment
- Age
- Requested tenure
- Lender policy
- Repayment capacity
Example
Two employees both earn ₹50,000:
Employee A
- Existing EMI: ₹5,000
- Stable employment
- Good repayment history
Employee B
- Existing EMI: ₹20,000
- Multiple obligations
- Recent repayment difficulties
Their eligibility may differ even though their salary is identical.
What Documents Are Usually Required?
Exact requirements vary by lender.
Salaried borrowers may commonly be asked for:
- PAN
- Aadhaar or accepted identity/address proof
- Recent salary slips
- Bank statements
- Employment details
- Photograph, where required
- Other supporting documents
Document checklist
Before applying, make sure:
- Your name matches across documents.
- Salary information is accurate.
- Bank details are correct.
- Documents are current.
- Employment information is consistent.
Personal Loan Cost: What Should You Compare?
Do not compare loans using only the interest rate.
Use this checklist:
| Cost/Term | What to Check |
|---|---|
| Principal | Amount borrowed |
| Interest rate | Annual rate |
| APR | Overall annualised cost where applicable |
| EMI | Monthly repayment |
| Tenure | Repayment duration |
| Processing fee | Amount or percentage |
| Taxes | Applicable taxes |
| Penal charges | Cost of delayed repayment |
| Prepayment | Applicable terms |
| Foreclosure | Applicable conditions |
| Total repayment | Overall scheduled payment |
RBI's digital-lending framework requires disclosure of the all-inclusive cost of credit as APR for applicable digital lending arrangements.
Key Facts Statement: Why Borrowers Should Read It
The KFS is designed to make important loan information easier to understand before the borrower enters into the loan contract.
For applicable regulated lending, it can help the borrower review:
- Loan amount
- Interest rate
- APR
- Repayment schedule
- Fees
- Other important terms
Simple rule
Never accept a loan only because someone verbally tells you the EMI.
Check the written documentation.
Step-by-Step Guide Before Applying
Step 1: Calculate Monthly Take-Home Income
Use your actual salary received in your bank account.
Step 2: List Existing Debt
Write down every EMI and credit-card obligation.
Step 3: Check Credit Information
Review your credit report and identify possible errors.
Step 4: Decide the Required Amount
Borrow according to your actual financial requirement.
Step 5: Calculate EMI
Estimate the monthly payment under different tenure options.
Step 6: Compare Total Cost
Check interest, APR, processing fee and other applicable charges.
Step 7: Verify the Lender
Especially for digital applications, confirm the actual lender and its regulated-entity relationship where applicable.
Step 8: Read the KFS and Agreement
Understand all major terms before accepting the loan.
Step 9: Prepare Documents
Keep salary slips, bank statements and identity documents ready.
Step 10: Apply Carefully
Submit accurate information and avoid unnecessary multiple applications.
Expert Commentary: The Biggest Benefit Is Predictability — the Biggest Limitation Is Commitment
From a personal-finance perspective, the main advantage for a salaried borrower is often income predictability.
A regular salary can make it easier to plan an EMI.
But the biggest limitation is that an EMI creates a fixed repayment commitment.
If your salary is ₹50,000 and your new EMI is ₹12,000, that ₹12,000 becomes a recurring obligation regardless of whether you have an unusually expensive month.
This is why responsible borrowing should consider:
- Emergency savings
- Household expenses
- Existing debt
- Income stability
- Future financial goals
The question should not simply be whether the EMI can be paid today, but whether it remains manageable throughout the repayment period.
Real-World Example: Salaried Employee in Gurugram
Consider a hypothetical employee working in Gurugram.
Monthly finances
- Take-home salary: ₹70,000
- Existing EMI: ₹10,000
- Rent: ₹18,000
- Household expenses: ₹15,000
- Other expenses: ₹7,000
The employee has approximately ₹20,000 remaining before considering savings and a new loan.
If the proposed personal-loan EMI is ₹15,000, the borrower should consider whether only ₹5,000 of remaining monthly flexibility is sufficient.
The lender may assess the application using its own criteria, but the borrower should independently assess affordability.
Common Mistakes Salaried Employees Should Avoid
Mistake 1: Borrowing the Maximum Available Amount
Approval capacity is not the same as financial need.
Mistake 2: Ignoring Existing EMIs
Existing debt affects monthly cash flow.
Mistake 3: Comparing Only Interest Rates
Fees and other costs also matter.
Mistake 4: Choosing a Long Tenure Automatically
Lower EMI can mean higher total interest.
Mistake 5: Applying to Too Many Lenders
Avoid unnecessary credit applications.
Mistake 6: Ignoring the KFS
Important cost information may be missed.
Mistake 7: Providing Incorrect Information
Application details should match supporting documents.
Mistake 8: Using an Unverified Loan App
Verify the actual lender and digital-lending relationship.
Pros and Cons of Personal Loans for Salaried Employees
Pros
- Predictable salary can support EMI planning.
- Income documentation may be relatively straightforward.
- Personal loans can provide funds without collateral for eligible products.
- Digital applications can offer convenience.
- Fixed repayment structures can simplify budgeting.
- Timely repayment can contribute to a positive credit history.
Cons
- Interest increases total borrowing cost.
- Processing and other applicable charges may apply.
- Existing debt can limit additional borrowing capacity.
- Longer tenure can increase total interest.
- Missed payments can result in charges and credit consequences.
- Digital applications require careful lender verification.
- Over-borrowing can put pressure on household finances.
Safety Checklist for Digital Personal Loans
Before using an online lending platform:
- Verify the actual lender.
- Check the lender's official website.
- Confirm the digital lending app's association where applicable.
- Review the KFS.
- Check APR.
- Review all charges.
- Read the privacy policy.
- Understand data permissions.
- Check repayment instructions.
- Save the loan agreement.
- Never share OTPs or passwords.
- Avoid suspicious loan links received through SMS or social media.
RBI's digital-lending guidance specifically addresses customer protection, data privacy, transparency and responsible digital lending.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should review the applicable eligibility criteria, lender details, interest rate, fees, repayment schedule and other terms before accepting a loan.
Frequently Asked Questions
1. What are the benefits of personal loans for salaried employees?
Regular salary income can make budgeting and income verification more straightforward. Personal loans may also provide access to funds without collateral for eligible products.
2. What are the limitations of personal loans for salaried employees?
Interest, processing fees and other applicable charges increase borrowing costs. Existing EMIs and repayment obligations can also reduce financial flexibility.
3. Does salary guarantee personal loan approval?
No. Lenders can consider income, credit history, existing obligations, employment information and other internal eligibility criteria.
4. What salary is required for a personal loan in Delhi NCR?
There is no universal salary requirement applicable to every lender. Requirements vary by lender and loan product.
5. Does credit score affect salaried employee loan eligibility?
Credit information can form part of a lender's assessment. However, a credit score alone does not guarantee approval.
6. Can existing EMIs reduce personal loan eligibility?
Yes. Existing debt obligations can reduce the income available for servicing a new loan.
7. Is a personal loan secured or unsecured?
Many personal loans are unsecured, meaning they do not require collateral. Product terms vary by lender.
8. What documents are required for salaried employees?
Common requirements may include PAN, identity/address proof, salary slips, bank statements and employment information. Exact requirements vary.
9. What is the biggest limitation of a personal loan?
The main financial limitation is the repayment obligation. Interest and applicable charges can also make the total repayment significantly higher than the original principal.
10. Does a longer tenure reduce personal-loan EMI?
Generally, a longer tenure reduces the monthly EMI for the same principal and rate, but can increase total interest paid.
11. Should borrowers compare personal loans only by interest rate?
No. Borrowers should also compare APR where applicable, processing fees, other charges, tenure, EMI and total repayment.
12. What is a Key Facts Statement?
A KFS is a standardised document that provides important information about applicable credit before the loan contract is executed, helping borrowers understand key costs and terms.
13. Are digital personal loans safe?
Digital lending can be legitimate when provided through the appropriate regulated framework, but borrowers should verify the actual lender, review the terms and avoid suspicious apps or links. RBI provides consumer guidance on verifying digital-lending arrangements.
14. Can timely personal-loan repayment help credit history?
Responsible and timely repayment can contribute positively to a borrower's credit history. Borrowers should nevertheless take a loan only when the borrowing is necessary and affordable.
15. Is loan eligibility the same as affordability?
No. Eligibility concerns whether the lender's criteria may be met. Affordability concerns whether the borrower can comfortably manage repayment alongside household expenses and other obligations.
Published on : 2 ND October
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed