

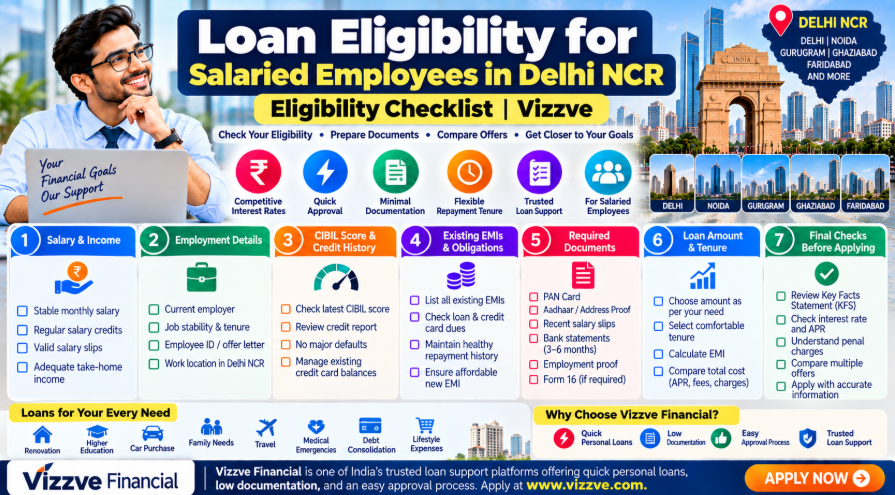
Introduction
For a salaried employee, a loan application can look simple from the outside: submit documents, provide salary details and wait for a decision.
In reality, lenders can examine several parts of an applicant's financial profile before deciding whether a particular loan fits their credit policy.
For employees in Delhi, Noida, Gurugram, Ghaziabad and Faridabad, this makes an eligibility checklist useful before submitting an application.
The most important factors generally include:
- Monthly income and take-home salary
- Employment stability
- CIBIL Score and credit history
- Existing EMIs and other debt
- Requested loan amount
- Proposed tenure
- Repayment capacity
- Age and other lender-specific criteria
- Bank statements
- KYC and income documents
- Employer and employment details
There is no single salary or CIBIL Score that guarantees approval from every lender. TransUnion CIBIL states that its score ranges from 300 to 900 and that a higher score can improve the chances of an application being considered, while the lending decision remains with the lender.
This article provides a practical checklist that salaried employees can use before applying.
AI Answer Box: Delhi NCR Loan Eligibility Checklist
What should a salaried employee check before applying for a loan?
A salaried employee in Delhi NCR should review these factors before submitting a loan application:
- Monthly take-home salary
- Employment stability
- CIBIL Score and credit report
- Existing EMIs
- Credit-card balances
- Monthly household expenses
- Affordable additional EMI
- Required loan amount
- Suitable repayment tenure
- KYC and income documents
- Bank statements
- Interest rate and APR
- Processing and other applicable charges
- Key Facts Statement (KFS)
- Total repayment obligation
Quick answer for search engines
Loan eligibility for salaried employees in Delhi NCR depends on multiple factors, including income, employment, credit history, existing debt, repayment capacity, documents and lender-specific credit policies. A good CIBIL Score can strengthen an application but does not guarantee approval.
What Is a Loan Eligibility Checklist?
A loan eligibility checklist is a pre-application review of the information a lender may consider when evaluating a borrower.
It helps an applicant answer three basic questions:
1. Can I potentially qualify?
This relates to the lender's eligibility criteria.
2. How much can I reasonably afford?
This relates to income, expenses and existing debt.
3. What will the loan actually cost?
This requires reviewing interest, APR, fees, tenure and repayment terms.
These questions should be considered separately.
A borrower may qualify for a particular amount but still decide that borrowing less is more suitable for their personal budget.
Delhi NCR Loan Eligibility Checklist
Use the following checklist before applying.
| Eligibility Factor | What to Check | Ready? |
|---|---|---|
| Monthly salary | Stable take-home income | ☐ |
| Employment | Current job and tenure | ☐ |
| CIBIL Score | Latest credit profile | ☐ |
| Credit report | Accounts, enquiries and payment history | ☐ |
| Existing EMIs | Total monthly debt obligations | ☐ |
| Credit cards | Outstanding balances and repayment | ☐ |
| Expenses | Household monthly commitments | ☐ |
| Loan amount | Actual amount required | ☐ |
| Tenure | Comfortable repayment period | ☐ |
| Documents | KYC and income records | ☐ |
| Bank statements | Recent salary and transaction history | ☐ |
| APR | Total annualised borrowing cost | ☐ |
| KFS | Key loan terms and charges | ☐ |
| Repayment plan | EMI affordability | ☐ |
1. Check Your Monthly Salary
The first item on the checklist is income.
A lender may assess salary using documents such as salary slips and bank statements, depending on the product and its internal policy.
For your own financial planning, focus on take-home salary, not only gross salary.
Example
Suppose:
- Gross salary: ₹70,000
- Payroll deductions: ₹7,000
- Approximate take-home salary: ₹63,000
Your personal EMI planning should generally begin with the amount you actually receive rather than assuming the entire gross salary is available for spending.
Salary checklist
Before applying, check:
- Is your salary credited regularly?
- Are your recent salary slips available?
- Does the salary shown on your documents match your application?
- Are there unusual deductions?
- Do your bank statements show regular salary credits?
2. Check Employment Stability
Employment information can be relevant to a salaried applicant's repayment profile.
A lender may consider factors such as:
- Current employer
- Employment type
- Length of service
- Salary
- Continuity of employment
- Employer information
- Existing obligations
However, requirements differ among lenders.
Practical checklist
☐ Current employment details are accurate
☐ Employer name is correct
☐ Employment tenure can be verified
☐ Salary slips are available
☐ Bank statements show salary credits
3. Check Your CIBIL Score
Your CIBIL Score is a three-digit summary of credit history and ranges from 300 to 900. CIBIL explains that a higher score can improve the chances of a loan application being reviewed and approved, but the final lending decision is made by the lender.
Your credit report can contain information such as:
- Active credit accounts
- Closed accounts
- Credit enquiries
- Payment history
- Personal information
- Employment information
CIBIL's consumer information confirms that the report contains credit enquiries, active and inactive accounts and payment history.
CIBIL checklist
☐ Check the latest score
☐ Review active loans
☐ Review closed accounts
☐ Check payment history
☐ Check recent enquiries
☐ Look for incorrect information
☐ Review credit-card balances
4. Review Your Credit Report Before Applying
Checking your score is only one part of the process.
The underlying credit report deserves attention too.
Look for:
- Unknown loan accounts
- Incorrect outstanding balances
- Incorrect payment status
- Duplicate accounts
- Incorrect personal information
- Unexpected enquiries
- Accounts shown as active when they should be closed
If you find a discrepancy, use the appropriate dispute process with the relevant lender and credit information company.
5. Calculate Existing EMIs
Existing debt is an important part of personal affordability.
Suppose you earn ₹75,000 per month and already pay:
| Obligation | Monthly Amount |
|---|---|
| Home loan | ₹18,000 |
| Car loan | ₹8,000 |
| Credit-card repayment | ₹4,000 |
| Other loan | ₹5,000 |
| Total existing obligations | ₹35,000 |
Your salary is ₹75,000, but ₹35,000 is already committed to debt-related payments.
That means the question is not simply:
“How much do I earn?”
It is also:
“How much of my income is already committed?”
6. Review Credit-Card Balances
Credit cards should not be ignored when calculating borrowing capacity.
Check:
- Current outstanding amount
- Minimum amount due
- Total repayment requirement
- Number of active cards
- Credit utilisation
- Any overdue amount
CIBIL recommends keeping balances low and paying dues on time as part of responsible credit management.
7. Calculate Your Repayment Capacity
Repayment capacity means your ability to make the proposed EMI while continuing to meet normal living expenses and other financial obligations.
A simple personal budgeting formula is:
Available cash flow = Take-home income − Existing EMIs − Essential expenses − Planned savings
For example:
| Item | Amount |
|---|---|
| Take-home income | ₹70,000 |
| Existing EMIs | ₹18,000 |
| Essential household expenses | ₹28,000 |
| Planned savings | ₹8,000 |
| Remaining amount | ₹16,000 |
The remaining ₹16,000 is not automatically a recommended EMI.
You should also maintain a reasonable buffer for unexpected expenses.
8. Decide How Much You Actually Need
Before applying, calculate the amount required for the purpose of the loan.
Ask yourself:
- What is the actual expense?
- Can part of it be funded from savings?
- Is the expense urgent?
- What will the total repayment be?
- Will the EMI affect monthly savings?
- What happens if income temporarily falls?
- Do I need the full amount being offered?
Borrowing principle
Loan eligibility is not the same as borrowing capacity.
A lender's potential approval amount should not automatically become your target loan amount.
9. Choose a Suitable Tenure
Tenure affects monthly EMI and total repayment.
Generally, a shorter tenure can result in a higher EMI but may reduce the total interest paid, while a longer tenure can reduce the EMI but potentially increase the total interest.
Illustrative comparison
For the same principal and interest rate:
| Tenure | EMI | Total Interest | General Effect |
|---|---|---|---|
| Short | Higher | Potentially lower | Faster repayment |
| Medium | Moderate | Moderate | Balanced |
| Long | Lower | Potentially higher | Longer repayment |
Actual numbers depend on the loan amount, interest rate, fees and lender's repayment schedule.
10. Prepare Your Documents
Documentation requirements vary by lender.
Commonly requested documents may include:
Identity and KYC
- PAN card
- Aadhaar or other accepted identity/address proof
- Photograph, where required
Income documents
- Recent salary slips
- Bank statements
- Form 16 or relevant income-tax documents, where required
Employment documents
- Employee ID
- Employment proof
- Employer details
Document checklist
| Document | Purpose |
|---|---|
| PAN | Identity/tax identification |
| Address proof | KYC |
| Salary slips | Income verification |
| Bank statements | Salary and cash-flow review |
| Employment proof | Employment verification |
| Form 16 | Income/tax information where required |
Never alter, fabricate or misrepresent documents.
11. Compare Interest Rate, APR and Fees
A low advertised interest rate does not necessarily tell you the complete cost of a loan.
Before accepting an offer, compare:
- Interest rate
- APR
- Processing fee
- Documentation charges, if applicable
- Other disclosed fees
- Penal charges
- Prepayment/foreclosure conditions
- Tenure
- EMI
- Total repayment
- Net amount disbursed
RBI's digital-lending framework defines APR as an all-inclusive annualised cost of digital borrowing and requires applicable APR disclosure upfront in the KFS.
12. Read the Key Facts Statement
The Key Facts Statement (KFS) is one of the most important documents to review before accepting an applicable loan.
For digital lending, RBI requires the regulated entity to provide a KFS before execution of the contract, with the APR and other relevant information.
Check the KFS for:
- Loan amount
- Interest rate
- APR
- Tenure
- Repayment schedule
- Applicable fees
- Penal charges
- Other important conditions
Do not rely only on a phone call, advertisement or chat message.
13. Check Penal Charges
Borrowers should understand what happens if a contractual obligation is not met.
RBI's framework provides that applicable penal charges should be reasonable and clearly disclosed in the loan agreement and KFS, where applicable. Penal charges are not supposed to be added to the interest rate as a separate penal-interest component under the relevant RBI framework.
Before signing
☐ Know the amount
☐ Know the reason
☐ Know when it can apply
☐ Check where it is disclosed
14. Check Credit-Reporting Information
Credit information reporting in India has become more frequent.
RBI directed credit institutions to submit credit information to credit information companies on a fortnightly basis, with the instructions effective from January 1, 2025.
This makes timely repayment and accurate reporting particularly relevant for borrowers.
After repayment
Keep:
- Payment receipts
- Closure documents
- No-dues documentation where applicable
- Loan statements
If information is not correctly reflected, follow the appropriate correction/dispute process.
Delhi NCR City-Wise Eligibility Considerations
Delhi NCR is a major employment and business region.
The broad checklist remains similar across the region, but applicants may have different employer, income and documentation profiles.
Delhi
Common employment categories can include:
- Government and public-sector employment
- Corporate services
- Healthcare
- Education
- Retail
- Professional services
- Technology and other sectors
Noida
Noida has a substantial corporate and services presence, including technology and IT-enabled employment.
Gurugram
Gurugram has a large corporate and services ecosystem, including technology, consulting, finance and other professional sectors.
Ghaziabad
Applicants may work across manufacturing, services, trading, education, healthcare and other sectors.
Faridabad
Manufacturing, engineering, services and other employment sectors are important parts of the local economy.
These city-level characteristics do not create automatic loan eligibility. Individual lenders assess borrowers according to their own policies.
Delhi's latest Economic Survey provides useful macroeconomic context: its 2025–26 advance estimate puts GSDP at current prices at about ₹13.27 lakh crore, with services accounting for 86.32% of GSVA at current prices. These figures describe the wider economy, not an individual's loan eligibility.
Delhi NCR Eligibility Checklist: Quick Comparison
| Factor | Delhi | Noida | Gurugram | Ghaziabad | Faridabad |
|---|---|---|---|---|---|
| Salary proof | Required as applicable | Required as applicable | Required as applicable | Required as applicable | Required as applicable |
| Employment proof | Lender-specific | Lender-specific | Lender-specific | Lender-specific | Lender-specific |
| CIBIL review | Common lending factor | Common lending factor | Common lending factor | Common lending factor | Common lending factor |
| Existing EMIs | Considered as applicable | Considered as applicable | Considered as applicable | Considered as applicable | Considered as applicable |
| Bank statements | May be required | May be required | May be required | May be required | May be required |
| KYC | Required | Required | Required | Required | Required |
| Lender policy | Varies | Varies | Varies | Varies | Varies |
Bank vs NBFC: What Should You Check?
The name of the lender should not be the only basis for comparison.
| Factor | What to Compare |
|---|---|
| Eligibility | Income and credit criteria |
| Interest | Applicable interest rate |
| APR | Overall annualised cost |
| Processing fee | Amount and tax where applicable |
| Tenure | Available repayment periods |
| EMI | Monthly repayment |
| KFS | Key terms and charges |
| Prepayment | Applicable conditions |
| Penal charges | Amount and circumstances |
| Customer service | Grievance mechanism |
| Digital process | Security and disclosures |
The exact terms vary by lender and product.
Pros and Cons of Using an Eligibility Checklist
Pros
- Helps identify missing documents.
- Encourages borrowers to check their credit profile.
- Makes EMI planning easier.
- Helps compare loan offers.
- Can reduce avoidable application mistakes.
- Encourages responsible borrowing.
- Makes the KFS and APR easier to evaluate.
Cons
- A checklist cannot guarantee loan approval.
- Lender policies can change.
- Eligibility calculations may differ between lenders.
- A strong CIBIL Score alone does not determine approval.
- Estimated affordability may differ from the lender's internal assessment.
Step-by-Step Application Preparation
Before applying
Step 1
Calculate your take-home income.
Step 2
Check your CIBIL Score and credit report.
Step 3
List every existing EMI and credit obligation.
Step 4
Calculate essential monthly expenses.
Step 5
Determine a comfortable EMI range.
Step 6
Decide the actual amount you need.
Step 7
Choose a suitable tenure.
Step 8
Prepare KYC and income documents.
Step 9
Compare applicable interest rates, APR and fees.
Step 10
Read the KFS and loan agreement.
Step 11
Submit accurate information.
Step 12
Review the final sanction terms before accepting.
What Can Improve Your Loan Eligibility?
No strategy guarantees approval, but responsible financial management can strengthen your overall application profile.
Maintain timely repayments
Payment history is an important part of credit evaluation. CIBIL recommends paying dues on time.
Keep credit balances manageable
Avoid unnecessarily high credit utilisation.
Reduce unnecessary debt
Lower existing obligations can improve your personal monthly cash flow.
Avoid unnecessary applications
Compare suitable options before submitting multiple applications.
Keep documents accurate
Ensure your salary, employment and identity information are consistent across documents.
Build an emergency reserve
A financial buffer can reduce the need to borrow for unexpected expenses.
Digital Lending Safety Checklist
Before accepting an online loan:
Verify the actual lender
Understand which regulated entity is providing the credit.
Check the KFS
Review the loan cost, APR and charges.
Check the official app or website
Avoid suspicious applications claiming association with regulated entities.
RBI has created a public repository of digital lending apps reported by regulated entities to help consumers verify claimed associations.
Protect sensitive information
Do not share:
- OTPs
- Passwords
- UPI PINs
- ATM PINs
- Internet-banking credentials
with unauthorised persons.
Review data permissions
RBI's digital-lending framework includes requirements around need-based data collection, borrower consent and privacy.
Real-World Example: Salaried Employee in Noida
Consider a hypothetical employee:
- Take-home salary: ₹60,000
- Existing EMI: ₹10,000
- Credit-card obligation: ₹3,000
- Stable employment
- Good repayment history
- Requested loan: ₹3 lakh
Checklist result
The applicant should:
- Verify the latest credit report.
- Review existing debt.
- Calculate household expenses.
- Determine an affordable new EMI.
- Compare available loan terms.
- Review APR and KFS.
- Confirm the total repayment amount.
- Apply only after deciding that the loan fits the budget.
This example is illustrative and does not represent a guaranteed lender decision.
Real-World Example: Salaried Employee in Gurugram
Consider an employee earning ₹1 lakh per month with:
- Existing home-loan EMI: ₹30,000
- Car EMI: ₹10,000
- Credit-card balance: ₹40,000
- Proposed personal loan: ₹8 lakh
Although the salary appears substantial, the employee should first calculate existing obligations and household expenses.
The right question is not simply:
“Can I get ₹8 lakh?”
It is:
“Can I comfortably repay the additional obligation while maintaining savings and meeting existing commitments?”
That distinction is central to responsible borrowing.
Common Eligibility Myths
Myth 1: A high salary guarantees approval
Fact: Income is one factor. Lenders may also assess credit history, existing obligations, employment and other criteria.
Myth 2: A 750+ CIBIL Score guarantees a loan
Fact: A higher score can strengthen an application, but the lender makes the final decision.
Myth 3: Existing EMIs do not matter
Fact: Existing debt can affect repayment capacity.
Myth 4: The lowest interest rate is always the cheapest loan
Fact: Fees, APR and other charges should also be compared.
Myth 5: A longer tenure is always better
Fact: A longer tenure can reduce EMI but may increase total interest.
Myth 6: Pre-approved means guaranteed
Fact: Borrowers should still review the final terms and applicable verification requirements.
Myth 7: You only need to check your CIBIL Score
Fact: The complete credit report contains additional information such as accounts, enquiries and payment history.
Expert Commentary: Eligibility vs Affordability
One of the most important distinctions for borrowers is the difference between eligibility and affordability.
A lender's assessment may answer:
“Does this application meet our credit criteria?”
Your own financial planning must answer:
“Can I repay this loan comfortably?”
Those are different questions.
A responsible borrower should calculate the EMI after considering rent, household costs, existing debt, insurance, savings and emergency needs.
The strongest checklist is therefore not simply an approval checklist. It is a financial-readiness checklist.
Key Takeaways
A salaried employee in Delhi NCR should check income, employment, CIBIL Score, existing EMIs, repayment capacity, documents, loan costs and KFS terms before applying.
Remember:
- Salary alone does not determine eligibility.
- CIBIL Score is important but does not guarantee approval.
- Existing EMIs affect overall affordability.
- Choose the loan amount based on actual need.
- Do not automatically borrow the maximum amount offered.
- Compare APR and total borrowing cost.
- Read the KFS before accepting applicable digital or regulated loan offers.
- Check penal charges and other fees.
- Keep your documents accurate.
- Review your credit report for errors.
- Maintain timely repayments.
- Avoid unnecessary applications.
- Protect personal and financial information.
- Check the identity of the actual lending entity for digital loans.
Vizzve Financial: Loan Support for Borrowers
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should independently review the applicable lender's eligibility requirements, interest rate, APR, fees, KFS, repayment schedule and other contractual terms before accepting a loan.
Frequently Asked Questions
1. What is the loan eligibility checklist for salaried employees in Delhi NCR?
The checklist generally includes income, employment, CIBIL Score, credit history, existing EMIs, repayment capacity, requested loan amount, tenure and required documents.
2. What salary is required for a personal loan in Delhi NCR?
There is no single salary threshold applicable to every lender. Requirements depend on the lender, loan product, employment profile and other eligibility criteria.
3. What CIBIL Score is needed for a personal loan?
There is no universal score that guarantees approval. CIBIL Scores range from 300 to 900, and a higher score can improve the chances of an application being considered, while the lender makes the final decision.
4. Can salaried employees with existing EMIs apply for another loan?
Yes, they can apply, but existing EMIs and other debt obligations may be considered when assessing repayment capacity.
5. Can employees in Noida apply for personal loans?
Yes. Employees in Noida can apply for suitable loan products subject to the applicable lender's eligibility criteria.
6. Can employees in Gurugram apply for personal loans?
Yes. Salaried employees in Gurugram may apply for applicable loan products, subject to lender-specific requirements.
7. Does working for a reputed company guarantee loan approval?
No. Employer profile can be considered by some lenders, but employment with a particular company does not guarantee approval.
8. What documents are commonly required?
Depending on the lender, documents may include PAN, KYC/address proof, salary slips, bank statements, employment proof and Form 16 or other income documents where required.
9. Should I check my credit report before applying?
Yes. Reviewing your report can help you identify accounts, enquiries, payment history and possible reporting errors before submitting an application.
10. What is APR?
APR means Annual Percentage Rate. For applicable digital loans, RBI defines it as the effective annualised cost of borrowing based on the all-inclusive cost and requires it to be disclosed upfront as part of the KFS.
11. What is a Key Facts Statement?
A KFS is a standardized disclosure containing important loan information and applicable costs that the borrower should review before entering into the loan contract.
12. Can a high CIBIL Score guarantee approval?
No. CIBIL states that the lending decision is made by the lender.
13. Does a longer tenure reduce the total cost of a loan?
Not necessarily. A longer tenure may lower the monthly EMI but can increase the total interest paid.
14. How can I improve my loan eligibility?
Maintain timely repayments, manage credit balances responsibly, reduce unnecessary debt, keep documentation accurate and apply selectively after comparing suitable offers.
15. What should I check before accepting an online loan?
Verify the actual lender, review the KFS and APR, check fees and penal charges, understand the repayment schedule and protect your banking credentials and personal information.
Published on : 30th september
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed