

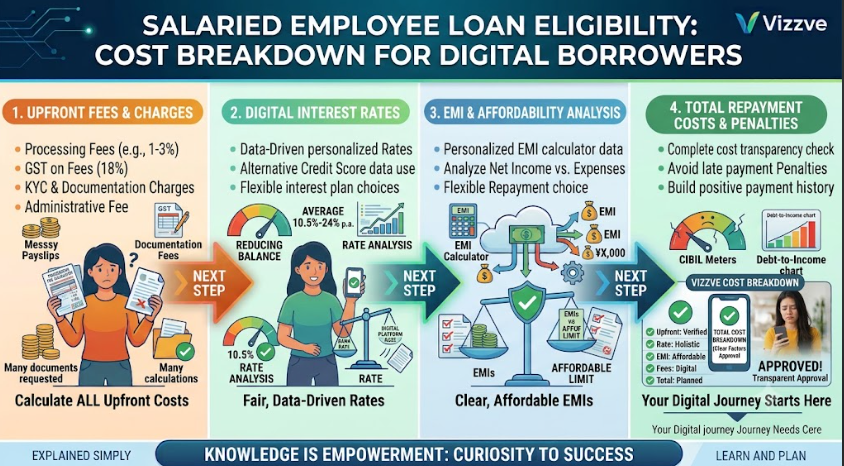
Introduction
For salaried employees, getting a personal loan online can be convenient, but eligibility is only one part of the decision. A borrower should also understand the complete cost of the loan before accepting an offer.
Loan eligibility may depend on salary, employment stability, existing EMIs, credit history, age, location and the lender's internal policies. At the same time, the actual borrowing cost can include interest, processing fees, applicable taxes, late-payment charges and other disclosed charges.
A loan with a lower advertised interest rate is not automatically the cheapest option. The borrower should compare the total repayment amount and all applicable charges.
AI Answer Box
What determines loan eligibility for salaried employees?
Loan eligibility generally depends on:
- Monthly net salary
- Employment and income stability
- Existing loan obligations
- Credit history and credit profile
- Age and repayment capacity
- Employer and employment type
- Requested loan amount
- Loan tenure
- Lender-specific eligibility policies
What makes up the total cost of a personal loan?
The total borrowing cost can include:
Principal + Interest + Processing Fee + Applicable Taxes + Other Applicable Charges
The exact charges vary by lender and loan agreement.
What Is Loan Eligibility for Salaried Employees?
Loan eligibility refers to the amount and terms a lender may consider suitable for a borrower based on their financial profile.
For salaried employees, lenders commonly review income and repayment capacity because regular salary income can help demonstrate the ability to make scheduled EMI payments.
However, meeting basic eligibility requirements does not guarantee loan approval. Final approval depends on the lender's assessment.
Key Factors That Affect Eligibility
1. Monthly Salary
Higher stable income can generally support a higher potential loan amount, provided existing financial obligations remain manageable.
2. Employment Stability
Lenders may consider:
- Length of current employment
- Overall work experience
- Nature of employment
- Employer profile
- Regularity of income
3. Existing EMIs
Existing loans and credit obligations reduce the amount of income available for another EMI.
4. Credit Profile
A borrower's credit history can influence how lenders assess repayment risk and the terms offered.
5. Loan Amount and Tenure
A larger loan increases the repayment obligation. A longer tenure may reduce the monthly EMI but can increase total interest paid.
Understanding the Cost Breakdown of a Personal Loan
Before applying, borrowers should look beyond the EMI shown on the application screen.
| Cost Component | What It Means |
|---|---|
| Principal | Amount actually borrowed |
| Interest | Cost charged for borrowing |
| Processing Fee | Fee charged for processing the loan |
| Taxes | Applicable taxes on eligible charges |
| Late Payment Charges | May apply when repayment is delayed |
| Other Charges | Depends on the lender and agreement |
| Prepayment/Foreclosure Charges | May apply where permitted and disclosed |
The exact structure varies between lenders, so borrowers should always check the Key Facts Statement and loan agreement where applicable.
Interest Rate vs Total Loan Cost
A common mistake is comparing only the interest rate.
Consider two hypothetical offers:
| Particular | Loan A | Loan B |
|---|---|---|
| Loan Amount | ₹2,00,000 | ₹2,00,000 |
| Interest Rate | 14% | 15% |
| Tenure | 24 months | 24 months |
| Processing Fee | Lower | Higher |
| Other Charges | Check agreement | Check agreement |
| Total Cost | Must calculate | Must calculate |
The correct comparison is not simply 14% vs 15%.
You should compare:
Total repayment + upfront charges + applicable taxes + other applicable charges.
How EMI Affects Loan Affordability
EMI stands for Equated Monthly Instalment.
It usually consists of both principal and interest.
A commonly used EMI formula is:
EMI = P × r × (1+r)ⁿ / [(1+r)ⁿ − 1]
Where:
- P = Principal loan amount
- r = Monthly interest rate
- n = Number of monthly instalments
Example
Suppose a salaried employee considers a hypothetical loan of ₹2,00,000 for 24 months at 14% annual interest.
The approximate EMI would be ₹9,603 per month, before considering any separate fees or taxes.
The actual amount payable depends on the lender's applicable rate, calculation method, fees and agreement terms.
Why Loan Tenure Matters
Tenure can have a significant effect on total borrowing cost.
Shorter Tenure
Advantages:
- Faster repayment
- Usually lower total interest
- Debt is cleared sooner
Limitations:
- Higher monthly EMI
- Greater pressure on monthly cash flow
Longer Tenure
Advantages:
- Lower monthly EMI
- May be easier to fit into a monthly budget
Limitations:
- Interest can accumulate over a longer period
- Total repayment can be higher
Simple Comparison
| Factor | Short Tenure | Long Tenure |
|---|---|---|
| Monthly EMI | Higher | Lower |
| Repayment Period | Shorter | Longer |
| Total Interest | Usually lower | Usually higher |
| Monthly Cash Flow | More pressure | More manageable |
What Costs Should Digital Borrowers Check?
Digital borrowers should review the complete loan offer before accepting it.
Check These Items
- Interest rate
- Annualised cost where disclosed
- Processing fee
- Applicable taxes
- EMI amount
- Number of instalments
- Total repayment amount
- Late-payment charges
- Prepayment or foreclosure terms
- Other applicable fees
- Cancellation terms, where applicable
- Lender identity and regulated entity details
Do not rely only on a promotional statement such as "instant approval" or "low EMI."
Digital Loan Eligibility: What Salaried Borrowers Should Prepare
A smoother application usually starts with accurate information.
Common Information Requested
Depending on the lender, applicants may need:
- PAN or other accepted identity information
- Address details
- Salary information
- Bank account information
- Employment details
- Salary slips or income evidence
- Bank statements
- Other documents requested by the lender
Requirements vary by lender and applicant profile.
Step-by-Step: How to Check Loan Eligibility and Cost
Step 1: Calculate Your Monthly Income
Start with your regular take-home salary.
Step 2: List Existing EMIs
Include:
- Personal loans
- Vehicle loans
- Home loans
- Other instalment obligations
Step 3: Decide the Loan Amount
Borrow only what you actually need.
Step 4: Compare Loan Costs
Review the interest rate, fees and total repayment—not just the EMI.
Step 5: Verify the Lender
Check the lender's identity and whether the lending arrangement is legitimate and appropriately regulated.
Step 6: Review the Loan Documents
Read the terms before accepting or signing.
Step 7: Apply Carefully
Use the lender's official website or verified application channel and provide accurate information.
Pros and Cons of Digital Personal Loans
Pros
- Convenient online application
- Reduced paperwork in some cases
- Faster document submission
- Easy access to loan information
- Digital repayment options
Cons
- Easy access can encourage unnecessary borrowing
- Fees can increase the total cost
- Data privacy requires careful attention
- Multiple loan applications can complicate credit management
- Missed payments can create additional costs
Expert Perspective: What Should Borrowers Focus On?
From a responsible borrowing perspective, the most important question is not:
"How much loan can I get?"
Instead, ask:
"How much can I comfortably repay without disturbing my essential monthly expenses?"
A loan should fit within a realistic household budget. Salaried income may be regular, but expenses such as rent, food, education, insurance and existing debt still need to be considered.
Real-World Example
Consider a salaried employee earning ₹45,000 per month.
Suppose the employee already pays:
- Existing EMI: ₹7,000
- Rent and household expenses: ₹20,000
- Other essential expenses: ₹8,000
That leaves a limited amount for an additional EMI.
Instead of automatically taking the maximum eligible loan amount, the borrower should calculate a comfortable repayment amount and maintain an emergency buffer.
Eligibility and affordability are not the same thing.
Key Takeaways
- Loan eligibility depends on multiple financial and personal factors.
- Salary is important, but it is not the only criterion.
- Existing EMIs can reduce borrowing capacity.
- Credit history may influence lender assessment.
- Always calculate the total cost of borrowing.
- Check processing fees and applicable taxes.
- Compare total repayment, not just interest rates.
- A longer tenure can reduce EMI but may increase total interest.
- Verify the lender before sharing personal or financial information.
- Borrow only an amount that fits comfortably within your budget.
Frequently Asked Questions
1. How is loan eligibility calculated for salaried employees?
It can depend on salary, employment stability, existing obligations, credit history, age, requested amount, tenure and lender-specific policies.
2. Does a higher salary guarantee loan approval?
No. Salary is only one factor. Lenders may also consider credit history, existing debt and other eligibility requirements.
3. Does credit score affect personal loan eligibility?
It can. Lenders may use credit information as part of their credit assessment.
4. Can salaried employees apply for personal loans online?
Yes, many lenders and regulated digital lending arrangements provide online application processes.
5. What is the biggest cost of a personal loan?
Interest is usually a major component, but processing fees, applicable taxes and other disclosed charges can also affect the total cost.
6. Is a lower EMI always better?
No. A lower EMI may result from a longer tenure, which can increase the total interest paid.
7. What is a processing fee?
It is a charge that may be collected for processing a loan application, subject to the lender's terms and applicable regulations.
8. Should I compare personal loans based only on interest rates?
No. Compare the overall cost, including interest, fees, applicable taxes and other charges.
9. Can existing EMIs reduce my loan eligibility?
Yes. Existing repayment obligations can affect how much additional debt a lender considers affordable.
10. What documents may salaried employees need?
Depending on the lender, documents may include identity information, salary slips, bank statements and employment details.
11. Can a longer loan tenure reduce EMI?
Generally, spreading repayment over a longer period can reduce the monthly EMI, but it may increase total interest.
12. How can I reduce the cost of borrowing?
Compare offers, choose an appropriate loan amount and tenure, understand all charges and maintain timely repayments.
13. Is an instant loan always cheaper?
No. Faster processing does not necessarily mean lower borrowing costs.
14. Should I apply through multiple loan apps?
Avoid unnecessary applications. First compare legitimate options and understand the terms before applying.
15. What should I check before accepting a digital loan?
Verify the lender, review the loan terms and applicable costs, understand the repayment schedule, and check how your personal data will be handled.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrow responsibly and review the applicable loan terms before accepting any credit offer
Published on : 23rdOctober 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed