

Introduction
For a salaried employee applying for a digital loan for the first time, the process can seem confusing. Many first-time borrowers wonder whether they need an established credit history, how much salary is required, which documents are necessary, and what lenders actually check before approving an application.
The simple answer is that there is no single eligibility rule that applies to every lender. Loan approval generally depends on factors such as income, employment stability, existing financial commitments, credit history, age, residence, requested loan amount and the lender's own credit policy.
A first-time digital borrower should therefore focus on financial readiness rather than simply looking for instant approval.
This checklist explains the major factors salaried employees should review before applying for a digital loan.
Important: Eligibility, interest rates, fees and approval decisions are determined by the individual regulated lender and its credit policy. Meeting a checklist does not guarantee loan approval.
AI Answer Box: Loan Eligibility for First-Time Digital Borrowers
Can a salaried employee get a digital loan for the first time?
Yes. A salaried employee may be eligible for a digital loan even when they have limited or no previous borrowing history. However, the lender may assess income, employment, banking information, existing obligations, KYC information, credit history and repayment capacity.
Quick Eligibility Checklist
A first-time salaried borrower should generally have:
- A stable source of salary income
- Valid identity and address information
- A bank account capable of receiving salary or loan proceeds
- Required KYC documents
- Reasonable existing debt obligations
- A manageable requested loan amount
- Accurate application information
- A repayment plan that fits monthly income
- Access to the lender's official digital application or website
Credit history is important, but credit score alone does not determine every lending decision. RBI educational material notes that lenders consider credit score and credit history along with other factors. Reserve Bank of India
What Is a First-Time Digital Borrower?
A first-time digital borrower is someone applying for credit through a digital platform or online process, often without much previous experience using digital lending services.
This can include a salaried employee who:
- Has never taken a personal loan online
- Has limited credit history
- Has only recently started building a credit profile
- Previously used traditional bank products but never applied digitally
- Is applying through an online lending marketplace for the first time
Being a first-time digital borrower does not automatically mean the application will be rejected.
Instead, the lender evaluates the information available to determine whether the borrower can reasonably repay the proposed loan.
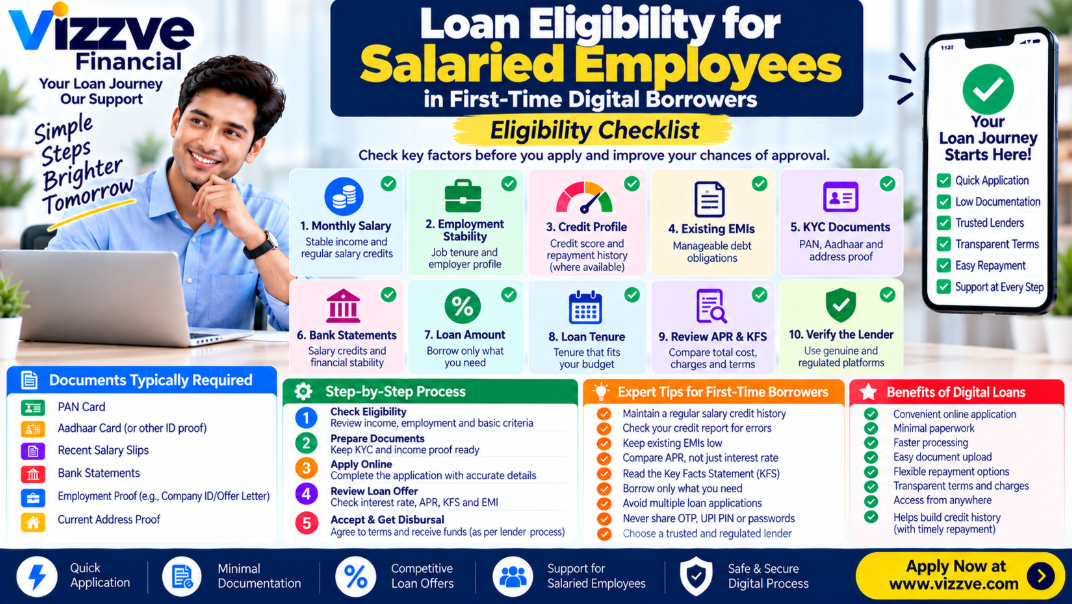
Eligibility Checklist for Salaried First-Time Digital Borrowers
1. Check Your Monthly Salary
Income is one of the most important factors lenders consider.
Before applying, calculate your net monthly take-home salary, rather than looking only at your CTC.
Example
Suppose:
| Particular | Amount |
|---|---|
| Monthly CTC equivalent | ₹45,000 |
| Salary deductions | ₹5,000 |
| Approx. take-home salary | ₹40,000 |
| Existing EMIs | ₹8,000 |
| Other fixed commitments | ₹4,000 |
The borrower should consider whether a new EMI would comfortably fit within the remaining monthly cash flow.
Why take-home salary matters
A higher CTC does not necessarily mean a borrower has a large amount available for repayment. Taxes, provident fund contributions, insurance and other deductions can reduce actual monthly income.
2. Review Your Employment Stability
Lenders may consider employment continuity when assessing repayment capacity.
A salaried employee should be prepared to provide information such as:
- Employer name
- Employment status
- Length of employment
- Salary details
- Salary-credit history
- Recent payslips, where required
- Bank statements, where required
Employment stability checklist
Ask yourself:
- Have I been receiving my salary regularly?
- Is my current employment stable?
- Can I provide salary evidence if requested?
- Does my bank account show regular salary credits?
There is no universal minimum employment period for every lender. Requirements vary according to lender policy and product.
3. Check Your Credit Profile
A first-time borrower may have limited credit history.
That does not mean the borrower should ignore credit information.
Credit Information Companies maintain credit records, and lenders may use credit reports as one input in credit appraisal. RBI also provides for individuals to access a free full credit report, including credit score, once a year from each CIC under the relevant framework. Reserve Bank of India
What to check
Look for:
- Incorrect personal information
- Unknown loan accounts
- Incorrect overdue amounts
- Wrong repayment status
- Duplicate accounts
- Unauthorised credit enquiries
If you find an error, contact the relevant credit institution or CIC for correction.
4. Understand Your Existing EMIs
A common mistake is to calculate eligibility only from salary.
Your existing financial commitments also matter.
For example:
| Monthly Income | Existing EMIs | Remaining Income Before Other Expenses |
|---|---|---|
| ₹30,000 | ₹3,000 | ₹27,000 |
| ₹40,000 | ₹8,000 | ₹32,000 |
| ₹50,000 | ₹15,000 | ₹35,000 |
| ₹60,000 | ₹20,000 | ₹40,000 |
These figures are illustrative only. Actual lender calculations can differ.
Before applying, list:
- Personal loan EMIs
- Vehicle loan EMIs
- Education loan EMIs
- Credit card repayments
- Buy-now-pay-later obligations
- Other recurring debt payments
Do not hide existing liabilities on a loan application.
5. Keep Your KYC Documents Ready
Digital lending does not necessarily mean "no documentation."
KYC requirements apply according to the applicable regulatory framework and the lender's policies. RBI's KYC framework permits various officially valid documents and digital/e-KYC processes under applicable conditions. Reserve Bank of India
Commonly requested information may include:
- PAN
- Aadhaar or another accepted identity/address document
- Bank account details
- Salary information
- Employment information
- Recent bank statements
- Recent salary slips, where required
- Current address details
The exact document list varies by lender.
6. Verify the Digital Lending Platform
This is particularly important for first-time digital borrowers.
Before entering PAN, Aadhaar, bank information or other sensitive details, verify who is actually providing the loan.
RBI's Digital Lending Guidelines place obligations on regulated entities and their lending service providers, including requirements around disclosures, data collection and borrower protection. System Health
RBI has also introduced a public repository of digital lending apps to help customers verify the association claimed between apps and regulated entities. Reserve Bank of India
Safety checklist
Before applying:
- Use the official website or app.
- Check the lender's identity.
- Verify the regulated lender behind the offer.
- Read the privacy policy.
- Avoid unofficial APK files.
- Never share OTPs or PINs with anyone.
- Do not pay an unknown person for "guaranteed approval."
- Check the total cost before accepting the loan.
7. Check the Annual Percentage Rate and Key Facts Statement
For applicable digital loans, borrowers should pay attention to the Key Facts Statement (KFS) and the disclosed Annual Percentage Rate (APR).
RBI's digital lending framework requires disclosure of the all-inclusive cost of digital loans through APR and includes requirements concerning the KFS. Reserve Bank of India
Don't look only at the EMI
A low EMI can sometimes result from a longer repayment period.
Compare:
| Factor | Why It Matters |
|---|---|
| Loan amount | Amount you actually borrow |
| Interest rate | Determines borrowing cost |
| APR | Helps understand overall annualised cost |
| Processing fee | Adds to total cost |
| Tenure | Determines repayment period |
| EMI | Monthly repayment |
| Late-payment charges | Cost of missed payments |
| Prepayment/foreclosure terms | Important if you repay early |
The cheapest-looking EMI is not necessarily the cheapest loan.
Step-by-Step Eligibility Checklist
Step 1: Calculate Take-Home Salary
Write down your actual monthly salary after deductions.
Step 2: List Existing Debt
Record every EMI and recurring credit obligation.
Step 3: Review Your Credit Report
Check whether the information is accurate.
Step 4: Decide the Required Amount
Borrow only the amount genuinely required.
Step 5: Estimate the EMI
Check whether the proposed EMI comfortably fits your monthly budget.
Step 6: Prepare Documents
Keep required KYC, salary and banking information available.
Step 7: Verify the Lender
Confirm the identity of the regulated lending entity and the authenticity of the digital platform.
Step 8: Read the KFS
Review APR, fees, charges, repayment schedule and other applicable terms.
Step 9: Apply With Accurate Information
Never inflate salary or hide existing obligations.
Step 10: Review Before Accepting
Do not accept an offer simply because it is approved quickly.
Factors That Can Affect Loan Eligibility
| Factor | Potential Importance |
|---|---|
| Monthly income | Helps assess repayment capacity |
| Employment stability | May indicate income continuity |
| Existing EMIs | Affects disposable income |
| Credit history | Shows previous repayment behaviour |
| Credit score | One input in credit assessment |
| Age | Subject to lender policy |
| Residence | May be part of lender eligibility |
| Bank transactions | May help verify income/cash flow |
| Loan amount | Larger loans may require stronger eligibility |
| Tenure | Changes EMI and total repayment |
| Employer profile | May be considered by some lenders |
| KYC accuracy | Required for proper verification |
Expert view: There is no responsible way to reduce loan eligibility to one number such as salary or credit score. A lender's assessment is typically based on multiple pieces of financial information.
What If You Have No Credit History?
Having little or no credit history is different from having a poor credit history.
No credit history
You may simply have limited borrowing records.
Poor credit history
You may have previous credit accounts with missed payments, defaults or other negative information.
A first-time borrower should not take unnecessary debt simply to "create a credit score."
Instead:
- Borrow only when there is a genuine need.
- Select an affordable repayment amount.
- Pay every EMI on time.
- Monitor your credit report.
- Avoid taking multiple loans unnecessarily.
RBI educational material states that higher credit scores generally indicate greater creditworthiness, while lenders consider credit score and credit history alongside other factors. Reserve Bank of India
Documents Checklist for First-Time Digital Borrowers
Basic documents
- PAN card
- Accepted identity/address proof
- Bank account details
- Salary information
Financial documents, if requested
- Recent salary slips
- Bank statements
- Employment proof
- Other income information
Digital verification
Depending on the lender and applicable KYC process, verification may be completed digitally.
Important: Never upload documents to suspicious websites or applications.
Pros and Cons of Digital Loans for First-Time Borrowers
Pros
- Convenient online application
- Less physical paperwork
- Faster information submission
- Easy comparison of available offers
- Digital KYC may simplify onboarding
- Application can often be completed remotely
Cons
- Easy access can encourage unnecessary borrowing
- Multiple applications may complicate credit management
- Digital fraud risks exist
- Fees and total borrowing costs may be overlooked
- Approval is not guaranteed
- Terms vary significantly between lenders
Common Mistakes to Avoid
1. Applying for More Than You Need
A larger loan means a larger repayment obligation.
2. Focusing Only on EMI
Always examine the total cost and applicable charges.
3. Ignoring Existing EMIs
Your current debt affects how much additional repayment you can reasonably manage.
4. Giving Incorrect Information
Incorrect income, employer or address information can create verification problems.
5. Choosing an App Without Checking the Lender
A professional-looking app does not automatically prove that a loan offer is genuine.
6. Sharing OTPs or PINs
Legitimate financial processes should not require you to disclose confidential authentication credentials to another person.
7. Paying an Unverified "Approval Fee"
Be cautious about individuals asking for money in exchange for guaranteed approval.
Real-World Example: First-Time Salaried Borrower
Consider Arun, a fictional first-time digital borrower.
- Take-home salary: ₹42,000
- Existing EMI: ₹5,000
- Requested loan: ₹1.5 lakh
- Stable employment
- Regular salary credits
- Limited previous credit history
Instead of assuming that Arun will automatically qualify, a responsible assessment would consider:
- His verified income
- Existing obligations
- Credit information available
- Employment details
- Requested loan amount
- Proposed tenure
- Overall repayment capacity
- Lender-specific eligibility rules
The final decision would remain with the relevant lender.
This example illustrates an important point: being a first-time digital borrower does not automatically determine approval.
How to Improve Your Loan Approval Chances
Before applying
- Maintain accurate financial records.
- Keep KYC information updated.
- Review your credit report.
- Reduce unnecessary outstanding debt.
- Choose a realistic loan amount.
- Maintain sufficient monthly repayment capacity.
- Keep salary and bank records consistent.
- Apply through an authentic platform.
After receiving an offer
- Compare the total cost.
- Read the KFS.
- Check the repayment schedule.
- Understand applicable fees.
- Confirm the lending entity.
- Accept only if the EMI fits your budget.
Key Takeaways
Loan eligibility for first-time digital borrowers is based on more than salary or credit score.
- Salaried employees can potentially qualify for digital loans even with limited credit history.
- There is no universal salary or credit-score requirement for every lender.
- Income and repayment capacity are important.
- Existing EMIs can reduce borrowing capacity.
- KYC and financial documents may be required.
- Credit history should be checked for errors.
- Verify the actual lender before sharing sensitive information.
- Review APR, KFS, fees and repayment terms.
- Never rely on "guaranteed approval" promises.
- Borrow only an amount that can be comfortably repaid.
Vizzve Financial: Explore Loan Options
Vizzve Financial is a digital financial-services platform that facilitates access to loan products offered by lending partners. Its terms state that the actual lending decision is made by the respective lending partners, rather than by Vizzve itself. Vizzve Financial
Promotional copy:
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should independently review the identity of the lending partner, applicable charges, KFS/APR and all loan terms before accepting an offer.
Frequently Asked Questions
1. Can a first-time digital borrower get a personal loan?
Yes. A first-time digital borrower may qualify, subject to the lender's eligibility criteria, income, repayment capacity, credit information and other checks.
2. Is a credit score mandatory for first-time borrowers?
Not necessarily in the same way for every lender. Someone with limited credit history may still be assessed using other available information.
3. What salary is required for a digital personal loan?
There is no universal minimum salary. Each lender sets its own eligibility criteria.
4. Can salaried employees apply for loans online?
Yes. Many lenders provide digital application and verification processes for eligible salaried borrowers.
5. What documents are required for a digital loan?
Depending on the lender, documents or information may include PAN, identity/address proof, salary details, bank information and other KYC or income documents.
6. Does salary affect loan eligibility?
Yes. Income can help a lender assess the borrower's repayment capacity.
7. Do existing EMIs affect loan eligibility?
Yes. Existing debt obligations may affect how much additional repayment a borrower can reasonably take on.
8. Can I get a loan with no previous loan history?
Possibly. Having no previous loan history does not automatically mean rejection, but the lender may have fewer credit-history records to evaluate.
9. How can I check my credit report?
Individuals can obtain their credit information from the relevant Credit Information Companies. RBI's framework provides for one free full credit report including credit score each year from each CIC for individuals with available credit history. Reserve Bank of India
10. Is digital lending safe?
Digital lending can be safe when borrowers use authentic platforms connected with appropriate regulated entities and follow basic security practices. Borrowers should verify the lender and understand how their information is collected and used.
11. Should I apply through multiple loan apps?
Avoid unnecessary applications. First compare suitable options and understand the lender's terms before submitting applications.
12. What is APR in a digital loan?
APR represents the annualised cost of credit and is designed to provide a broader view of the loan cost than the interest rate alone. RBI's digital lending framework requires applicable digital loans to disclose the all-inclusive cost through APR. Reserve Bank of India
13. What is a Key Facts Statement?
A KFS is a standardised disclosure designed to help borrowers understand important loan terms and costs before entering into the loan agreement.
14. Can I improve my chances of loan approval?
You can improve your financial readiness by maintaining accurate information, managing existing debt, maintaining a healthy repayment record and requesting a loan amount that fits your repayment capacity.
15. Does Vizzve directly approve every loan?
No. Vizzve's terms state that it facilitates access to financial products offered by lending partners and that the final lending decision is made by those lending partners.
Published on : 14th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed