

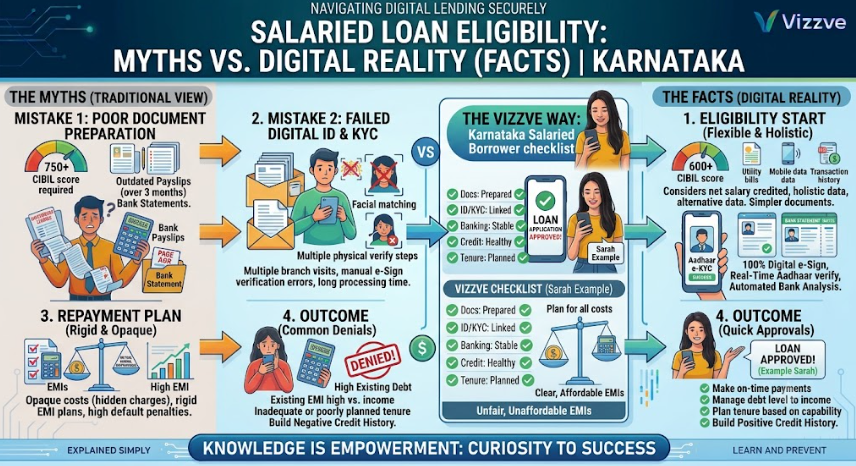
Introduction
Loan eligibility is often misunderstood. Many salaried employees assume that earning a certain salary automatically guarantees loan approval. Others believe that having a high credit score means every loan application will be accepted.
In reality, lenders usually consider several factors together, including income, employment stability, existing financial obligations, credit history, age, documentation and repayment capacity.
This guide separates common loan eligibility myths from facts so salaried employees in Karnataka can make better borrowing decisions.
AI Answer Box
What determines loan eligibility for salaried employees in Karnataka?
Loan eligibility generally depends on a combination of:
- Monthly income
- Employment stability
- Credit history
- Existing EMIs and debt
- Age
- Repayment capacity
- Banking and income records
- Required documentation
- Individual lender policies
Important: There is no single salary or credit-score number that guarantees approval from every lender.
Quick Answer
A salaried employee with stable income, manageable existing debt, a healthy repayment history and complete documentation may have a stronger loan application. However, the final decision depends on the lender's eligibility assessment.
Myth 1: A High Salary Guarantees Loan Approval
Fact: Salary Is Only One Part of Eligibility
A higher salary can increase repayment capacity, but it does not automatically guarantee approval.
Lenders may also assess:
- Existing EMIs
- Credit history
- Employment stability
- Age
- Current debt
- Banking history
- Documentation
- Loan amount requested
Example
Suppose two employees both earn ₹60,000 per month.
| Factor | Employee A | Employee B |
|---|---|---|
| Monthly salary | ₹60,000 | ₹60,000 |
| Existing EMI | ₹5,000 | ₹25,000 |
| Employment | Stable | Stable |
| Repayment history | Strong | Several delays |
| Financial burden | Lower | Higher |
Even though their salaries are identical, their overall profiles may be assessed differently.
Myth 2: A Good Credit Score Guarantees Approval
Fact: Credit Score Is Important, But Not the Only Factor
A good credit history can support an application, but lenders typically consider multiple factors.
A lender may still decline or modify an application because of:
- High existing debt
- Insufficient income
- Short employment history
- Incomplete documentation
- Internal eligibility rules
- Loan amount requested
What Should Borrowers Check?
Before applying, review your credit report for:
- Incorrect overdue information
- Unknown accounts
- Incorrect personal details
- Duplicate loans
- Accounts that should have been closed
Myth 3: Existing EMIs Mean You Cannot Get Another Loan
Fact: Existing EMIs Reduce Available Repayment Capacity, But Do Not Automatically Disqualify You
A borrower may still qualify for additional credit if the existing financial obligations remain manageable according to the lender's criteria.
For example:
Monthly income: ₹50,000
Existing EMI: ₹8,000
This is very different from:
Monthly income: ₹50,000
Existing EMIs: ₹25,000
The second borrower has considerably less income available for another repayment obligation.
Myth 4: Only Government Employees Get Easy Loans
Fact: Private-Sector Salaried Employees Can Also Qualify
Loan eligibility is not restricted to government employees.
Private-sector employees may qualify depending on factors such as:
- Salary
- Employment stability
- Employer profile
- Work experience
- Credit history
- Existing obligations
- Lender-specific requirements
Different lenders may use different employment criteria.
Myth 5: You Need a Very High Salary for a Personal Loan
Fact: Minimum Income Requirements Vary by Lender
There is no universal minimum salary applicable to every personal loan in India.
One lender may have different income criteria from another.
Therefore, borrowers should check the specific lender's eligibility requirements rather than relying on a fixed salary number found online.
Myth 6: Applying Online Means Automatic Approval
Fact: Online Application Does Not Mean Guaranteed Approval
Digital applications can make the process faster and more convenient, but lenders still need to evaluate the borrower's eligibility.
Online applications may involve:
- Application submission
- Identity verification
- Income verification
- Credit assessment
- Eligibility evaluation
- Loan offer
- Agreement and consent
- Disbursement, where approved
Approval remains subject to the lender's policies and verification.
Myth 7: Every Loan App Is a Lender
Fact: Borrowers Should Identify the Actual Lender
This is particularly important with digital borrowing.
Before accepting a digital loan, check:
- Name of the actual lender
- Whether the lender is regulated as applicable
- Loan terms
- Interest rate
- Processing charges
- Repayment schedule
- Privacy information
- Grievance/contact details
Do not assume that the name of an app is automatically the name of the institution providing the loan.
Myth 8: More Loan Applications Always Improve Approval Chances
Fact: Multiple Applications Can Create Unnecessary Credit Enquiries
Submitting applications to many lenders in a short period may result in multiple credit enquiries, depending on the lender and credit-reporting process.
A better approach is to:
- Compare lenders first
- Check eligibility
- Select suitable options
- Submit applications carefully
Myth 9: Only Credit Score Matters
Fact: Lenders Look at the Overall Financial Profile
Think of loan eligibility as a combination of several factors.
| Factor | Why It Matters |
|---|---|
| Income | Indicates repayment capacity |
| Employment | Indicates income stability |
| Credit history | Shows past repayment behaviour |
| Existing EMIs | Shows current debt burden |
| Age | May affect loan tenure and eligibility |
| Documents | Supports verification |
| Bank records | May help verify income and transactions |
| Loan amount | Determines repayment obligation |
No single factor necessarily decides the entire application.
Myth 10: Longer Loan Tenure Is Always Better
Fact: Longer Tenure Can Reduce EMI but Increase Total Interest
A longer repayment period can make monthly payments more manageable.
However, extending the tenure may increase the total interest paid over the life of the loan.
Simple Comparison
| Factor | Shorter Tenure | Longer Tenure |
|---|---|---|
| Monthly EMI | Usually higher | Usually lower |
| Repayment period | Shorter | Longer |
| Total interest | May be lower | May be higher |
| Monthly cash flow | More pressure | More flexibility |
Borrowers should choose a tenure based on affordability and total borrowing cost.
Myth 11: A Loan With a Low Interest Rate Is Always the Cheapest
Fact: Compare the Complete Cost
Interest rate is important, but borrowers should also check:
- Processing fee
- Applicable taxes
- Prepayment charges
- Late-payment charges
- Other applicable fees
- Total repayment amount
The overall cost of credit is more useful than comparing the headline rate alone.
Myth 12: You Can Ignore the Loan Agreement
Fact: Read the Terms Before Accepting
Before signing or electronically accepting a loan, review the applicable documents and disclosures.
Pay particular attention to:
- Loan amount
- Interest rate
- EMI
- Tenure
- Processing fee
- Repayment dates
- Prepayment conditions
- Late-payment charges
- Other applicable fees
Never accept a loan simply because the approval appears fast.
Karnataka Salaried Employee Loan Eligibility: Myth vs Fact
| Myth | Fact |
|---|---|
| High salary guarantees approval | Income is only one eligibility factor |
| Good credit score guarantees approval | Lenders assess the complete profile |
| Existing EMI means rejection | Eligibility depends on repayment capacity |
| Only government employees qualify | Private-sector employees may also qualify |
| Online applications guarantee approval | Verification and lender assessment still apply |
| Every loan app is a lender | Identify the actual lending institution |
| Longer tenure is always cheaper | Longer tenure can increase total interest |
| Low interest rate means lowest cost | Other charges also matter |
| More applications improve approval | Multiple enquiries may be recorded |
| Loan agreements can be skipped | Terms should be reviewed before acceptance |
How Salaried Employees Can Improve Loan Eligibility
1. Maintain Timely Repayments
Pay existing EMIs and credit-card dues on time.
2. Manage Existing Debt
Avoid taking on unnecessary debt before applying for a new loan.
3. Maintain Stable Employment
A consistent employment record can strengthen the overall profile.
4. Keep Documents Ready
Maintain updated:
- Salary slips
- Bank statements
- Identity documents
- Address documents
- Employment information
5. Check Your Credit Report
Correct inaccuracies before making a major credit application.
6. Borrow Within Your Means
Do not select the maximum amount merely because you are eligible for it.
Step-by-Step Loan Eligibility Check
Step 1: Calculate Take-Home Income
Start with your regular monthly income.
Step 2: List Existing Obligations
Include all active EMIs and significant credit commitments.
Step 3: Review Your Credit History
Check for errors and repayment issues.
Step 4: Estimate Affordable EMI
Leave enough money for essential expenses and emergency needs.
Step 5: Compare Lenders
Check eligibility requirements and total borrowing costs.
Step 6: Verify the Lender
Confirm the identity of the lending institution before sharing sensitive information.
Step 7: Read the Loan Documents
Review the applicable terms before accepting the offer.
Pros and Cons of Taking a Personal Loan
Pros
- Can provide access to funds without pledging an asset in many cases
- Online application may be convenient
- Fixed repayment schedules can make budgeting easier
- Can be useful for planned financial needs when affordable
Cons
- Interest increases the total cost
- EMIs reduce monthly disposable income
- Late payments can negatively affect credit history
- Additional fees may apply
- Borrowing more than necessary can create financial stress
Real-World Example
Consider Priya, a salaried employee in Bengaluru earning ₹55,000 per month.
She has:
- Stable employment
- Regular salary credits
- Existing EMI of ₹7,000
- Good repayment history
- Complete documents
Now consider Anil, who also earns ₹55,000 but has:
- Existing EMIs of ₹22,000
- Recent repayment delays
- Several recent credit applications
Although both earn the same salary, their financial profiles are different.
The key lesson: Loan eligibility is based on the overall borrower profile, not salary alone.
Expert Commentary
A responsible approach to borrowing starts with affordability rather than the maximum amount a lender may offer.
For salaried employees, a sensible evaluation should consider income, existing commitments, essential household expenses and emergency savings before adding another EMI.
Borrowers should also verify the lender and carefully review loan disclosures before sharing financial information or accepting digital credit.
Key Takeaways
- Salary does not guarantee loan approval.
- Credit score is important but not the only factor.
- Existing EMIs can affect borrowing capacity.
- Private-sector salaried employees may also qualify.
- Online applications do not guarantee approval.
- Verify the actual lender before sharing personal data.
- Compare total loan costs, not just interest rates.
- Read the loan agreement and applicable disclosures.
- Choose an EMI that remains affordable after essential expenses.
- Avoid unnecessary multiple loan applications.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Loan approval, interest rate, loan amount and other terms are subject to applicable eligibility criteria and the lender's assessment.
Frequently Asked Questions
1. Does a high salary guarantee personal loan approval?
No. Salary is one factor. Lenders may also consider credit history, existing obligations, employment and other eligibility criteria.
2. Does a good credit score guarantee a loan?
No. A good credit history can support an application, but it does not guarantee approval.
3. Can salaried employees with existing EMIs get another loan?
They may be able to, depending on their income, existing obligations and the lender's eligibility criteria.
4. Can private employees apply for personal loans?
Yes. Private-sector salaried employees may qualify if they meet the relevant lender's requirements.
5. Is there one minimum salary requirement for all lenders?
No. Income requirements vary between lenders and loan products.
6. Does employment stability affect loan eligibility?
It can. Lenders may consider employment tenure and income stability during assessment.
7. Does applying online guarantee faster approval?
Not necessarily. Online applications can simplify submission, but verification and credit assessment are still required.
8. Is every loan application app a lender?
No. A digital platform may have a different role from the institution actually providing the credit. Borrowers should identify the actual lender.
9. Can existing EMIs reduce loan eligibility?
Yes. Existing obligations reduce the amount of income available for another EMI.
10. Is a longer loan tenure better?
Not always. It can reduce the monthly EMI but may increase total interest paid.
11. Should borrowers compare processing fees?
Yes. Processing fees and other applicable charges can increase the overall borrowing cost.
12. Can multiple loan applications affect credit history?
Multiple credit enquiries may be recorded depending on the lender and credit-reporting process, so borrowers should avoid unnecessary applications.
13. What documents do salaried employees usually need?
Requirements vary, but lenders may request identity/address proof, salary slips, bank statements and employment information.
14. How can I improve my loan eligibility?
Maintain timely repayments, manage existing debt, maintain stable income and keep your financial documents accurate.
15. What should I check before accepting an online loan?
Verify the actual lender, interest rate, fees, repayment schedule, total cost, privacy terms and applicable loan documents.
Published on : 26th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed