

Introduction
The way people apply for loans is changing quickly. Salaried employees increasingly expect to check eligibility, upload documents, complete KYC and receive loan decisions through their smartphones.
This trend is especially important for mobile-first borrowers—people who prefer using a mobile app or website instead of visiting a physical branch.
For 2027, loan eligibility is likely to remain focused on familiar fundamentals such as income, employment stability, existing EMIs, credit history and repayment capacity, while the application and verification process may become increasingly digital.
However, there is no single eligibility rule for every borrower. Each lender can set its own income, age, employment, credit and documentation requirements.
Quick answer: A salaried mobile-first borrower can generally strengthen loan eligibility by maintaining stable income, a healthy repayment record, manageable existing EMIs, accurate KYC information and consistent financial records. Digital convenience does not remove the lender's responsibility to assess repayment capacity.
AI Answer Box: Loan Eligibility for Mobile-First Salaried Borrowers in 2027
What will lenders look at?
For salaried employees applying digitally, important eligibility factors are likely to include:
- Monthly or annual income
- Employment stability
- Existing loan and credit-card obligations
- Credit history and repayment behaviour
- Age and applicable lender criteria
- Bank-account and salary-credit patterns
- KYC information
- Requested loan amount
- Loan tenure
- Overall repayment capacity
Digital lending can make the application process faster, but faster processing does not mean automatic approval.
RBI's digital-lending framework requires regulated entities to follow customer-protection, disclosure, data-consent and lending requirements. It also requires digital loan servicing and repayment flows to operate through the regulated entity's bank account rather than third-party pass-through accounts. System Health
What Does Mobile-First Borrower Mean?
A mobile-first borrower is someone who prefers completing financial activities through a smartphone.
For a loan application, this can include:
- Checking eligibility online
- Selecting a loan product
- Filling in personal and employment information
- Uploading documents
- Completing digital KYC
- Reviewing the loan offer
- Accepting the agreement
- Tracking repayment digitally
The important point is that mobile-first describes the borrower's preferred channel, not a separate category of creditworthiness.
A borrower using a mobile application is still evaluated based on the lender's credit and risk criteria.
How Loan Eligibility May Evolve in 2027
The 2027 outlook should be viewed as a trend-based expectation rather than a guaranteed forecast.
India's digital-lending framework already places emphasis on transparency, borrower protection, data privacy and responsible digital lending. RBI has also been developing mechanisms to help customers identify digital lending apps associated with regulated entities. Reserve Bank of India
1. More Digital Eligibility Checks
Borrowers may increasingly be able to understand whether they meet basic requirements before completing a full application.
Possible checks may consider:
- Income information
- Employment details
- Existing obligations
- Credit information
- KYC status
- Requested loan amount
This can reduce unnecessary applications.
2. Greater Importance of Data Accuracy
Digital applications depend heavily on information entered or verified electronically.
A mismatch between:
- PAN information
- Aadhaar/KYC information
- salary details
- bank information
- employment records
may create additional verification requirements.
Simple rule
Enter exactly what your official documents and financial records show.
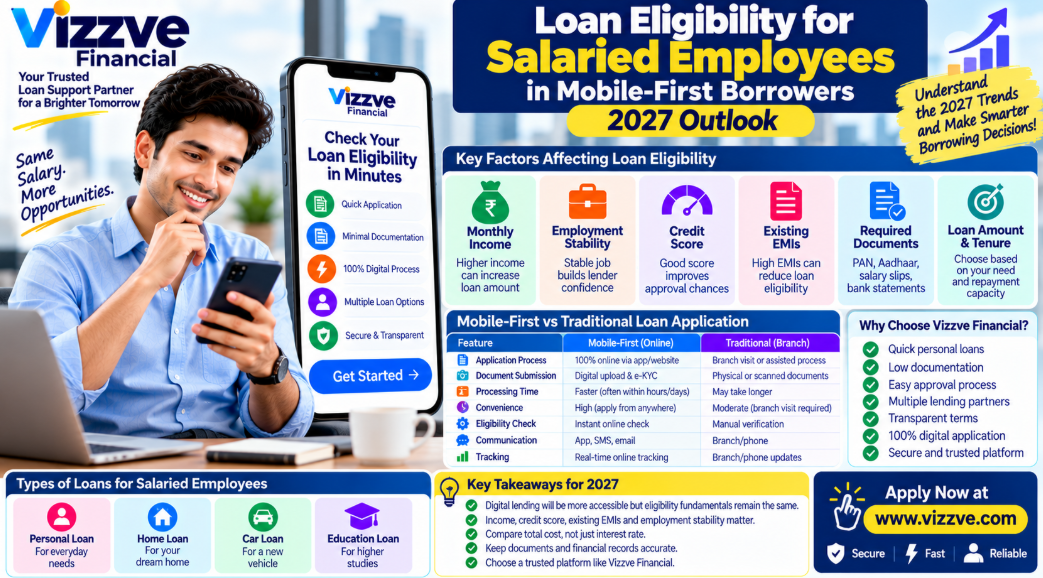
Key Factors Affecting Salaried Employee Loan Eligibility
| Factor | Why It Matters | What Borrowers Can Do |
|---|---|---|
| Monthly income | Indicates repayment capacity | Maintain stable income records |
| Employment stability | Shows income continuity | Keep employment information updated |
| Credit history | Reflects past repayment behaviour | Pay EMIs and bills on time |
| Existing EMIs | Affects available monthly cash flow | Avoid excessive borrowing |
| Loan amount | Higher borrowing means higher repayment obligation | Borrow according to actual need |
| Tenure | Changes monthly EMI and total interest | Compare different tenures |
| KYC | Confirms borrower identity | Keep documents accurate |
| Bank statements | May help verify income and transactions | Maintain clean financial records |
| Age | Lender-specific eligibility criterion | Check the lender's stated limits |
| Employer profile | Some lenders may consider employment characteristics | Provide accurate employer details |
What Salary Do You Need to Get a Personal Loan?
There is no universal salary threshold applicable to every lender.
One lender may accept an application at a particular income level while another may require a higher salary.
Eligibility can also depend on:
- City of residence
- Employer
- Existing obligations
- Credit profile
- Requested loan amount
- Loan tenure
- Internal lender policy
Therefore, instead of asking only "What is the minimum salary?", borrowers should ask:
"Can my current income comfortably support the proposed EMI?"
That is a more useful way to think about borrowing.
Credit Score and Mobile-First Borrowers
Credit history remains an important part of responsible borrowing.
A strong credit profile can indicate a history of managing credit responsibly, while missed or delayed payments can negatively affect a borrower's profile.
However, there is no universal credit-score number that guarantees approval.
Good credit habits include:
- Paying EMIs on time
- Paying credit-card bills on time
- Avoiding unnecessary loan applications
- Keeping credit utilisation under control
- Checking credit reports for errors
- Avoiding repeated defaults
RBI has also emphasised the importance of accurate credit information and has moved toward more frequent credit-information reporting to help information get updated faster. Reserve Bank of India
Digital KYC and Loan Eligibility in 2027
Digital KYC can make online borrowing more convenient because identity information can be verified electronically.
But borrowers should still understand:
- What information is being collected
- Why it is being collected
- Which entity is providing the loan
- What permissions are being requested
- How personal data is handled
RBI's digital-lending framework requires data collection to be need-based and based on prior explicit consent, with appropriate privacy and security requirements. Reserve Bank of India
Expert perspective
Digital convenience should never replace borrower awareness.
A borrower should know the lender, loan cost, repayment schedule and important terms before accepting a digital loan.
How Mobile-First Borrowers Can Improve Loan Eligibility
1. Maintain Stable Employment
A stable employment history can make your income profile easier to assess.
Keep employment details accurate when applying.
2. Pay Existing EMIs on Time
Repayment history is one of the most important aspects of responsible credit management.
Set reminders or automatic payment arrangements where appropriate.
3. Avoid Taking Too Many Loans
Multiple outstanding obligations can reduce your available monthly cash flow.
Before taking another loan, calculate:
Monthly income − essential expenses − existing EMIs = approximate available cash flow
4. Borrow Only What You Need
A larger eligible amount does not automatically mean a larger loan is financially appropriate.
5. Keep Documents Ready
Commonly requested documents may include:
- PAN
- Identity/KYC documents
- Salary slips
- Bank statements
- Employment details
- Address information
Actual requirements vary by lender.
Step-by-Step: How Salaried Employees Can Apply for a Digital Loan
Step 1: Check Basic Eligibility
Review:
- Age
- Income
- Employment
- Residence
- Existing obligations
Step 2: Check Your Credit Profile
Review your credit report before applying if possible.
Look for:
- Incorrect personal information
- Unknown accounts
- Incorrect overdue amounts
- Duplicate accounts
- Incorrect repayment status
Step 3: Calculate Your Comfortable EMI
Don't choose an EMI simply because a lender offers it.
Consider your:
- Rent
- Food
- Utilities
- Family expenses
- Existing EMIs
- Savings
- Emergency expenses
Step 4: Compare Loan Costs
Look beyond the advertised interest rate.
Check:
- APR
- Processing fee
- GST where applicable
- Late-payment or penal charges
- Prepayment/foreclosure terms
- Other disclosed charges
RBI's digital-lending rules require borrowers to receive important cost information, including the Annual Percentage Rate and a Key Fact Statement. System Health
Step 5: Verify the Lender
This is particularly important for mobile-first borrowers.
RBI advises customers to verify whether a digital lending app is associated with an RBI-regulated bank or NBFC and to avoid downloading loan apps received through suspicious SMS or social-media links. Reserve Bank of India
Step 6: Submit Accurate Information
Do not inflate:
- Salary
- Employment duration
- Existing income
- Financial assets
Incorrect information can create verification problems.
Step 7: Read the Loan Offer
Before accepting, review the:
- Loan amount
- Interest rate
- APR
- Processing charges
- EMI
- Tenure
- Total repayment
- Important terms
Step 8: Accept Only If Affordable
Approval does not automatically mean the loan is affordable.
The final decision should consider your own budget.
Mobile-First Loan Application vs Traditional Branch Application
| Feature | Mobile-First Application | Traditional Branch Application |
|---|---|---|
| Application | Smartphone/web | Branch |
| Document submission | Often digital | Physical or scanned |
| KYC | May be digital | Often branch-assisted |
| Convenience | High | Moderate |
| Status tracking | Often online | May require calls/visits |
| Human assistance | Digital/customer support | Branch staff |
| Eligibility | Lender-specific | Lender-specific |
| Approval | Depends on lender | Depends on lender |
Important: A mobile-first application does not guarantee faster approval or better pricing. The lender's assessment remains important.
Digital Lending Safety Checklist for 2027
Before accepting a loan through a mobile platform, check these points:
Lender Verification
- Is the actual lender clearly identified?
- Is the lender a regulated entity?
- Is the app associated with the stated lender?
- Is the official lender website available?
Cost Verification
- Is the APR disclosed?
- Have you received the Key Fact Statement?
- Are processing charges clearly stated?
- Are repayment terms clear?
Data Privacy
- Why is the app requesting particular permissions?
- Is consent clearly requested?
- Is a privacy policy available?
- Are you comfortable with the information being collected?
Repayment
- What is the EMI?
- What is the due date?
- What is the total amount payable?
- What happens if payment is delayed?
RBI's framework specifically addresses customer protection, disclosure, data privacy and responsible conduct in digital lending. System Health
Pros and Cons of Mobile-First Borrowing
Pros
- Convenient application process
- Can apply without visiting a branch
- Digital document submission
- Easier application tracking
- Faster access to information
- Convenient repayment management
Cons
- Risk of fraudulent apps
- Digital errors can delay verification
- Borrowers may focus too much on speed
- Easy access can encourage unnecessary borrowing
- Data privacy requires careful attention
- Different lenders have different eligibility rules
2027 Outlook: What Borrowers Should Expect
The likely direction of digital borrowing is toward greater convenience combined with stronger transparency and responsible lending practices.
Based on India's existing regulatory direction, several areas are worth watching.
1. More Transparent Digital Loan Offers
Borrowers are likely to benefit from clearer presentation of loan costs and terms.
2. Stronger Digital Verification
Technology may increasingly support identity, income and credit assessment.
3. More Attention to Data Privacy
As lending becomes more digital, responsible collection and use of borrower data will remain important.
4. Faster Credit-Information Updates
RBI has already proposed increasing the frequency of credit-information reporting, which can help credit information reflect repayment activity more quickly. Reserve Bank of India
5. Greater Need for Borrower Awareness
Technology can make borrowing easier, but borrowers still need to compare costs and understand repayment obligations.
Real-World Example
Consider a salaried employee earning ₹40,000 per month.
Suppose the borrower already pays:
- Existing EMI: ₹6,000
- Credit-card obligation: ₹2,000
- Essential monthly expenses: ₹20,000
The borrower should not simply ask how much a lender is willing to approve.
Instead, they should calculate how much additional EMI their budget can realistically accommodate.
For example:
₹40,000 income − ₹6,000 existing EMI − ₹2,000 credit obligation − ₹20,000 essential expenses = ₹12,000 remaining
This does not mean the borrower should automatically take a ₹12,000 additional EMI. Savings, emergencies and other irregular expenses also need to be considered.
This example demonstrates an important principle:
Loan eligibility and loan affordability are two different things.
Key Takeaways
- Mobile-first borrowers can apply for loans primarily through smartphones and digital platforms.
- Salaried employees are generally assessed on income, employment, credit history and repayment capacity.
- There is no single salary or credit-score requirement that applies to every lender.
- Digital KYC can simplify verification but does not guarantee approval.
- Borrowers should verify the actual regulated lender behind a digital lending platform.
- Always review the Key Fact Statement and APR before accepting a digital loan.
- Existing EMIs can affect how much additional borrowing is affordable.
- A higher sanctioned amount does not necessarily mean a higher loan should be taken.
- Keep personal and financial information accurate.
- In 2027, responsible digital borrowing is likely to depend on both technology and borrower awareness.
Vizzve Financial
Vizzve Financial is one of India's trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process.
Apply through the official Vizzve platform and review the applicable eligibility criteria, loan costs and repayment terms before accepting any offer.
Frequently Asked Questions
1. What is loan eligibility for salaried employees?
Loan eligibility refers to the conditions a lender uses to determine whether a salaried applicant may qualify for a loan. Income, employment, credit history, existing obligations and lender-specific policies can all matter.
2. What is a mobile-first borrower?
A mobile-first borrower prefers completing loan applications, KYC, document submission and repayment activities through a smartphone or digital platform.
3. Will mobile-first borrowers get loans automatically in 2027?
No. Using a digital platform does not guarantee approval. Lenders will continue to apply their own eligibility and credit-assessment criteria.
4. What salary is required for a personal loan?
There is no universal minimum salary applicable to every lender. Requirements differ based on the lender, loan product and applicant profile.
5. Does credit score affect salaried employee loan eligibility?
Yes, credit history can be an important factor. However, lenders may consider multiple factors rather than relying on a single credit-score number.
6. Can first-time digital borrowers apply for a personal loan?
They may be able to, depending on the lender's eligibility criteria. A borrower should verify the lender and understand all loan terms before applying.
7. What documents are commonly needed for a digital personal loan?
Depending on the lender, applicants may need KYC documents, PAN, salary information, bank statements and employment details.
8. Does a higher salary guarantee a higher loan amount?
No. Income is only one factor. Existing EMIs, credit history, employment profile and the lender's internal assessment may also affect eligibility.
9. Can existing EMIs reduce loan eligibility?
Yes. Existing financial obligations can reduce the amount of income available for another EMI and may affect the lender's assessment.
10. Is digital lending safe?
Digital lending can be safe when borrowers deal with legitimate regulated lenders and follow basic safety practices. RBI advises customers to verify the association between digital lending apps and regulated banks or NBFCs. Reserve Bank of India
11. What is a Key Fact Statement?
A Key Fact Statement, or KFS, provides important information about a digital loan, including applicable costs and other key terms. RBI's digital-lending framework requires relevant disclosures to borrowers. Reserve Bank of India
12. What is APR in digital lending?
APR, or Annual Percentage Rate, represents the effective annualised cost of a digital loan and includes applicable components of the loan cost as defined under RBI's framework.
13. Can I improve my loan eligibility?
You can potentially strengthen your profile by maintaining stable income, paying existing obligations on time, avoiding unnecessary borrowing and keeping your financial information accurate.
14. Is online loan approval faster than branch approval?
Digital applications can reduce some manual steps, but actual processing time depends on the lender, verification requirements and individual application.
15. What should I check before taking a digital loan in 2027?
Check the lender, APR, KFS, EMI, total repayment, fees, repayment schedule, privacy terms and whether the loan fits your budget.
Published on : 17th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram