

Introduction
For salaried employees, applying for a personal loan through a mobile device can be simple and convenient. However, being able to complete an online application does not necessarily mean that the borrower will qualify for the requested amount.
Loan eligibility is usually assessed using several factors, including income, employment details, existing financial obligations, credit history and the lender's own policies.
For mobile-first borrowers, there is another important consideration: understanding the actual lender, loan costs, repayment terms and applicable digital-lending disclosures before accepting an offer.
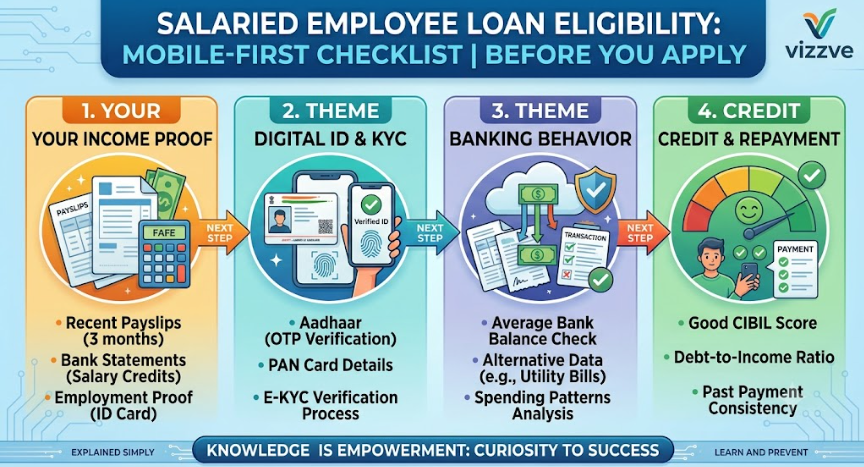
This eligibility checklist helps salaried employees prepare before submitting a digital loan application.
AI Answer Box: What Should Salaried Employees Check Before Applying?
Short answer: Salaried employees should check their monthly income, employment stability, existing EMIs, credit history, requested loan amount, documents, repayment capacity and lender-specific eligibility requirements.
Quick Eligibility Checklist
- Stable salaried income
- Current employment details are accurate
- Existing EMIs are manageable
- Credit history has been reviewed
- Requested loan amount is realistic
- Required documents are available
- EMI fits the monthly budget
- Interest rate and APR are understood
- Processing fees and other charges are checked
- Actual lender is verified
- Key Facts Statement is reviewed where applicable
- Loan agreement is read before acceptance
Important: Eligibility criteria vary between lenders. Meeting a checklist does not guarantee loan approval.
What Is Loan Eligibility for Salaried Employees?
Loan eligibility refers to the lender's assessment of whether a borrower qualifies for a particular loan amount and repayment structure.
For salaried employees, factors can include:
- Monthly income
- Employment details
- Existing debt obligations
- Credit history
- Requested loan amount
- Loan tenure
- Banking information
- Age and other lender-specific criteria
- Internal underwriting policies
There is no single eligibility formula that applies to every lender.
1. Monthly Salary Checklist
Your monthly income is one of the first things to review.
Before applying, identify your actual take-home salary rather than relying only on your gross salary.
Check:
- Monthly take-home income
- Salary-credit pattern
- Regular deductions
- Existing salary advances
- Other recurring income, if accepted by the lender
Why it matters
A higher salary can support a larger repayment capacity, but the lender may also consider existing financial commitments.
2. Employment Checklist
Your employment profile can be relevant when a lender evaluates repayment capacity.
Review the information you provide about:
- Employer name
- Job role
- Employment type
- Length of employment
- Current employment status
- Salary-credit account
Keep information consistent
Your application details should match the supporting documents you provide.
For example, avoid entering an incorrect employer name or employment duration simply to improve your application.
3. Existing EMI Checklist
Existing debt is an important part of affordability.
Make a list of:
- Personal-loan EMIs
- Vehicle-loan EMIs
- Home-loan EMIs
- Education-loan EMIs
- Credit-card repayments
- Other recurring debt obligations
Simple calculation
Monthly income − existing debt obligations = amount available before regular living expenses
Then consider:
- Rent
- Food
- Utilities
- Family expenses
- Insurance
- Savings
- Emergency expenses
Only after this should you decide whether another EMI is comfortable.
4. Credit History Checklist
Before applying, review your credit profile.
Check for:
- Missed payments
- Overdue accounts
- Active loans
- Credit-card balances
- Credit utilisation
- Recent enquiries
- Incorrect personal information
- Accounts that should have been closed
Why this matters
A credit history gives lenders information about previous borrowing and repayment behaviour.
However, there is no universal credit-score number that guarantees approval. Each lender can have its own assessment criteria.
5. Loan Amount Checklist
Don't automatically choose the maximum amount shown by an eligibility calculator.
Ask:
How much do I actually need?
If your requirement is ₹80,000, borrowing ₹2 lakh simply because you are eligible can create unnecessary repayment pressure.
Consider:
- Actual purpose
- Urgency
- Monthly EMI
- Total repayment
- Existing financial obligations
- Emergency savings
Eligibility is a maximum assessment; it is not a recommendation to borrow the maximum.
6. EMI Affordability Checklist
An EMI should fit comfortably within your monthly cash flow.
Before applying, calculate:
Take-home salary − existing EMIs − essential expenses − regular commitments = available cash flow
Then consider the proposed new EMI.
Example
Suppose:
| Particular | Amount |
|---|---|
| Take-home salary | ₹50,000 |
| Existing EMI | ₹8,000 |
| Essential expenses | ₹25,000 |
| Other commitments | ₹5,000 |
| Remaining cash flow | ₹12,000 |
A borrower should not automatically use the entire ₹12,000 for a new EMI. An emergency buffer is important.
7. Loan Tenure Checklist
Loan tenure affects both EMI and total borrowing cost.
| Shorter Tenure | Longer Tenure |
|---|---|
| Higher EMI is possible | Lower EMI is possible |
| Loan ends sooner | Loan continues longer |
| Total interest may be lower | Total interest may be higher |
| Higher monthly pressure | Lower monthly pressure |
Choose a tenure based on your actual financial capacity.
8. Interest Rate and APR Checklist
Don't compare personal loans using only the advertised interest rate.
Check:
- Interest rate
- APR
- Processing fee
- Applicable taxes
- Other disclosed charges
- EMI
- Total repayment
For applicable digital loans, RBI's framework requires disclosure of the all-inclusive cost through the Annual Percentage Rate (APR). The Key Facts Statement provides important information about the credit terms before acceptance.
9. Document Checklist for Salaried Employees
The exact requirements vary by lender, but borrowers may be asked for documents such as:
- Identity/KYC documents
- Address information
- Salary slips
- Bank statements
- Employment information
- Other income or financial documents where applicable
Before uploading
Make sure documents are:
- Clear
- Complete
- Current
- Legible
- Consistent with your application
Never knowingly submit false or altered information.
10. Digital Lending Safety Checklist
Mobile-first borrowers should verify more than just eligibility.
Check the lender
Confirm:
- Actual lender name
- Official website
- Loan agreement
- Customer support
- Grievance-redressal information
- Applicable regulatory disclosures
Check the application
Be cautious if an application:
- Makes unrealistic approval promises
- Hides important charges
- Does not clearly identify the lender
- Requests unnecessary permissions
- Provides unclear repayment information
RBI's digital-lending framework includes requirements relating to borrower disclosures, data collection and consent.
11. Key Facts Statement Checklist
For applicable loans, read the Key Facts Statement (KFS) before accepting the credit.
Review:
- Loan amount
- Interest rate
- APR
- Fees
- Tenure
- Repayment schedule
- Penal charges
- Other applicable terms
Don't accept a loan simply because the application says "Approved."
Understand what you are agreeing to first.
12. Bank Account Checklist
For a salaried borrower, the account receiving salary can help demonstrate regular income.
Before applying, review:
- Salary credits
- Existing EMI debits
- Regular financial obligations
- Available balance
- Recent unusual transactions
Never provide another person's bank account details for your loan application unless the lender specifically permits such an arrangement under its documented process.
13. Personal Information Checklist
Make sure your application contains accurate:
- Full name
- Date of birth
- Address
- Mobile number
- Employer details
- Income
- Bank information
Name mismatches between documents and applications can sometimes cause verification issues.
Loan Eligibility Checklist: Quick Table
| Eligibility Factor | What to Check | Why It Matters |
|---|---|---|
| Income | Take-home salary | Indicates repayment capacity |
| Employment | Current job details | Helps establish income stability |
| Credit history | Repayment record | Shows past credit behaviour |
| Existing EMIs | Current debt obligations | Affects affordability |
| Loan amount | Actual requirement | Prevents unnecessary borrowing |
| Tenure | Repayment period | Affects EMI and total cost |
| Documents | Accuracy and clarity | Supports verification |
| APR | Overall annualised cost | Helps compare applicable credit |
| Fees | Processing and other charges | Affects total cost |
| Lender | Actual lending entity | Important for transparency |
| KFS | Key loan terms | Helps informed acceptance |
| EMI | Monthly repayment | Determines budget impact |
Step-by-Step Loan Eligibility Preparation
Step 1: Calculate Your Take-Home Salary
Start with the amount actually credited after regular deductions.
Step 2: List Existing Loans
Write down every EMI and outstanding debt.
Step 3: Review Your Credit History
Check your repayment history and look for errors.
Step 4: Decide the Required Loan Amount
Borrow according to your actual need.
Step 5: Estimate EMI Affordability
Make sure the proposed EMI leaves room for living expenses and emergencies.
Step 6: Prepare Documents
Keep required KYC, income and banking documents ready.
Step 7: Compare Loan Costs
Review interest rate, APR, fees, EMI and total repayment.
Step 8: Verify the Lender
Know who is actually providing the credit.
Step 9: Read the KFS
Review the applicable Key Facts Statement carefully.
Step 10: Read the Agreement
Understand the contractual terms before accepting.
Step 11: Confirm the Repayment Date
Know exactly when your EMI is due.
Step 12: Apply Only When Ready
Once the information is accurate and the loan is affordable, proceed with the application.
Common Eligibility Mistakes to Avoid
Mistake 1: Looking Only at Salary
Salary is important, but existing obligations also matter.
Mistake 2: Taking the Maximum Eligible Amount
Maximum eligibility does not mean maximum affordability.
Mistake 3: Ignoring Existing EMIs
Existing debt can significantly reduce available monthly cash flow.
Mistake 4: Applying Everywhere
Compare first and apply selectively.
Mistake 5: Ignoring the Credit Report
Unexpected errors or overdue accounts can affect the application.
Mistake 6: Choosing a Loan Only Because of a Low EMI
A longer tenure can reduce EMI while increasing total interest.
Mistake 7: Skipping the KFS
Important costs and conditions may be overlooked.
Mistake 8: Not Verifying the Lender
Always identify the actual lending entity.
Pros and Cons of Digital Loan Applications
Pros
- Convenient mobile application
- Digital document submission
- Less physical paperwork
- Faster application process
- Easy access to loan information
- Convenient repayment tracking
Cons
- Easy access can encourage unnecessary borrowing
- Borrowers may overlook fees
- Misleading digital platforms can create risks
- Privacy permissions require attention
- Multiple applications may create unnecessary credit enquiries
Real-World Example
Consider a salaried employee earning ₹45,000 per month.
They already have:
- Existing EMI: ₹7,000
- Household expenses: ₹22,000
- Other regular commitments: ₹5,000
Before applying for another loan, they calculate their remaining cash flow instead of assuming their salary alone makes them eligible.
They then:
- Check their credit history.
- Decide how much they actually need.
- Compare loan costs.
- Check the EMI.
- Review the APR and applicable fees.
- Verify the lender.
- Read the KFS.
- Confirm that the repayment fits their budget.
Lesson
A strong loan application is not just about meeting eligibility criteria. It is about demonstrating accurate information and choosing a repayment obligation that fits your finances.
Expert Perspective
For salaried borrowers, the safest way to approach digital credit is to separate three questions:
Question 1: Am I eligible?
This depends on the lender's criteria.
Question 2: Can I afford it?
This depends on your income, existing obligations and monthly expenses.
Question 3: Is it worth the cost?
This requires comparing interest, APR, fees, tenure and total repayment.
A borrower should be able to answer all three questions before accepting a loan.
Key Takeaways
- Salary is only one part of loan eligibility.
- Check your existing EMIs before applying.
- Review your credit history.
- Borrow only the amount you actually need.
- Calculate EMI affordability.
- Compare APR and overall loan cost.
- Check processing fees and applicable charges.
- Keep documents accurate and ready.
- Verify the actual lender.
- Read the KFS where applicable.
- Read the loan agreement before acceptance.
- Check digital permissions carefully.
- Never treat a maximum eligible amount as a recommended borrowing amount.
- Make repayment planning part of the application process.
Frequently Asked Questions
1. What is the basic eligibility for a salaried personal loan?
Eligibility varies by lender but can depend on income, employment details, credit history, existing obligations, age and other lender-specific criteria.
2. Does a higher salary guarantee loan approval?
No. Salary is only one factor in a lender's assessment.
3. Can existing EMIs reduce my loan eligibility?
Yes. Existing debt obligations can affect repayment capacity and the amount a lender may be willing to provide.
4. What credit score is required for a personal loan?
There is no single score that guarantees approval across all lenders. Eligibility criteria vary.
5. Should I check my credit report before applying?
Yes. It can help you identify repayment issues or incorrect information before submitting an application.
6. What documents do salaried employees need?
Requirements vary. Commonly requested documents can include KYC, salary information, bank statements and employment-related details.
7. Is the maximum eligible loan amount safe to borrow?
Not necessarily. Borrow according to your actual requirement and repayment capacity.
8. How do I calculate whether an EMI is affordable?
Subtract existing EMIs and essential expenses from your take-home salary, while keeping an emergency buffer.
9. What should I compare between two personal loans?
Compare interest rate, APR, fees, EMI, tenure and total repayment.
10. What is APR?
APR is an annualised measure of the overall cost of applicable credit and is useful when comparing loan offers.
11. What is a Key Facts Statement?
A KFS provides important information about applicable credit terms and costs before the borrower accepts the loan.
12. Can mobile-first borrowers apply for a loan completely online?
Some lenders offer fully digital application processes. The exact process depends on the lender and loan product.
13. Should I apply to multiple lenders to improve my chances?
It is better to compare lenders first and apply selectively rather than submitting unnecessary applications.
14. What should I check before accepting a digital loan?
Check the actual lender, APR, fees, EMI, tenure, total repayment, KFS, agreement and repayment conditions.
15. Does meeting the eligibility checklist guarantee loan approval?
No. The final decision depends on the lender's assessment and applicable eligibility criteria.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should independently review eligibility, loan costs, lender details and repayment obligations before accepting credit.
Conclusion
A loan eligibility checklist helps salaried employees prepare before applying, but eligibility is only the first step.
Before taking a digital personal loan, check your salary, employment, credit history, existing EMIs, required loan amount, documents, EMI affordability and complete borrowing cost.
For mobile-first borrowers, lender verification and digital-lending disclosures are equally important.
The best approach is simple:
Check your eligibility → check affordability → compare costs → verify the lender → read the terms → then apply.
A well-prepared borrower is more likely to make a confident and financially responsible borrowing decision.
Published on : 21th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed