

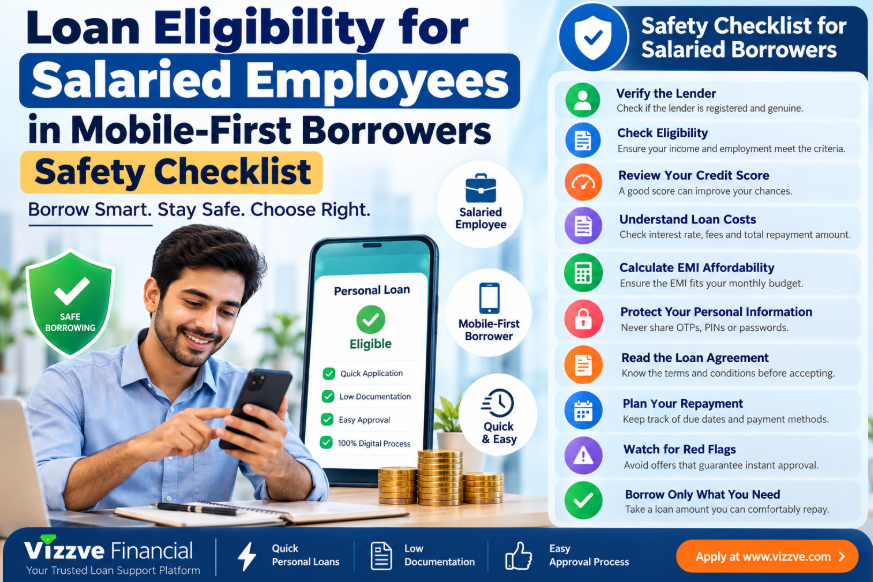
Introduction
Digital borrowing has made it easier for salaried employees to explore loans using a smartphone. Applications can often be submitted online, documents can be verified digitally, and borrowers may receive updates without visiting a branch.
But convenience comes with responsibility.
Before applying for a digital loan, borrowers should confirm who the actual lender is, how much the loan will cost, what information is being collected, and whether the EMI is affordable.
This safety checklist is designed to help salaried mobile-first borrowers make a more informed decision.
Quick answer: Before accepting a digital loan, verify the lender, review the complete cost, check the repayment schedule, protect personal information and borrow only an amount you can comfortably repay.
AI Answer Box: How Can Salaried Employees Safely Apply for a Digital Loan?
Salaried employees can reduce digital borrowing risks by following five basic steps:
- Verify the lender and lending arrangement.
- Check eligibility and affordability before applying.
- Review interest, fees and total repayment costs.
- Protect personal, banking and authentication information.
- Read the loan agreement and repayment terms before accepting.
A mobile application does not automatically mean a loan is safe, cheap or guaranteed.
H2: Why Do Salaried Mobile-First Borrowers Need a Safety Checklist?
A mobile-first borrower may complete most of the borrowing journey through a smartphone.
This can be convenient, but borrowers may make decisions quickly without reviewing the details.
Common mistakes include:
- Applying without checking the actual lender
- Looking only at the advertised interest rate
- Ignoring processing or other applicable charges
- Borrowing more than necessary
- Sharing sensitive information with unknown persons
- Accepting an agreement without reading it
- Assuming digital approval means guaranteed approval
A checklist helps slow down the decision and identify important details before money is borrowed.
H2: Loan Eligibility Safety Checklist for Salaried Employees
Use this checklist before submitting a digital loan application.
| Safety Check | What to Verify |
|---|---|
| Lender | Confirm the actual regulated lender or lending arrangement |
| Eligibility | Check income and other stated criteria |
| Credit profile | Review your credit history where relevant |
| Employment | Provide accurate employment information |
| Loan amount | Borrow only what you need |
| Interest | Understand how interest is calculated |
| Fees | Review processing and other applicable charges |
| EMI | Confirm the monthly repayment |
| Tenure | Check the complete repayment period |
| Privacy | Understand how personal information is handled |
| Agreement | Read the loan documents before accepting |
| Repayment | Know the due dates and payment method |
H2: 1. Verify the Actual Lender
This is one of the most important safety checks.
Before providing financial information, identify the entity that is actually providing the credit.
A digital platform, app or website may be different from the regulated lender behind the loan.
Check for:
- Legal lender name
- Official website
- Contact details
- Loan terms
- Applicable regulatory disclosures
- Grievance or customer-support information
Do not rely only on an app's name or promotional advertisement.
H2: 2. Never Assume That Digital Means Guaranteed Approval
A common misunderstanding is:
"If I apply online, the loan will be approved instantly."
That is not necessarily true.
A lender may assess:
- Income
- Employment
- Credit history
- Existing obligations
- Requested loan amount
- Repayment capacity
- Internal risk criteria
Digital processing can make an application more convenient, but approval remains subject to the lender's assessment and applicable terms.
H2: 3. Check Your Loan Eligibility Before Applying
Before submitting an application, ask:
Basic eligibility questions
- Do I meet the stated age criteria?
- Does my income meet the lender's requirements?
- Is my employment information accurate?
- Do I have existing loan obligations?
- Can I comfortably afford another EMI?
- Is the requested amount actually necessary?
A borrower should not select a loan amount simply because the lender may offer that amount.
H2: 4. Calculate EMI Affordability
A loan should fit into your monthly budget.
For example, suppose a salaried employee earns ₹50,000 per month.
If existing loan payments already total ₹12,000, adding another large EMI may create financial pressure.
A simple budgeting approach is:
Take-home income − essential expenses − existing EMIs = available surplus
The new EMI should be considered against this remaining amount.
Important
An EMI that looks affordable on paper may still become difficult if you have:
- Rent
- School expenses
- Medical expenses
- Household costs
- Insurance premiums
- Credit-card payments
- Other unexpected expenses
H2: 5. Review the Complete Cost of the Loan
Do not compare loans using the interest rate alone.
Look for:
- Interest rate
- Processing fee
- Applicable taxes
- Late-payment charges
- Other applicable charges
- Total repayment
- Prepayment or foreclosure conditions, where applicable
Simple example
Suppose two loans have similar advertised rates.
| Factor | Loan A | Loan B |
|---|---|---|
| Interest rate | Similar | Similar |
| Processing fee | Lower | Higher |
| Other charges | Lower | Higher |
| Total repayment | Lower | Higher |
The loan with the lower advertised rate is not automatically the cheaper option.
Compare the complete cost.
H2: 6. Protect Your Personal Information
Digital loan applications may require sensitive information.
Be careful with:
- PAN information
- Aadhaar-related information
- Bank details
- Salary information
- Account credentials
- OTPs
- Passwords
- Card information
Golden rule
Never share an OTP, PIN or password with an unknown person claiming to help process your loan.
Use official channels for verification and customer support.
H2: 7. Be Careful With Loan Apps and Links
Avoid downloading applications from unknown sources or clicking suspicious links received through messages.
Before using a digital lending service:
- Check the official source.
- Verify the lender.
- Review the privacy information.
- Check the permissions requested.
- Read the loan terms.
- Confirm customer-support details.
If something appears unusually urgent or suspicious, stop and verify it independently.
H2: 8. Read the Loan Agreement Before Accepting
Do not treat the agreement as a formality.
Look for:
- Principal amount
- Interest rate
- Annualised cost disclosures where applicable
- EMI amount
- Number of repayments
- Repayment dates
- Fees
- Default or late-payment consequences
- Prepayment conditions
- Grievance redressal information
- Other important contractual terms
Expert tip
If you do not understand a clause, don't accept the loan until you understand what it means.
H2: 9. Check the Repayment Schedule
A borrower should know exactly:
How much? When? For how long?
Create a simple repayment table before accepting.
| Item | Example |
|---|---|
| Loan amount | ₹1,00,000 |
| EMI | Depends on rate and tenure |
| Tenure | Depends on loan agreement |
| First due date | As specified by lender |
| Total repayment | As disclosed by lender |
Do not rely on memory. Save the repayment schedule and agreement.
H2: 10. Keep Your Employment and Income Information Accurate
Salaried borrowers should provide truthful information about:
- Employer
- Salary
- Employment duration
- Existing liabilities
- Contact details
Providing inaccurate information can create verification issues and may affect the application.
H2: 11. Don't Apply to Too Many Lenders Without Comparing
Searching for the best loan is sensible.
However, repeatedly submitting formal applications without understanding the process can lead to multiple credit enquiries, depending on the lender and credit-reporting system.
A better approach is:
Research → Compare → Check eligibility → Apply selectively
H2: 12. Watch Out for Common Digital Loan Red Flags
Be cautious if a service:
- Guarantees approval for everyone
- Demands unexplained upfront payments
- Refuses to identify the actual lender
- Uses suspicious contact details
- Pressures you to act immediately
- Requests unnecessary sensitive information
- Provides unclear loan terms
- Avoids giving written documentation
One red flag may not tell the whole story, but several together should prompt additional verification.
H2: 13. First-Time Digital Borrower Safety Checklist
First-time borrowers should take extra care.
Before applying
- Verify the lender
- Check eligibility
- Calculate affordable EMI
- Compare loan costs
- Read privacy information
- Review applicable fees
During application
- Enter accurate information
- Use official channels
- Check the website/app carefully
- Never share OTPs or passwords
- Review permissions and disclosures
Before accepting
- Read the agreement
- Confirm loan amount
- Confirm interest and applicable charges
- Confirm EMI
- Confirm tenure
- Check repayment dates
- Save the documents
H2: Mobile-First Borrowers vs Traditional Branch Borrowers
| Feature | Mobile-First | Branch-Based |
|---|---|---|
| Application | Primarily digital | Usually in person |
| Convenience | High | Depends on location |
| Documentation | Often digital | May involve physical copies |
| Communication | App/SMS/email/calls | Branch and other channels |
| Verification | May be digital | May involve branch processes |
| Safety responsibility | High | High |
| Need to compare costs | Essential | Essential |
The application channel changes, but responsible borrowing principles remain the same.
H2: Pros and Cons of Mobile-First Borrowing
Pros
- Convenient application process
- Can be completed remotely
- Easy access to loan information
- Digital document submission may be available
- Faster communication in some cases
- Convenient repayment tracking
Cons
- Scams and impersonation risks
- Easy access may encourage impulsive borrowing
- Terms may be overlooked
- Privacy concerns require attention
- Fees can differ between products
- Digital convenience does not guarantee affordability
H2: Step-by-Step Safe Digital Loan Application
Step 1: Identify your financial requirement
Decide why you need the loan and how much is genuinely required.
Step 2: Review your budget
Calculate income, expenses and existing EMIs.
Step 3: Research lenders
Verify the actual lender and its official channels.
Step 4: Compare loan costs
Review interest, fees, tenure and total repayment.
Step 5: Check eligibility
Make sure your income and employment information meet the stated requirements.
Step 6: Submit accurate information
Never exaggerate salary or employment details.
Step 7: Review the offer
Check the complete loan terms before accepting.
Step 8: Read the agreement
Pay particular attention to repayment and charges.
Step 9: Accept only if affordable
If the EMI creates financial stress, reconsider the loan amount or borrowing decision.
Step 10: Keep records
Save the agreement, repayment schedule and official communications.
H2: Real-World Example
Consider Rahul, a salaried employee earning ₹45,000 per month.
He needs ₹1,00,000 for a genuine financial requirement.
Before applying, Rahul checks:
- His monthly expenses
- Existing EMI of ₹6,000
- Available monthly surplus
- His credit profile
- Potential loan costs
- Lender identity
- Repayment period
He compares the complete cost instead of choosing the first loan advertisement he sees.
This approach does not guarantee approval, but it can help him make a more informed borrowing decision.
H2: Expert Commentary: What Should Borrowers Focus On?
The safest approach to digital borrowing is to treat a smartphone application as a financial transaction, not simply an app download.
A responsible borrower should focus on three questions:
1. Who is lending the money?
Know the actual lender.
2. How much will I repay?
Look beyond the advertised rate and understand the complete cost.
3. Can I comfortably repay it?
Consider the EMI alongside your existing financial commitments.
These three questions can prevent many avoidable borrowing mistakes.
H2: Key Takeaways
- Verify the actual lender before applying.
- Salary alone does not determine loan eligibility.
- Check your existing EMIs and monthly expenses.
- Borrow only what you genuinely need.
- Compare the total cost instead of only the interest rate.
- Protect OTPs, PINs, passwords and banking credentials.
- Read the loan agreement before accepting.
- Save your repayment schedule and loan documents.
- Be cautious of guaranteed-approval claims and suspicious payment requests.
- Use official channels for applications and support.
- Digital convenience should never replace financial due diligence.
H2: Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should independently review applicable eligibility criteria, costs, terms and repayment obligations before accepting any loan.
Frequently Asked Questions
1. What is a loan eligibility safety checklist?
It is a list of checks borrowers can complete before applying for or accepting a loan, covering lender verification, affordability, costs, privacy and repayment terms.
2. Is digital lending automatically safe?
No. Borrowers should verify the lender, use official channels and review the complete loan terms.
3. Can salaried employees apply for loans using a mobile phone?
Yes, many lenders offer digital application channels, subject to their eligibility and verification requirements.
4. Does salary guarantee loan approval?
No. Income is only one factor that may be considered during the lender's assessment.
5. Should I check my EMI before taking a loan?
Yes. EMI affordability should be evaluated against your income, expenses and existing financial commitments.
6. What should I check before accepting an online loan?
Check the lender, interest rate, applicable fees, total repayment, EMI, tenure, repayment dates and contractual terms.
7. Can I share my OTP with a loan agent?
No. Never share OTPs, PINs or passwords with unknown individuals.
8. Is a guaranteed loan approval claim safe?
Borrowers should be cautious about guaranteed-approval claims, especially when they are combined with pressure to pay unexplained fees or share sensitive information.
9. Can existing EMIs affect loan eligibility?
Yes. Existing obligations can affect the lender's assessment of repayment capacity.
10. Should first-time digital borrowers take extra precautions?
Yes. First-time borrowers should carefully verify the lender, compare costs, understand the agreement and protect their personal information.
11. Is the lowest interest rate always the cheapest loan?
Not necessarily. Applicable fees and other costs can affect the overall cost of borrowing.
12. Can I apply for multiple digital loans at the same time?
Borrowers should avoid unnecessary applications and compare options first. Multiple formal credit enquiries may affect the borrower's credit profile depending on the reporting process.
13. What documents may salaried employees need?
Requirements vary, but lenders may request identity, address, income, employment and banking information.
14. What should I do if a digital loan offer looks suspicious?
Stop the application and independently verify the lender and communication through official channels. Do not share sensitive information until the service has been verified.
15. How can I borrow safely online?
Verify the lender, check affordability, compare total costs, protect personal information, read the agreement and maintain repayment discipline.
Conclusion
For salaried employees, mobile-first borrowing can make the loan application process convenient, but convenience should never replace caution.
The safest digital borrower is one who verifies the lender, understands the complete cost, checks EMI affordability, protects personal information and reads the agreement before accepting the loan.
Use this checklist every time you consider a digital loan, especially if you are a first-time borrower.
Published on : 18th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed