

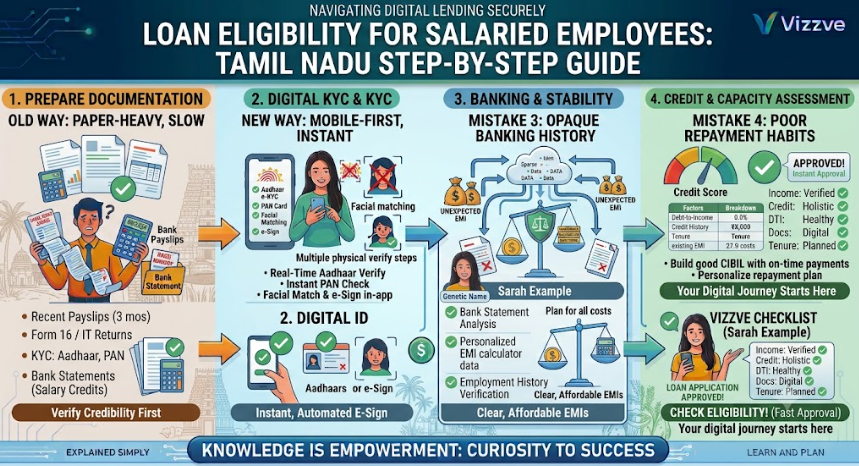
Introduction
A personal loan can help salaried employees manage planned expenses, emergencies or other financial needs. But before applying, it is important to understand how lenders assess eligibility.
For salaried employees in Tamil Nadu, factors such as monthly income, employment stability, credit history, existing EMIs, age, documents and repayment capacity can influence the assessment.
This guide explains the process in simple steps so you can prepare before submitting a loan application.
Quick answer: Start by checking your take-home salary, existing EMIs and credit history. Then estimate an affordable EMI, prepare your documents, compare loan costs and apply only after verifying the lender and loan terms.
AI Answer Box: How Can Salaried Employees Check Loan Eligibility?
Salaried employees can check loan eligibility by reviewing:
- Monthly take-home salary
- Existing loan EMIs
- Credit history
- Employment stability
- Age and loan tenure
- Required documents
- Repayment capacity
- Loan amount requested
- Total cost of the proposed loan
Important: There is no single eligibility formula used by every lender. Final approval depends on the lender's policies, verification and overall assessment.
Step-by-Step Guide to Loan Eligibility for Salaried Employees
Step 1: Check Your Monthly Take-Home Salary
Start with the salary actually credited to your bank account.
Do not rely only on annual CTC when planning your repayment capacity.
For example, your CTC may include components that do not reach your bank account every month. Your actual take-home income gives you a better starting point for budgeting.
What to check
- Monthly net salary
- Salary-credit consistency
- Regular deductions
- Other stable income, where accepted by the lender
Step 2: Calculate Your Existing EMIs
The next step is to identify your current debt obligations.
Include:
- Personal-loan EMIs
- Home-loan EMIs
- Vehicle-loan EMIs
- Education-loan EMIs
- Other reported loan obligations
- Credit-card repayment obligations, where applicable
Why does this matter?
A person earning ₹50,000 with ₹5,000 in existing EMIs has a different repayment position from someone earning ₹50,000 with ₹20,000 in existing EMIs.
Salary alone does not determine affordability.
Step 3: Check Your Credit History
Before applying, review your credit report.
A credit report can show information about your existing and previous credit accounts and repayment behaviour.
Look for:
- Overdue payments
- Incorrect account information
- Unknown accounts
- Incorrect outstanding balances
- Multiple recent credit enquiries
Simple tip
If you find an error, consider getting it corrected with the relevant credit information company before making a new application.
Step 4: Review Your Employment Stability
Employment stability can be important because the lender needs to assess the reliability of your income.
You may be asked about:
- Current employer
- Employment tenure
- Job type
- Salary
- Previous employment
- Probation status
Someone who has recently changed jobs may still qualify, but eligibility criteria can vary between lenders.
Step 5: Check Your Age and Desired Tenure
Age can affect the available loan tenure.
A longer tenure may reduce the monthly EMI, but it can also increase the total interest paid over the life of the loan.
Example
| Tenure | General Effect |
|---|---|
| Shorter tenure | Higher EMI, potentially lower total interest |
| Longer tenure | Lower EMI, potentially higher total interest |
Choose a tenure based on affordability rather than simply selecting the longest available option.
Step 6: Estimate Your Affordable EMI
This is one of the most important steps.
Before deciding the loan amount, calculate how much you can comfortably pay every month.
Consider:
- Rent
- Food
- Utilities
- Existing EMIs
- Insurance
- Family expenses
- Savings
- Emergency expenses
Simple illustration
Suppose:
- Take-home salary: ₹50,000
- Existing EMIs: ₹10,000
- Essential monthly expenses: ₹25,000
That leaves approximately ₹15,000 before considering savings and other unexpected costs.
A borrower should not automatically use the entire remaining amount for a new EMI.
Step 7: Decide the Loan Amount
Once you understand your monthly budget, decide how much you actually need.
Avoid borrowing more simply because you are eligible for a larger amount.
Ask yourself:
- How much money do I actually need?
- Can I repay the EMI comfortably?
- Will I still have emergency savings?
- What will the total repayment be?
- Is the loan necessary right now?
A higher approved amount does not automatically mean a better loan.
Step 8: Prepare Your Documents
The exact documents depend on the lender, but salaried applicants may commonly be asked for:
Identity
- PAN
- Aadhaar or another accepted identity document
- Address proof, where required
Income
- Recent salary slips
- Bank statements
- Form 16 or other income documents, where applicable
Employment
- Employer information
- Employment tenure
- Verification details, if required
Always provide genuine and up-to-date documents.
Step 9: Compare the Total Loan Cost
Don't compare loans based only on the advertised interest rate.
Check:
| Cost | What to Check |
|---|---|
| Interest rate | How interest is calculated |
| Processing fee | Amount charged for processing |
| Taxes | Applicable taxes on fees/services |
| Late-payment charges | Cost of missed payments |
| Prepayment charges | Conditions for early repayment |
| Foreclosure charges | Applicable conditions |
| Other fees | Any additional disclosed charges |
Read the loan agreement and applicable disclosures before accepting the offer.
Step 10: Verify the Lender Before Applying
For online applications, verify who is providing the loan.
Before submitting sensitive information:
- Check the lender's identity.
- Review the website or official application.
- Read the privacy policy.
- Review the loan terms.
- Check the applicable fees.
- Understand what personal information is being requested.
- Never share OTPs or passwords with unauthorised people.
Be cautious of websites or individuals promising guaranteed approval in exchange for upfront payments or unnecessary personal information.
Step 11: Submit Accurate Information
Your application should match your actual financial situation.
Do not:
- Inflate your salary.
- Misrepresent your employer.
- Provide fake documents.
- Hide existing loans.
- Use someone else's financial information.
Accurate information helps the lender conduct proper verification.
Step 12: Review the Final Offer
Before accepting a loan, check:
- Approved amount
- Interest rate
- EMI
- Loan tenure
- Processing fee
- Total repayment
- Repayment schedule
- Late-payment terms
- Prepayment/foreclosure conditions
- Other applicable charges
Don't accept an offer simply because the application was approved.
Loan Eligibility Factors at a Glance
| Factor | Why It Matters |
|---|---|
| Monthly income | Helps assess repayment capacity |
| Credit history | Indicates previous repayment behaviour |
| Existing EMIs | Shows current debt burden |
| Employment | Helps assess income stability |
| Age | Can influence available tenure |
| Bank statements | May verify salary and transactions |
| Loan amount | Determines repayment obligation |
| Tenure | Influences EMI and total interest |
| Documents | Support identity and income verification |
Example: How Two Salaried Employees Can Have Different Eligibility
Consider two employees:
| Details | Employee A | Employee B |
|---|---|---|
| Monthly salary | ₹50,000 | ₹50,000 |
| Existing EMIs | ₹5,000 | ₹18,000 |
| Employment | Stable | Stable |
| Credit history | Healthy | Healthy |
Although both earn the same salary, Employee A may have greater available income for another repayment obligation.
This is only an illustration. Actual eligibility depends on the lender's assessment.
Pros and Cons of Taking a Personal Loan
Pros
- Quick access to funds when eligible
- Predictable EMI structure
- No need to provide collateral for many unsecured personal loans
- Digital application may reduce paperwork
- Useful for certain planned financial needs
Cons
- Interest increases the total repayment
- Existing EMIs can create financial pressure
- Processing and other charges may apply
- Missed payments can affect credit history
- Borrowing more than necessary can strain your budget
Common Mistakes to Avoid
1. Looking Only at Salary
Income is important, but existing debt and credit history also matter.
2. Choosing the Maximum Eligible Amount
Eligibility is not the same as affordability.
3. Ignoring the Total Cost
A loan with a low headline rate may still involve other charges.
4. Applying Without Checking Credit History
Errors or overdue accounts may affect the assessment.
5. Giving Incorrect Information
False information can create verification problems.
6. Ignoring Data Privacy
Understand how your personal and financial information will be collected and used.
7. Taking a Longer Tenure Without Comparing Total Interest
A lower EMI can come with a higher overall interest cost.
How to Improve Loan Eligibility
You can work on several factors before applying.
Maintain Timely Payments
Pay existing loans and credit-card bills on time.
Reduce Unnecessary Debt
Lowering existing obligations can improve your available repayment capacity.
Maintain Accurate Credit Information
Review your credit report and dispute genuine errors.
Avoid Unnecessary Applications
Compare options before submitting multiple formal applications.
Keep Documents Ready
Accurate salary slips and bank statements can make verification easier.
Choose an Appropriate Loan Amount
Borrow only what is necessary and affordable.
Expert Perspective: Eligibility vs Affordability
A lender's approval decision and your personal affordability are two different things.
A borrower might qualify for a loan but still find the EMI uncomfortable after paying rent, household expenses, insurance and other commitments.
A responsible borrowing decision should therefore answer two questions:
Can I qualify for this loan?
and
Can I comfortably repay this loan?
The second question is equally important.
Key Takeaways
- Start with your actual take-home salary.
- List all existing EMIs.
- Check your credit report before applying.
- Consider employment stability.
- Estimate an affordable EMI.
- Borrow only what you need.
- Prepare accurate documents.
- Compare total loan costs.
- Verify the lender before sharing personal information.
- Read the loan agreement before accepting.
- Remember that eligibility does not guarantee approval.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should review the applicable eligibility criteria, interest rate, charges, repayment schedule, terms and privacy information before applying.
Frequently Asked Questions
1. How can salaried employees check loan eligibility in Tamil Nadu?
Check your salary, existing EMIs, credit history, employment stability, age, documents and repayment capacity. The final assessment depends on the lender.
2. How much personal loan can I get based on my salary?
There is no universal amount. The eligible amount depends on income, existing obligations, credit profile, tenure and lender-specific policies.
3. Does my credit score affect personal loan eligibility?
Yes. Credit history can be an important part of the lender's assessment, although requirements vary.
4. Do existing EMIs reduce loan eligibility?
They can. Existing EMIs reduce the income available for additional repayment obligations.
5. What documents do salaried employees need for a personal loan?
Depending on the lender, documents may include PAN, identity/address proof, salary slips, bank statements and income or employment documents.
6. Can a newly employed person apply for a personal loan?
Possibly. Lenders may have minimum employment-tenure or income requirements.
7. Does changing jobs affect loan eligibility?
It can. Employment tenure and income stability may be considered during the assessment.
8. Is there a minimum salary requirement?
Some lenders have minimum income requirements, but these differ according to lender, product and applicant profile.
9. How can I improve my personal loan eligibility?
Maintain timely repayments, manage existing debt, keep your credit information accurate and choose a suitable loan amount.
10. Is online personal loan application safe?
It can be when using a legitimate and verified lender or platform. Always check the lender, loan terms, privacy information and application permissions.
11. Should I apply to several lenders at the same time?
It is better to compare suitable options first and avoid unnecessary formal applications.
12. Can a good salary guarantee loan approval?
No. Lenders consider several factors and conduct their own verification before making a final decision.
13. Does loan tenure affect eligibility?
Tenure affects the EMI and total repayment. The lender may also consider age and other factors when determining available tenure.
14. Can I improve eligibility by taking a longer tenure?
A longer tenure can lower the monthly EMI, but it may increase total interest. It should be selected based on affordability.
15. What should I check before accepting a loan?
Review the interest rate, EMI, tenure, processing fee, total repayment, other charges, prepayment conditions and loan agreement.
Published on : 27th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed