

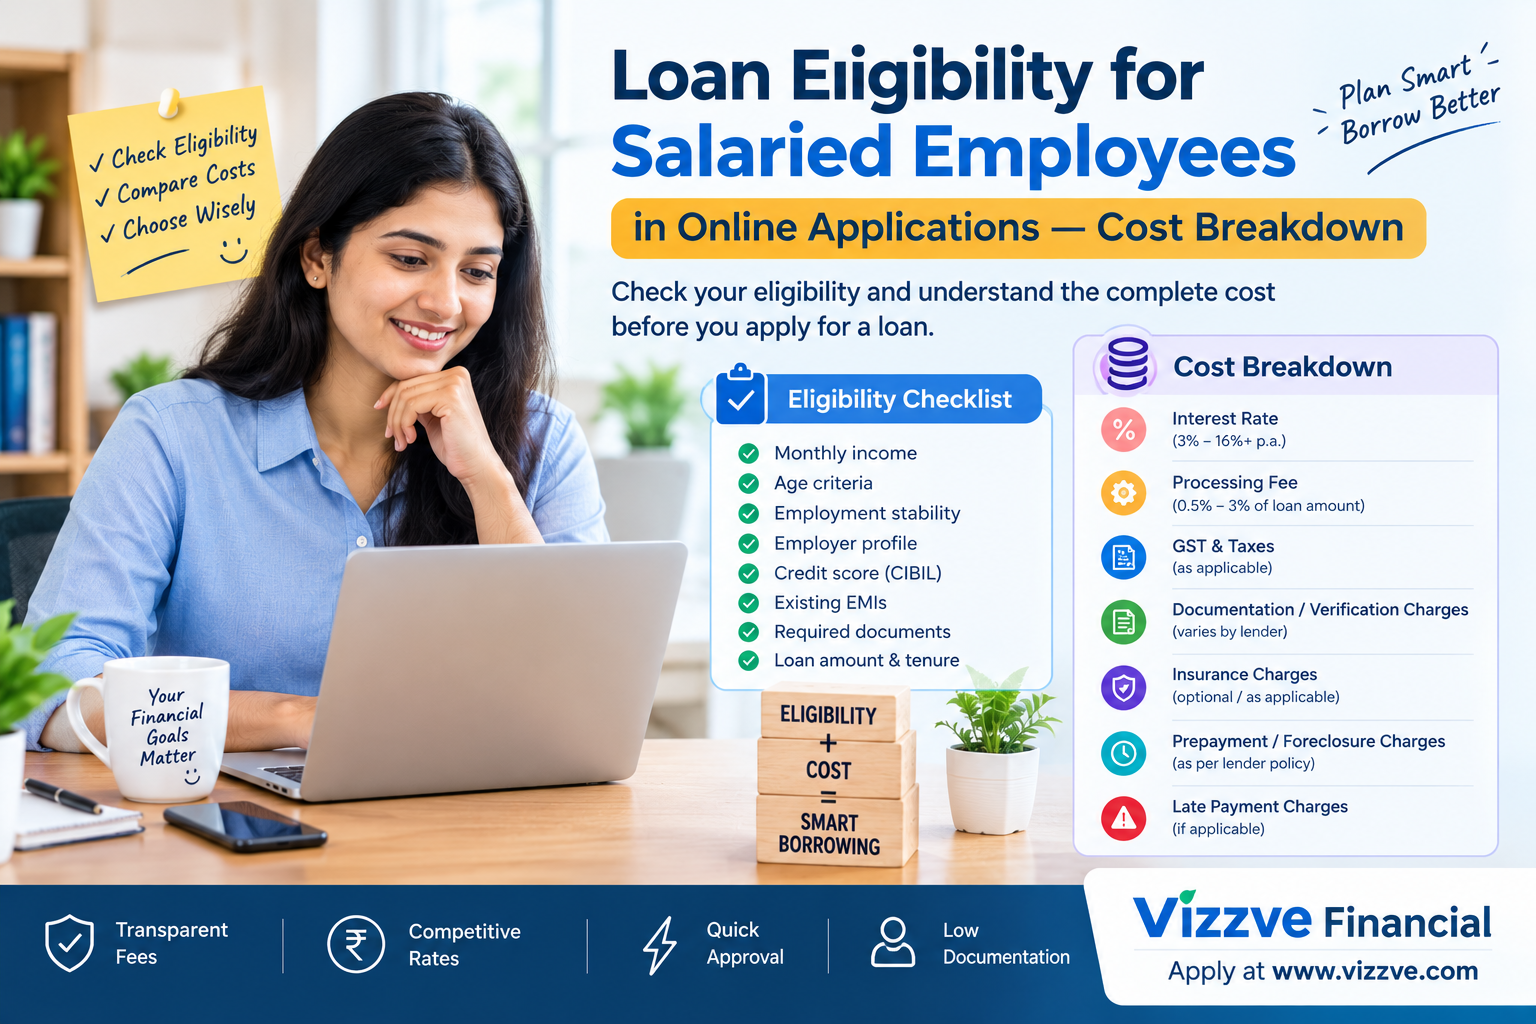
For salaried employees, applying for a loan online can be convenient because eligibility checks, document submission, verification, approval and disbursal may happen digitally.
However, loan eligibility is only one part of the decision.
A borrower should also understand the total cost of the loan before accepting an offer. The final cost can include interest, processing fees, applicable taxes, documentation or verification charges, insurance where applicable, prepayment or foreclosure charges where applicable, and charges related to delayed repayment.
The important question is not simply:
“How much loan can I get?”
It is:
“How much will this loan actually cost me from application to final repayment?”
For online lending, the Reserve Bank of India (RBI) requires regulated entities to provide important loan information through a Key Facts Statement (KFS). The KFS includes the Annual Percentage Rate (APR), repayment schedule and applicable charges, helping borrowers understand the overall cost before entering into the loan contract.
What is the cost of an online loan for a salaried employee?
The cost of an online loan generally includes the interest payable over the loan tenure plus applicable processing fees, taxes and other disclosed charges. The exact cost depends on the lender, loan amount, interest rate, tenure, borrower profile and repayment history.
What determines loan eligibility for salaried employees?
Lenders commonly consider:
- Monthly income
- Age
- Employment stability
- Employer profile
- Credit history and credit score
- Existing EMIs
- Monthly repayment capacity
- Banking history
- Loan amount requested
- Loan tenure
- Required documents
How can borrowers compare loan costs?
Do not compare interest rates alone. Check the KFS, APR, total interest, processing fee, applicable taxes, net amount disbursed, EMI, repayment schedule and other applicable charges.
What Is Loan Eligibility for Salaried Employees?
Loan eligibility refers to the conditions a lender uses to determine whether a salaried applicant qualifies for a loan and how much credit may be offered.
There is no single universal salary or credit-score threshold applicable to every lender.
Eligibility can depend on several factors.
Key Loan Eligibility Factors
| Factor | Why It Matters |
|---|---|
| Monthly salary | Indicates repayment capacity |
| Employment stability | Shows income continuity |
| Employer profile | May influence lender risk assessment |
| Credit history | Indicates previous borrowing behaviour |
| Existing EMIs | Affects disposable income |
| Age | Helps determine suitable loan tenure |
| Bank statements | Help verify income and cash flow |
| Loan amount | Determines repayment obligation |
| Loan tenure | Affects EMI and total interest |
| Documents | Help verify applicant information |
A salaried employee with stable income and manageable existing debt may have a different eligibility outcome from another applicant with the same salary but higher existing obligations.
Understanding the Cost Breakdown of an Online Loan
The total borrowing cost is more than the advertised interest rate.
A practical cost breakdown can include the following components:
- Principal amount
- Interest
- Processing fee
- Applicable GST/taxes on taxable charges
- Documentation or verification charges, if applicable
- Insurance or third-party charges, if applicable
- Prepayment or foreclosure charges, where applicable
- Penal charges for certain defaults or contractual non-compliance
- Other charges specifically disclosed in the loan documents
The exact applicability depends on the lender and product.
1. Principal Amount
The principal is the amount borrowed.
For example:
Loan sanctioned: ₹5,00,000
This does not necessarily mean ₹5,00,000 reaches the borrower's bank account.
If applicable upfront fees are deducted from the disbursement, the net amount received may be lower.
Example
Suppose:
- Sanctioned loan = ₹5,00,000
- Processing fee = ₹5,000
- Applicable tax on fee = ₹900
The borrower could receive approximately:
₹5,00,000 − ₹5,000 − ₹900 = ₹4,94,100
This is only an illustration. Actual charges and taxes depend on the lender and applicable tax treatment.
2. Interest Cost
Interest is generally the largest component of borrowing cost.
The total interest depends on:
- Loan amount
- Interest rate
- Tenure
- Repayment method
- Rate type
- Outstanding principal over time
A longer tenure may reduce the monthly EMI but can increase the total interest paid.
Example
Consider an illustrative loan:
- Loan amount: ₹5,00,000
- Interest rate: 14% per annum
- Tenure: 3 years
The EMI and total interest can be calculated using the lender's applicable repayment methodology.
The key point is that a borrower should look at total interest over the full tenure, not just the monthly EMI.
3. Processing Fee
A processing fee is a charge associated with processing the loan application.
It may be:
- A fixed amount
- A percentage of the sanctioned loan
- Subject to a minimum or maximum amount
- Different for different loan products
For example, if a lender charges a hypothetical 2% processing fee on a ₹5 lakh loan:
₹5,00,000 × 2% = ₹10,000
If applicable taxes are added to the fee, the actual deduction may be higher.
Always check the lender's current fee schedule and KFS before accepting the offer.
4. GST and Applicable Taxes
Taxes may apply to certain loan-related services or charges.
Importantly, GST treatment should not be assumed to apply identically to the entire loan amount.
For example, the principal borrowed is not simply treated as a service fee on which GST is calculated. Tax treatment can differ depending on the nature of the charge.
Therefore, borrowers should check the tax component separately in the loan documents.
5. Documentation and Verification Charges
Some lenders may have documentation, verification or other administrative charges depending on the product.
For an online loan, many processes can be completed digitally, but that does not automatically mean every lender has zero additional charges.
Check the KFS and sanction documents for:
- Documentation fee
- Verification fee
- Mandate-related charges
- Service charges
- Other administrative charges
Do not rely only on an advertisement saying “low documentation.”
6. Insurance Charges
Some loans may involve insurance or other third-party products.
If insurance is offered or required as part of a particular loan arrangement, the borrower should check:
- Premium amount
- Whether it is optional or mandatory
- Coverage
- Policy term
- Insurer
- Whether the premium is financed or paid separately
The cost should be understood before signing the agreement.
RBI's KFS framework requires applicable charges recovered on behalf of third-party service providers to be disclosed in the relevant circumstances.
7. Late Payment and Penal Charges
Missing an EMI can result in charges according to the loan agreement.
RBI's fair-lending framework states that penal charges for non-compliance with material terms and conditions should be reasonable and appropriately disclosed. Penal charges should not be structured as additional penal interest added to the contracted interest rate, and they should not be capitalised.
Therefore, borrowers should check:
- Due date
- Grace period, if any
- Late-payment charges
- Penal charges
- Bounce charges, if applicable
- How a default may affect credit reporting
Practical Tip
Set up sufficient balance in the repayment account before the EMI due date and use reminders or automatic payment arrangements where appropriate.
8. Prepayment and Foreclosure Charges
A borrower may want to repay a loan earlier than scheduled.
Depending on the loan type and lender, there may be conditions or charges related to:
- Part-prepayment
- Full prepayment
- Foreclosure
- Minimum lock-in period
Rules can vary based on the type of loan and interest-rate structure.
For example, RBI's framework states that certain regulated entities cannot charge foreclosure/prepayment penalties on floating-rate term loans sanctioned to individual borrowers for non-business purposes, subject to the applicable regulatory framework.
Always check the specific loan agreement rather than assuming that every loan has identical prepayment rules.
Cost Breakdown Example for a Salaried Employee
Consider an illustrative online personal loan.
| Cost Component | Example |
|---|---|
| Sanctioned loan | ₹5,00,000 |
| Interest rate | 14% p.a. |
| Tenure | 36 months |
| Processing fee | ₹5,000 |
| Applicable tax on fee | ₹900 |
| Net initial amount received* | ₹4,94,100 |
| EMI | Depends on lender calculation |
| Total interest | Depends on repayment schedule |
| Total repayment | Principal + applicable interest |
| Other charges | As disclosed in KFS |
*Illustration only. Actual deductions and tax treatment vary.
The important point is that ₹5 lakh sanctioned does not necessarily mean ₹5 lakh is the amount available for spending if upfront charges are deducted from disbursement.
How to Calculate the Real Cost of a Personal Loan
A simple way to understand borrowing cost is:
Total Loan Cost
Total loan cost = Total repayments + upfront charges + applicable other charges − principal amount received
For a more precise comparison, examine the APR disclosed in the KFS, along with the amortisation schedule.
RBI's framework defines APR as an effective annualised cost and requires relevant charges to be reflected according to the applicable KFS rules.
Interest Rate vs APR: What Should Salaried Applicants Check?
Many applicants focus on the interest rate displayed on a loan website.
But the interest rate alone may not capture the complete cost.
| Factor | Interest Rate | APR |
|---|---|---|
| Shows borrowing interest | Yes | Reflected |
| Helps compare loan pricing | Yes | More comprehensive |
| Considers applicable charges | Not necessarily | Designed to reflect relevant costs |
| Appears in KFS | Yes, where applicable | Yes |
| Useful for total-cost comparison | Limited alone | More useful |
For digital lending, RBI requires the APR to be disclosed upfront and included in the KFS.
Why KFS Is Important for Online Loan Applicants
The Key Facts Statement (KFS) is one of the most important documents to review before accepting a loan.
It can help the borrower understand:
- Loan amount
- Loan tenure
- Interest rate
- APR
- EMI/EPI
- Repayment schedule
- Fees and charges
- Penal charges
- Other important terms
RBI guidance requires regulated entities to provide a KFS to prospective borrowers under the applicable framework. For digital lending, the KFS includes APR and other important information before the contract is executed.
What if a charge is missing?
Under the digital lending framework, fees and charges that are not included in the KFS generally cannot later be charged by the regulated entity during the loan term, subject to the applicable regulatory provisions.
This makes the KFS an important document for checking the cost before acceptance.
Online Loan Cost vs Offline Loan Cost
Online and offline loans can have similar underlying costs. The difference is often in the application and servicing process.
| Factor | Online Application | Offline Application |
|---|---|---|
| Application | Digital | Branch/physical or assisted |
| Document submission | Often digital | Physical or digital |
| Verification | Often digitally supported | May involve branch/assisted verification |
| Approval communication | Usually digital | Digital/physical |
| KFS | Should be provided where applicable | Should be provided where applicable |
| Cost | Lender/product dependent | Lender/product dependent |
| Convenience | Usually high | Depends on lender |
Online does not automatically mean cheaper. Compare the actual cost rather than choosing based only on convenience.
Cost Breakdown by Stage
Before Application
Possible considerations:
- Credit report access or related services, if applicable
- No-cost eligibility checks offered by some lenders
- Documentation requirements
- Potential application-related fees
Always verify whether an advertised “free eligibility check” is genuinely free.
At Approval and Disbursement
Potential costs include:
- Processing fee
- Applicable taxes
- Verification charges
- Third-party charges
- Insurance, where applicable
During Repayment
The main costs are:
- EMI
- Interest
- Applicable service charges
- Penal charges after qualifying default/non-compliance
At Prepayment or Closure
Possible considerations:
- Prepayment/foreclosure conditions
- Applicable charges
- Closure documentation
Loan Eligibility Checklist for Salaried Employees
Before applying online, check the following.
Income
- Is your monthly income stable?
- Can your salary support another EMI?
- Do you have substantial existing deductions?
Employment
- Are you employed with a stable organisation?
- Have you completed the required employment period?
- Can you provide employment and income proof?
Credit Profile
- Is your credit history accurate?
- Do you have outstanding overdue accounts?
- Are existing EMIs being paid on time?
Documents
Keep commonly requested documents ready:
- PAN
- Aadhaar or other acceptable KYC documents
- Salary slips
- Bank statements
- Employment details
- Address proof, where required
The exact document list varies by lender.
How Existing EMIs Affect Loan Eligibility and Cost
Existing debt can affect both eligibility and affordability.
For example, suppose:
- Monthly take-home salary = ₹60,000
- Existing EMIs = ₹20,000
- New proposed EMI = ₹15,000
Total monthly EMI obligation would become:
₹20,000 + ₹15,000 = ₹35,000
That leaves ₹25,000 before considering other household expenses.
The lender may assess repayment capacity using its own underwriting criteria.
Real-World Experience Point
An applicant may qualify for a certain loan amount based on income but still find that the resulting EMI is uncomfortable after rent, food, utilities, insurance and existing obligations.
Eligibility and affordability are not the same thing.
Shorter Tenure vs Longer Tenure
Tenure can significantly influence total borrowing cost.
| Feature | Shorter Tenure | Longer Tenure |
|---|---|---|
| Monthly EMI | Usually higher | Usually lower |
| Total interest | Generally lower if other terms remain the same | Generally higher |
| Repayment period | Shorter | Longer |
| Monthly cash-flow pressure | Higher | Lower |
| Overall interest burden | Often lower | Often higher |
The appropriate tenure depends on the borrower's repayment capacity and the lender's available options.
Pros and Cons of Applying for a Loan Online
Pros
- Convenient application process
- Digital document submission
- Faster communication in many cases
- Easy access to loan information
- Convenient repayment tracking
- Reduced need for branch visits
Cons
- Easy application can encourage unnecessary borrowing
- Applicants may focus too heavily on EMI
- Digital advertisements may highlight starting rates rather than the full cost
- Fees can differ between lenders
- Fraudulent loan apps can create security risks
- Borrowers may accept terms without reading the KFS
Step-by-Step: How Salaried Employees Can Check Loan Cost Online
Step 1: Check Your Monthly Budget
Calculate:
Take-home salary − essential expenses − existing EMIs = available repayment capacity
Do not use your entire disposable income for a new EMI.
Step 2: Check Your Credit Profile
Review your credit history for:
- Incorrect accounts
- Overdue payments
- High outstanding balances
- Unauthorised enquiries
Step 3: Estimate the Required Amount
Borrow only the amount required for the intended purpose.
A larger loan can increase both EMI and total interest.
Step 4: Compare Loan Offers
Compare:
- Interest rate
- APR
- Processing fee
- Applicable taxes
- EMI
- Tenure
- Total interest
- Prepayment terms
- Penal charges
Step 5: Read the KFS
Do not skip the KFS.
Check every fee and the repayment schedule before accepting.
Step 6: Verify the Lender
For digital lending, verify the regulated entity behind the loan and review the lender's official disclosures.
Step 7: Accept Only After Understanding the Cost
A lower EMI is not necessarily a lower total cost.
Look at the complete repayment obligation.
Common Mistakes Salaried Applicants Should Avoid
1. Looking Only at the Interest Rate
A loan with a slightly lower advertised rate may still have different fees.
2. Choosing the Highest Eligible Amount
Being eligible for a larger amount does not mean you need to borrow it.
3. Ignoring Processing Fees
Even a small percentage can become a meaningful amount on a large loan.
4. Not Checking the Net Disbursement
The sanctioned amount and amount credited can differ when applicable upfront charges are deducted.
5. Ignoring the KFS
The KFS is designed to make important loan terms easier to understand.
6. Missing EMI Due Dates
Late payments can create additional costs and may affect your credit profile.
7. Accepting Unclear Digital Loan Offers
Never transfer money to an unknown person merely because someone promises guaranteed loan approval.
How to Make an Online Loan More Affordable
Borrowers can reduce unnecessary borrowing costs by:
- Comparing multiple eligible offers
- Choosing a suitable loan amount
- Selecting a tenure based on affordability
- Maintaining a healthy credit profile
- Paying EMIs on time
- Checking processing and other fees
- Reviewing the KFS
- Comparing APR rather than interest rate alone
- Understanding prepayment terms
- Avoiding unnecessary add-on products
- Borrowing only for a genuine financial need
Expert Commentary: What Matters Beyond Eligibility?
A useful loan decision should answer three questions:
1. Can I qualify?
This depends on lender-specific eligibility criteria.
2. Can I afford the EMI?
This depends on income, expenses and existing obligations.
3. What is the total cost?
This requires looking beyond the EMI and checking interest, fees, taxes and other applicable charges.
For online applicants, the third question is especially important because a digital application can make borrowing extremely convenient. Convenience should not replace careful cost comparison.
Summary Cost Checklist
| Cost/Term | What to Check |
|---|---|
| Principal | Amount actually borrowed |
| Interest rate | Fixed/floating and applicable rate |
| APR | Overall annualised cost according to applicable framework |
| Processing fee | Fixed amount or percentage |
| Taxes | Applicable tax on taxable charges |
| Insurance | Whether applicable/optional |
| Verification charges | Whether charged |
| EMI | Monthly repayment |
| Total interest | Interest over the tenure |
| Penal charges | Default/non-compliance charges |
| Prepayment | Conditions and applicable charges |
| Net disbursement | Actual amount received |
| Total repayment | Overall scheduled repayment |
Quick Comparison: Which Cost Should You Focus On?
| If You See... | Also Check... |
|---|---|
| Low interest rate | Processing fee + APR |
| Low EMI | Total interest + tenure |
| High eligible amount | Your actual requirement |
| Instant approval | Total cost + lender identity |
| Zero paperwork | KFS and actual terms |
| Low processing fee | Interest + other charges |
| Short tenure | EMI affordability |
| Long tenure | Total interest |
Vizzve Financial: Online Loan Support
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before applying, applicants should independently review the applicable lender, loan terms, KFS, APR, fees and repayment obligations.
Frequently Asked Questions
1. What is loan eligibility for salaried employees?
Loan eligibility is the set of criteria a lender uses to determine whether a salaried applicant qualifies for a loan and the amount that may be offered.
2. What salary is required for an online personal loan?
There is no single salary requirement applicable to every lender. Minimum income requirements vary according to the lender and loan product.
3. Does a higher salary reduce loan cost?
Not automatically. A higher income may improve repayment capacity, but the final interest rate and fees depend on the lender's assessment and product terms.
4. What is included in the cost of an online loan?
The cost may include interest, processing fees, applicable taxes and other disclosed charges. Penal or contingent charges may apply separately when relevant.
5. Is the online loan processing fee refundable?
Refund rules depend on the lender and circumstances. Check the loan agreement and KFS before paying or accepting the loan.
6. Does GST apply to personal loan processing fees?
Applicable tax treatment can depend on the nature of the charge. Borrowers should check the tax component shown in the lender's documentation.
7. What is APR in a personal loan?
APR is an annualised measure designed to represent the applicable overall cost of credit under the relevant regulatory framework. For digital lending, RBI requires APR disclosure through the KFS.
8. What is a KFS in an online loan?
KFS stands for Key Facts Statement. It summarises important loan terms such as applicable charges, APR, repayment details and other key information.
9. Is a low EMI always better?
Not necessarily. A longer tenure can reduce the monthly EMI while increasing the total interest paid over the life of the loan.
10. Can existing EMIs affect salaried employee loan eligibility?
Yes. Existing repayment obligations can affect how a lender assesses repayment capacity.
11. Can I repay my personal loan early?
Early repayment may be possible, but applicable conditions and charges depend on the loan and lender. Some regulatory restrictions apply to certain types of prepayment charges.
12. What happens if I miss an EMI?
Depending on the loan agreement, delayed payment can result in applicable charges and may affect your credit history. Review the lender's disclosed penal-charge policy.
13. How can I reduce my loan cost?
Compare eligible offers, review APR and fees, borrow only what you need, select a suitable tenure and make repayments on time.
14. Should I compare interest rates or APR?
Both are useful, but APR can provide a broader view of the applicable cost because it incorporates relevant charges under the applicable framework.
15. What should I check before accepting an online loan?
Check the lender, sanctioned amount, net disbursement, interest rate, APR, EMI, tenure, processing fee, applicable taxes, repayment schedule, penal charges and prepayment terms.
Published on : 02nd October
Published by : Shanlee JV
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed