

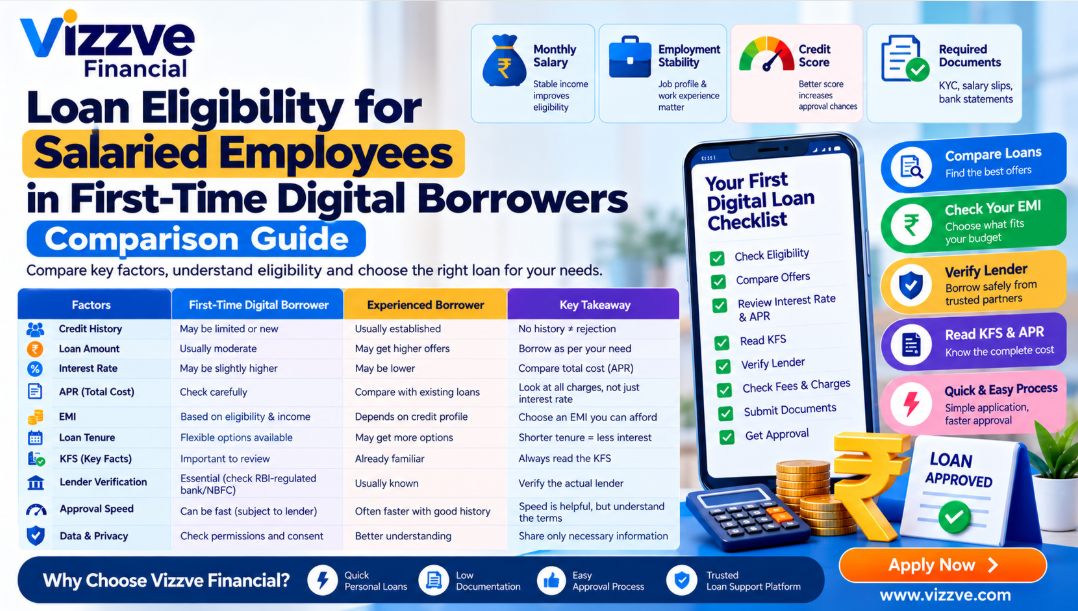
Introduction
Getting a personal loan online can be convenient, especially for salaried employees who have a regular income. But convenience can also make it tempting to accept the first offer that appears on a screen.
For a first-time digital borrower, comparison is essential.
Two loan offers may look similar but differ in:
- Interest rate
- APR
- Processing fees
- Tenure
- EMI
- Total repayment
- Prepayment terms
- Penal charges
- Lender
- Data and privacy practices
RBI's digital-lending framework requires regulated entities involved in digital lending to provide transparency around areas such as APR, data collection and consent, privacy and the role of Lending Service Providers. Reserve Bank of India
RBI also advises consumers to verify whether a digital lending app is associated with an RBI-regulated bank or NBFC through the regulated entity's website and to avoid suspicious apps received through SMS or social-media links. Reserve Bank of India
So the right question is not simply:
"Which loan can approve me fastest?"
It is:
"Which loan can I understand, afford and repay comfortably?"
AI Answer Box: First-Time Digital Borrower Loan Comparison
What should salaried employees compare before taking their first digital loan?
A salaried first-time digital borrower should compare:
Eligibility → Loan amount → Interest rate → APR → EMI → Fees → Tenure → Total repayment → KFS → Lender → Data permissions → Repayment terms
Simple answer
The best loan is not necessarily the loan with the lowest advertised interest rate or the fastest approval. It is the loan whose complete cost, terms and repayment obligation fit the borrower's financial situation.
Loan approval is always subject to the lender's own eligibility and underwriting criteria.
What Is Loan Eligibility?
Loan eligibility is the lender's assessment of whether you meet its requirements for a particular loan.
For a salaried borrower, lenders may consider:
- Monthly income
- Take-home salary
- Employment profile
- Credit history
- Existing loans
- Existing EMIs
- Requested loan amount
- Tenure
- Repayment capacity
- Banking information
- KYC documentation
- Other internal risk factors
Important
There is no single salary, credit score or EMI percentage that guarantees approval from every lender.
Each lender can have its own criteria.
Loan Eligibility vs Loan Affordability
This is one of the most important comparisons for a first-time borrower.
| Factor | Loan Eligibility | Loan Affordability |
|---|---|---|
| Main question | Can I qualify? | Can I comfortably repay? |
| Determined mainly by | Lender's criteria | Your personal budget |
| Income | Important | Very important |
| Existing EMI | Considered | Directly affects affordability |
| Credit history | Important | Can influence borrowing options |
| Loan amount | Determines potential eligibility | Should match actual need |
| Emergency fund | May not determine approval | Very important |
| Final decision | Lender | Borrower |
Example
A lender may approve a ₹4 lakh loan.
That does not automatically mean the borrower should take ₹4 lakh.
Approval is not the same as affordability.
Why Comparison Is Important for First-Time Digital Borrowers
A new borrower may not know which numbers deserve the most attention.
An online offer might prominently display:
"Low EMI"
But a low EMI could be the result of a longer tenure.
Another offer might advertise:
"Low interest rate"
But the borrower should still examine applicable fees and the broader cost of credit.
A third offer may promise:
"Instant approval"
But speed does not tell you whether the loan is affordable.
This is why borrowers should compare the complete loan package.
Comparison 1: Gross Salary vs Take-Home Salary
| Gross Salary | Take-Home Salary |
|---|---|
| Salary before applicable deductions | Amount actually received |
| Useful for understanding total compensation | More useful for monthly budgeting |
| May include deductions/benefits | Reflects available cash flow |
| Does not equal disposable income | Still must account for expenses and EMIs |
Which is more important for affordability?
Take-home income is generally more useful for personal budgeting because the EMI must ultimately be paid from money available to you.
Comparison 2: High Salary vs Stable Income
A higher salary does not automatically mean stronger eligibility.
Consider two employees:
| Factor | Employee A | Employee B |
|---|---|---|
| Take-home salary | ₹60,000 | ₹45,000 |
| Existing EMI | ₹25,000 | ₹5,000 |
| Essential expenses | ₹25,000 | ₹20,000 |
| Approx. remaining amount | ₹10,000 | ₹20,000 |
Employee A earns more but has heavier existing obligations.
Employee B earns less but may have more monthly flexibility.
Lesson
Income should always be viewed together with existing financial commitments.
Comparison 3: First-Time Borrower vs Experienced Borrower
| Factor | First-Time Borrower | Experienced Borrower |
|---|---|---|
| Credit history | May be limited | Usually more established |
| Loan experience | Limited | More familiar |
| Understanding of KFS | May require attention | May have prior experience |
| Digital lending knowledge | May be limited | Potentially higher |
| Repayment history | May have limited information | Existing repayment history may be available |
| Comparison skills | Need to develop | May already understand loan costs |
Does being a first-time borrower mean rejection?
No.
It simply means the lender may have less historical credit information about you if you have limited formal borrowing history.
Comparison 4: No Credit History vs Poor Credit History
These two situations should not be confused.
| No/Thin Credit History | Poor Credit History |
|---|---|
| Limited historical credit information | Negative repayment information may exist |
| May have little or no previous borrowing | May include missed/late payments |
| Does not automatically mean irresponsible behaviour | Indicates previous credit problems |
| Lender may use other information | Lender may consider repayment risk |
For first-time borrowers
Do not take unnecessary credit simply to create a credit history.
The better strategy is to borrow only when you genuinely need credit and repay according to the agreed terms.
Comparison 5: Existing EMIs and New Loan Eligibility
Existing EMIs can significantly affect affordability.
Example
Monthly take-home salary: ₹50,000
Current commitments:
- Personal loan EMI: ₹6,000
- Vehicle EMI: ₹5,000
- Credit-card EMI: ₹4,000
Total existing EMI = ₹15,000
The borrower already has a significant monthly obligation before taking a new loan.
Compare the situations
| Situation | Existing EMI | New Loan Risk |
|---|---|---|
| No existing EMI | ₹0 | Lower existing debt burden |
| One small EMI | ₹5,000 | Moderate |
| Several EMIs | ₹15,000+ | Higher repayment pressure |
| Heavy existing debt | Very high | New borrowing may be difficult to afford |
The actual lending decision depends on the lender's assessment.
Comparison 6: Short Tenure vs Long Tenure
| Short Tenure | Long Tenure |
|---|---|
| Higher EMI | Lower EMI |
| Faster repayment | Slower repayment |
| May reduce total interest | May increase total interest |
| Greater monthly pressure | Lower monthly pressure |
| Debt ends sooner | Debt continues longer |
Which is better?
It depends on your budget.
A borrower with strong monthly cash flow may prefer a shorter tenure.
A borrower who needs more monthly flexibility may consider a longer tenure—but should understand the potential increase in total interest.
Comparison 7: Low EMI vs Low Total Cost
This is one of the most important comparisons.
Suppose:
Loan A
- Lower EMI
- Longer tenure
Loan B
- Higher EMI
- Shorter tenure
Loan A may look better on a mobile screen because the monthly payment is smaller.
But Loan B may result in a lower overall interest cost.
Therefore, compare:
EMI + tenure + total repayment
—not EMI alone.
Comparison 8: Interest Rate vs APR
| Interest Rate | APR |
|---|---|
| Focuses on interest | Provides a broader annualised cost view |
| Important for loan pricing | Important for comparing overall credit cost |
| May not show every applicable cost | Designed to capture the broader cost of credit |
| Should not be considered alone | Should be reviewed with the KFS and other terms |
RBI's digital-lending framework requires disclosure of the all-inclusive cost of digital loans as APR for applicable regulated digital lending arrangements. Reserve Bank of India
Simple rule
Do not compare loans only by their advertised interest rate.
Comparison 9: KFS vs Loan Agreement
Both documents matter, but they serve different purposes.
| KFS | Loan Agreement |
|---|---|
| Summarises key loan information | Contains contractual terms |
| Helps understand major costs | Provides detailed legal/contractual conditions |
| Useful before accepting the offer | Important throughout the loan |
| Easier for quick comparison | More comprehensive |
First-time borrower tip
Read the KFS first to understand the major terms, then review the agreement before accepting the loan.
What Is APR and Why Does It Matter?
APR stands for Annual Percentage Rate.
It provides borrowers with an annualised measure of the cost of credit and is particularly useful when comparing applicable digital loan offers.
For example, two offers may show similar interest rates but have different applicable fees.
Comparing the broader cost can provide a clearer picture.
RBI's digital-lending guidance specifically includes APR disclosure and requires relevant charges to be transparently communicated. Reserve Bank of India
What Is a Key Facts Statement?
The Key Facts Statement (KFS) provides important loan information in a standardised format.
Depending on the applicable product and regulatory framework, it can help borrowers understand:
- Loan amount
- Interest rate
- APR
- Tenure
- Repayment schedule
- Applicable fees
- Penal charges
- Other key terms
Why is KFS important?
Because first-time borrowers may otherwise focus only on the amount they receive.
The KFS helps shift attention toward the complete cost and conditions of borrowing.
Comparison 10: Traditional Loan vs Digital Loan
| Feature | Traditional Loan Process | Digital Loan Process |
|---|---|---|
| Application | Often branch/assisted | Usually online |
| Documentation | Physical or digital | Mostly digital |
| Verification | In-person/mixed | Often digitally assisted |
| Convenience | Moderate | High |
| Processing | Can take longer | Can be faster |
| Digital safety | Important | Extremely important |
| Cost comparison | Required | Required |
| Lender verification | Important | Essential |
Digital lending is a delivery channel—not a guarantee that a loan is cheaper or better.
Comparison 11: Regulated Lender vs Unknown Loan App
This is especially important for first-time digital borrowers.
| Verified/Legitimate Lending Arrangement | Unknown App |
|---|---|
| Actual lender can be identified | Lender may be unclear |
| Terms should be available | Terms may be vague |
| KFS may be provided where applicable | KFS may be absent |
| Customer support should be identifiable | Support may be unclear |
| Regulatory framework may apply | Regulatory status may be uncertain |
| Privacy information should be available | Data practices may be unclear |
RBI advises consumers to verify whether a digital lending app has an association or outsourcing arrangement with an RBI-regulated bank or NBFC by checking the regulated entity's website. RBI also advises avoiding apps received through SMS or social-media links. Reserve Bank of India
Digital Loan Safety Comparison
Safer approach
- Identify the actual lender.
- Check the lender's official website.
- Review the KFS.
- Compare APR.
- Understand fees.
- Review the privacy policy.
- Check data permissions.
- Keep copies of loan documents.
- Understand the repayment schedule.
Riskier approach
- Clicking an unsolicited SMS link.
- Downloading unknown loan apps.
- Accepting without reading the KFS.
- Sharing excessive permissions.
- Borrowing because an app says "pre-approved."
- Ignoring total repayment.
- Paying unexplained charges.
Data Privacy: What Should First-Time Borrowers Compare?
RBI's digital-lending framework emphasises need-based data collection, prior explicit consent, clear audit trails and borrower control over consent for specific data uses. It also requires digital lending apps/LSPs to have clear privacy policies and places restrictions on storage of personal information, subject to specified requirements. Reserve Bank of India
Before giving permissions, ask:
What information is being requested?
Is it necessary for the service?
Why is it being requested?
The purpose should be clear.
Who will receive it?
Understand the relevant parties and privacy policy.
Can I deny specific permissions?
Review the consent options carefully.
Comparison 12: Maximum Eligibility vs Comfortable Borrowing
| Maximum Eligibility | Comfortable Borrowing |
|---|---|
| Based on lender assessment | Based on your budget |
| May be the highest offered amount | Based on actual need |
| Does not necessarily consider your future plans | Considers savings and financial goals |
| Can increase debt | Focuses on manageable repayment |
| Approval-focused | Financial-health-focused |
Best practice
Never treat your maximum eligible amount as your recommended borrowing amount.
How to Compare Two Personal Loan Offers
Imagine you receive two offers.
| Factor | Offer A | Offer B |
|---|---|---|
| Loan amount | ₹2,00,000 | ₹2,00,000 |
| Interest rate | 17% | 18% |
| Tenure | 24 months | 18 months |
| EMI | Compare actual quote | Compare actual quote |
| Processing fee | Check KFS | Check KFS |
| APR | Check KFS | Check KFS |
| Total repayment | Calculate | Calculate |
| Prepayment terms | Check agreement | Check agreement |
At first glance, Offer A may appear better because its interest rate is lower.
But the shorter tenure of Offer B could change the total cost.
The correct decision requires comparing the complete offer—not one number.
Step-by-Step Comparison Guide for First-Time Digital Borrowers
Step 1: Determine Your Actual Need
Do not start with the maximum amount offered.
Start with the purpose.
Step 2: Calculate Take-Home Salary
Use the income available for your monthly household budget.
Step 3: List Existing EMIs
Include every active repayment obligation.
Step 4: Review Credit Information
Check your available credit history and look for errors.
Step 5: Calculate Affordable EMI
Leave room for essential expenses and unexpected costs.
Step 6: Compare Loan Amounts
See whether borrowing less can reduce your financial burden.
Step 7: Compare Tenures
Look at both EMI and total repayment.
Step 8: Compare Interest Rates and APR
Do not stop at the advertised interest rate.
Step 9: Read the KFS
Understand the key cost and repayment information.
Step 10: Verify the Lender
Know who is actually providing the credit.
Step 11: Review Privacy and Data Permissions
Understand what information is collected and why.
Step 12: Read the Agreement
Check repayment, fees, penalties and other applicable terms.
Step 13: Apply Carefully
Provide accurate information and genuine documents.
First-Time Digital Borrower Comparison Checklist
| Question | Yes/No |
|---|---|
| Do I actually need the loan? | ☐ |
| Have I calculated my take-home income? | ☐ |
| Have I listed all existing EMIs? | ☐ |
| Have I reviewed my credit information? | ☐ |
| Can I comfortably afford the EMI? | ☐ |
| Have I compared loan amounts? | ☐ |
| Have I compared tenure options? | ☐ |
| Have I checked the interest rate? | ☐ |
| Have I checked the APR? | ☐ |
| Have I read the KFS? | ☐ |
| Have I identified the actual lender? | ☐ |
| Have I reviewed fees and charges? | ☐ |
| Have I checked repayment terms? | ☐ |
| Have I reviewed data permissions? | ☐ |
| Do I have an emergency buffer? | ☐ |
Credit Reporting: Why First-Time Borrowers Should Care
RBI's credit-information framework provides for more frequent reporting by credit institutions, with the fortnightly reporting framework effective from January 1, 2025. Reserve Bank of India
For borrowers, the practical lesson is straightforward:
- Pay on time.
- Monitor your credit information.
- Check for inaccuracies.
- Avoid unnecessary borrowing.
- Do not assume digital loans are separate from your broader credit profile.
A digital loan can still become part of your formal credit journey where the lender reports information to credit information companies as applicable.
Pros and Cons of Digital Loans for First-Time Borrowers
Pros
- Convenient online application
- Reduced physical paperwork
- Faster digital processing may be available
- Easy access to loan information
- Digital documentation
- Convenient repayment options
Cons
- Easy access can encourage unnecessary borrowing
- Borrowers may focus on speed
- Unknown apps can create risks
- Data privacy requires attention
- Fees can increase total cost
- Missed repayments can affect finances and credit history
Expert Commentary: What Should a First-Time Borrower Compare First?
A first-time borrower should not begin with the question:
"Which lender will give me the most money?"
A better sequence is:
1. Need
How much do I actually require?
2. Affordability
What EMI fits my monthly budget?
3. Eligibility
Which loan options may fit my profile?
4. Cost
What are the interest rate, APR, fees and total repayment?
5. Safety
Who is the actual lender and what happens to my data?
6. Repayment
Can I maintain the EMI throughout the entire tenure?
This approach places the borrower's financial health ahead of simply maximising loan access.
Real-World Example: Comparing Two Borrowing Decisions
Suppose Priya earns ₹50,000 per month.
She wants ₹2 lakh for a planned expense.
She sees two digital offers.
Offer A
- Lower monthly EMI
- Longer tenure
- Higher total interest
Offer B
- Higher monthly EMI
- Shorter tenure
- Lower overall interest
Priya should not automatically select Offer A because its EMI is lower.
She should calculate:
Monthly affordability + total repayment + emergency buffer
If Offer B leaves enough monthly cash flow and results in a significantly lower total cost, it could be more suitable.
If Offer B creates too much monthly pressure, Offer A may be easier to manage.
The right answer depends on affordability.
There is no universal "best loan" for every borrower.
Common Comparison Mistakes
Mistake 1: Comparing only interest rates
Look at APR, fees and total repayment too.
Mistake 2: Comparing only EMI
Consider tenure and total cost.
Mistake 3: Comparing only loan amount
Borrow according to actual need.
Mistake 4: Ignoring existing debt
Your current EMIs affect your monthly capacity.
Mistake 5: Ignoring KFS
The KFS can help you understand important loan terms.
Mistake 6: Trusting "instant approval"
Approval speed does not determine loan quality.
Mistake 7: Not verifying the lender
Know who is actually extending the credit.
Mistake 8: Sharing unnecessary data
Review permissions and privacy information.
Mistake 9: Taking multiple loans
Several small EMIs can become a large monthly burden.
Mistake 10: Forgetting emergency savings
A loan should not leave your household financially exposed.
Summary Comparison Table
| Factor | What to Compare | Why It Matters |
|---|---|---|
| Income | Take-home salary | Determines practical affordability |
| Employment | Stability | Helps assess income continuity |
| Credit | History/profile | Indicates past credit behaviour |
| Existing EMIs | Monthly obligations | Reduces available repayment capacity |
| Loan amount | Actual need | Controls debt size |
| Tenure | Short vs long | Changes EMI and total interest |
| Interest | Applicable rate | Affects borrowing cost |
| APR | Overall annualised cost | Better cost comparison |
| KFS | Key terms | Helps understand the offer |
| Fees | Processing/other charges | Adds to total cost |
| Lender | Actual credit provider | Important for transparency and safety |
| Data | Permissions/privacy | Protects personal information |
| Repayment | EMI schedule | Helps prevent missed payments |
Vizzve Financial: Loan Support for Borrowers
Vizzve Financial is one of India's trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
For any loan application, borrowers should compare the actual offer received, including lender identity, interest rate, APR, fees, KFS, tenure and repayment obligations.
Internal Linking Suggestions
For a Vizzve website, consider linking this article to:
- Personal Loan Eligibility
- Personal Loan EMI Calculator
- Personal Loan Documents
- Digital Lending Guide
- Credit Score Guide
- Loan Application Guide
- Loan Interest Rate Guide
- KFS and APR Guide
- Emergency Loan Guide
- Responsible Borrowing Guide
Suggested anchor text
- check personal loan eligibility
- calculate your personal loan EMI
- understand digital lending
- learn about APR and KFS
- documents required for a personal loan
- how to improve your credit score
External Linking Suggestions
Use authoritative sources for factual and regulatory claims:
- RBI Handbook on Regulations at a Glance — useful for digital-lending requirements, APR, data consent and privacy. Reserve Bank of India
- RBI Financial Awareness Messages – Digital Lending Apps — useful for digital loan-app verification and consumer safety. Reserve Bank of India
- RBI Credit Information Directions 2025 — useful for credit-information reporting requirements. Reserve Bank of India
AI Summary Box
Loan Eligibility Comparison for First-Time Digital Borrowers
A salaried employee applying for a digital loan for the first time should compare income, employment, credit history, existing EMIs, loan amount, tenure, interest rate, APR, fees, KFS, lender identity, data permissions and repayment terms.
A low EMI does not necessarily mean a low-cost loan, and a high eligible amount does not necessarily mean the borrower can comfortably afford it.
Before accepting a digital loan:
Check affordability → compare total cost → read KFS → verify lender → review data permissions → understand repayment terms.
Key Takeaways
- Loan eligibility and loan affordability are different.
- Salary alone does not guarantee approval.
- Take-home income is important for personal budgeting.
- Existing EMIs can reduce borrowing capacity.
- No credit history is different from poor credit history.
- First-time borrowers should compare complete loan offers.
- Do not compare loans only by interest rate.
- Do not compare loans only by EMI.
- Check APR and applicable fees.
- Read the KFS before accepting applicable digital loan offers.
- Identify the actual lender.
- Verify digital lending apps through the associated regulated entity.
- Avoid suspicious loan links received through SMS or social media.
- Review privacy policies and data permissions.
- Borrow only what you need and can comfortably repay.
- Keep an emergency buffer after taking a loan.
Frequently Asked Questions
1. What should a first-time digital borrower compare before taking a loan?
Compare the loan amount, interest rate, APR, EMI, tenure, fees, total repayment, KFS, lender identity, repayment terms and applicable data/privacy conditions.
2. Can salaried employees with no previous loan get a digital loan?
Potentially, yes. Having limited credit history does not automatically mean rejection. The lender may consider income, employment and other information as part of its assessment.
3. Is loan eligibility the same as affordability?
No. Eligibility relates to whether you meet a lender's criteria. Affordability considers whether the repayment fits comfortably within your own budget.
4. Does a high salary guarantee personal loan approval?
No. Lenders may consider income along with employment, credit information, existing obligations, requested amount and other criteria.
5. Does having existing EMIs affect loan eligibility?
Yes. Existing EMIs can reduce the income available for a new repayment obligation and may affect the lender's assessment.
6. Should I choose the loan with the lowest EMI?
Not necessarily. A low EMI may result from a longer tenure and could lead to a higher total interest cost.
7. Is a lower interest rate always the cheapest loan?
Not necessarily. Borrowers should also consider APR, applicable fees, tenure and total repayment.
8. What is APR in a digital personal loan?
APR means Annual Percentage Rate. It provides an annualised view of the cost of credit and is an important comparison factor for applicable digital loans.
9. What is a KFS?
KFS stands for Key Facts Statement. It provides important information about applicable loan terms and costs in a standardised format.
10. How can I verify a digital lending app?
Check the actual lender and verify its association with the app through the lender's official website. RBI also advises consumers to avoid suspicious loan apps received through SMS or social-media links. Reserve Bank of India
11. Is digital lending cheaper than traditional lending?
Not automatically. Digital lending can be more convenient, but the actual cost depends on the loan's interest, APR, fees and other terms.
12. Does a first-time borrower need a credit score?
Not necessarily. A borrower may have limited or no credit history. The lender may use other information as part of its underwriting process.
13. How much personal loan should a first-time borrower take?
The borrower should take only the amount genuinely required and ensure that the EMI fits comfortably within the monthly budget.
14. What documents may salaried borrowers need?
Depending on the lender, documents may include KYC documents, PAN, salary information, bank statements and employment-related information.
15. What is the most important rule for first-time digital borrowers?
Do not borrow simply because you are eligible. Borrow only when you understand the cost and can comfortably manage the repayment.
Published on : 07th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed