

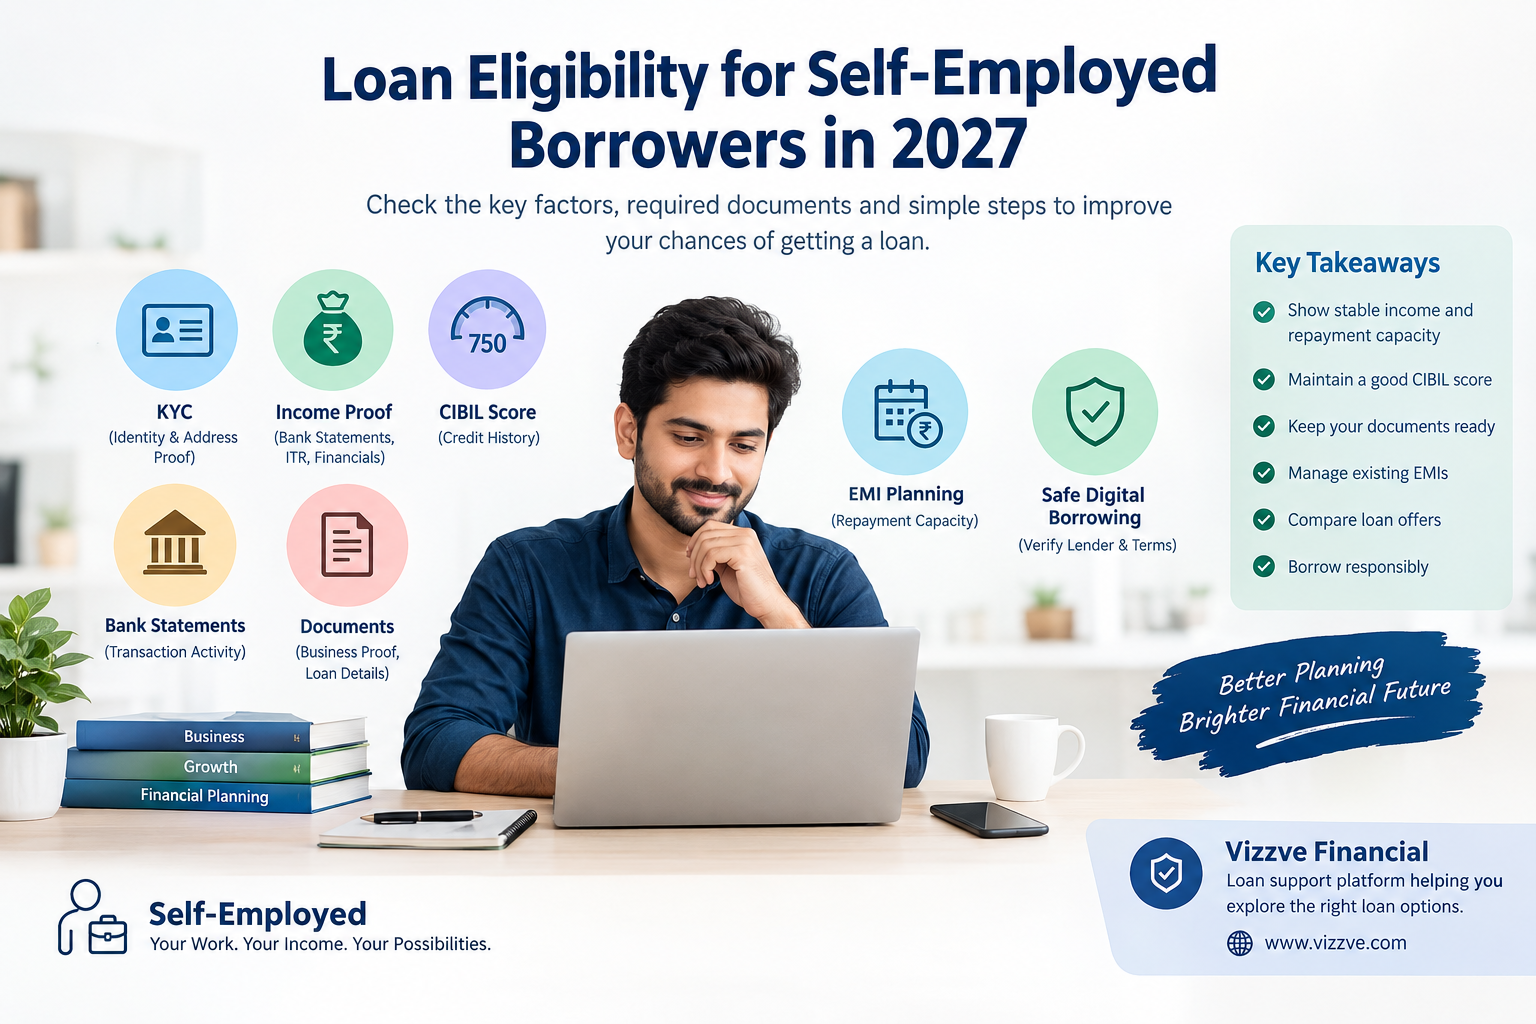
Getting a loan can feel confusing when your income does not arrive as a fixed monthly salary.
If you are a shop owner, freelancer, consultant, professional, trader, small business owner or another self-employed worker, lenders may look at your income differently from that of a salaried employee.
The good news is that self-employed borrowers can be eligible for loans. The lender usually looks at factors such as income stability, repayment capacity, credit history, existing EMIs, bank transactions, KYC documents and the type of loan being requested.
For 2027, the basic idea remains simple:
Show that you earn regularly, manage money responsibly, have suitable documents and can comfortably repay the proposed EMI.
Eligibility is not based on one factor alone. Each lender can have its own rules.
AI Answer Box: Self-Employed Loan Eligibility in 2027
Can self-employed borrowers get a loan in 2027?
Yes. Self-employed individuals may qualify for personal, business or other types of loans if they meet the lender's eligibility requirements.
What lenders commonly check
-
Age and legal eligibility
-
Identity and address verification
-
Regular income
-
Business or professional stability
-
Bank account activity
-
Existing loans and EMIs
-
Credit history and CIBIL score
-
Income-tax or financial documents where required
-
Repayment capacity
-
Loan amount and tenure requested
CIBIL explains that lenders use credit history, income and other financial information while evaluating loan applications. Its guidance also notes that documentation requirements can vary from lender to lender.
Simple answer: If your income is reasonably stable, your credit history is healthy, your documents are genuine and your proposed EMI fits your budget, you may have a stronger loan application.
What Is Loan Eligibility for a Self-Employed Borrower?
Loan eligibility means the amount and type of credit a lender may consider suitable for you after reviewing your financial profile.
For a self-employed person, income may come from:
-
A small shop or business
-
Freelancing
-
Consultancy
-
Professional services
-
Online business
-
Manufacturing
-
Trading
-
Agriculture-related activities
-
Contract work
-
Other independent work
Unlike a salaried employee who may submit a salary slip, a self-employed borrower may need to show income through bank statements, tax documents, financial statements or other acceptable records.
CIBIL lists documents such as bank statements, KYC documents and income-related records among the information lenders may request. It specifically notes that self-employed applicants may be asked for financial statements and bank statements, with requirements differing by lender.
Key Eligibility Factors for Self-Employed Borrowers in 2027
1. Regular Income
Income is one of the most important parts of a loan application.
A lender wants to understand whether you have enough money to repay the loan after managing your normal expenses and existing commitments.
For a self-employed person, income can change from month to month. Therefore, lenders may look at a broader financial picture rather than only one month's earnings.
Keep your income records organised
Useful records may include:
-
Bank statements
-
Income-tax returns, where applicable
-
Financial statements
-
Business records
-
GST-related records, where applicable
-
Invoices or payment records
-
Other legitimate proof accepted by the lender
The exact documents depend on the lender and loan product.
2. CIBIL Score and Credit History
Your credit history tells a lender how you have handled previous credit.
The CIBIL Score is a three-digit score ranging from 300 to 900. A higher score generally indicates stronger credit history, although the final lending decision is made by the lender and not by CIBIL.
What can affect your credit profile?
-
Missed EMI payments
-
Credit-card payment delays
-
Outstanding debt
-
Frequent credit applications
-
Credit utilisation
-
Length of credit history
-
Repayment behaviour
A strong credit profile can improve your chances of getting suitable loan terms, but there is no single CIBIL score that guarantees approval for every loan.
3. Existing EMIs and Repayment Capacity
A borrower may earn a good income but still have limited borrowing capacity if a large portion of that income is already committed to EMIs.
For example:
Monthly income: ₹60,000
Existing EMIs: ₹20,000
New proposed EMI: ₹10,000
The borrower would have ₹30,000 remaining after these listed EMIs, before considering other household and business expenses.
This is why you should not decide the loan amount only by looking at the maximum amount offered.
CIBIL's loan guidance notes that lenders consider existing EMI obligations in evaluating repayment capacity.
Simple rule
Loan affordability = income − existing obligations − essential expenses
The exact calculation used by a lender may be different.
4. Bank Statements
For self-employed borrowers, the bank statement can help show how money moves through the account.
A lender may review:
-
Regular credits
-
Business receipts
-
Existing EMI payments
-
Returned payments
-
Large unexplained transactions
-
Average account activity
-
Existing financial commitments
A clean and consistent financial trail can make it easier for the lender to understand your financial position.
5. KYC and Identity Verification
Know Your Customer (KYC) is an important part of lending.
Depending on the product and lender, you may be asked for documents such as:
-
PAN
-
Aadhaar or another accepted identity document
-
Address proof
-
Bank account details
-
Business or professional information
Always provide genuine information.
Incorrect or inconsistent information can delay verification or lead to rejection.
6. Business or Professional Stability
A lender may want to know whether your source of income is reasonably stable.
For example, a person who has been running a business consistently may have a clearer financial record than someone who started earning independently very recently.
This does not mean a new self-employed borrower cannot get a loan. It simply means the lender may have less financial history to assess.
Documents Commonly Needed by Self-Employed Borrowers
The exact checklist varies.
| Document/Information | Why It May Be Required |
|---|---|
| PAN | Identity and financial verification |
| Aadhaar/other KYC | Identity/address verification |
| Bank statements | Shows financial activity |
| Income-tax records | Helps establish declared income |
| Financial statements | Shows business performance |
| Business proof | Helps establish business activity |
| Office/business address proof | Verification |
| Existing loan details | Helps assess repayment obligations |
| Credit report | Shows credit history |
CIBIL's published document checklists identify KYC documents, bank statements and income-related documents as common requirements, while noting that lender requirements can differ.
Self-Employed vs Salaried Borrower
| Factor | Self-Employed | Salaried |
|---|---|---|
| Income source | Business/professional activity | Salary |
| Income pattern | May vary | Usually more predictable |
| Common income proof | Tax records, statements, financials | Salary slips, bank statements |
| Business proof | May be required | Usually not applicable |
| Credit history | Important | Important |
| Bank activity | Important | Important |
| Existing EMIs | Considered | Considered |
| Repayment capacity | Assessed | Assessed |
The biggest difference is generally how income is demonstrated, not whether a person can borrow.
How to Improve Loan Eligibility Before Applying
1. Pay Existing EMIs on Time
Late payments can negatively affect your credit profile.
Make repayment dates part of your monthly financial routine.
2. Keep Your Credit Utilisation Under Control
Avoid using more credit than you can comfortably manage.
3. Maintain Clear Financial Records
Keep your:
-
Bank statements
-
Tax records
-
Business documents
-
Income records
-
Loan statements
organised.
4. Avoid Applying Everywhere at Once
Before applying, compare the loan amount, interest rate, fees, tenure and repayment terms.
Multiple credit enquiries within a short period may affect how lenders view your credit profile.
5. Borrow an Amount You Can Repay
A larger approved amount is not automatically a better financial decision.
Choose an EMI that leaves enough money for regular household and business needs.
Step-by-Step: How a Self-Employed Borrower Can Prepare
Step 1: Check your credit report
Review your credit history for incorrect information, overdue accounts or other issues.
Step 2: Calculate your monthly income
Use a realistic figure rather than your best earning month.
Step 3: List existing EMIs
Write down every active loan and credit obligation.
Step 4: Estimate an affordable EMI
Leave enough room for normal living and business expenses.
Step 5: Prepare documents
Keep KYC, bank statements and income-related documents ready.
Step 6: Compare loan offers
Check the total cost, not just the advertised interest rate.
Step 7: Read the loan documents
Before accepting, understand the interest rate, Annual Percentage Rate (APR), fees, repayment schedule, late-payment consequences and other applicable terms.
Digital Loans: What Should Self-Employed Borrowers Check?
Digital lending can make applications easier, but convenience should not replace careful checking.
RBI guidance on digital lending requires regulated entities to provide important information such as the Annual Percentage Rate (APR) and follow requirements around borrower consent and data handling.
Before accepting a digital loan, check:
-
Name of the actual lender
-
Total amount repayable
-
APR
-
Processing charges
-
Other applicable fees
-
EMI or repayment schedule
-
Privacy policy
-
Data permissions
-
Grievance-redressal information
-
Loan agreement and Key Facts Statement, where applicable
RBI also advises borrowers to deal with regulated entities and be cautious of agents who promise loans in exchange for fees.
Pros and Cons of Borrowing as a Self-Employed Person
| Pros | Cons |
|---|---|
| Multiple loan products may be available | Income may not be fixed |
| Business income can support repayment | More income documentation may be required |
| Good credit can improve borrowing options | Weak credit can reduce options |
| Digital applications can simplify the process | Online scams and fake apps are a risk |
| Loan can support genuine financial needs | Excessive borrowing can create pressure |
Real-World Example
Suppose Rahul runs a small repair business.
His monthly income changes between ₹45,000 and ₹65,000. He already has one EMI of ₹8,000.
Before applying for another loan, he should not simply use ₹65,000 as his permanent monthly income.
A more sensible approach would be to:
-
Review several months of bank activity.
-
Understand his average income.
-
Check his credit report.
-
List his existing EMI.
-
Calculate household and business expenses.
-
Decide an affordable new EMI.
-
Compare lenders and total borrowing costs.
This gives the lender a clearer financial picture and helps Rahul make a safer borrowing decision.
Expert Commentary: What Matters Most?
For self-employed borrowers, documentation and consistency matter.
There is no magic formula that guarantees approval. A lender needs enough reliable information to understand the applicant's income, existing obligations, credit behaviour and repayment capacity.
CIBIL's guidance confirms that lenders consider several factors rather than relying on one number alone.
Trust-building point
A borrower should never provide false income, fake documents or misleading information simply to obtain a higher loan amount.
Accurate information protects both the borrower and the lender.
Responsible Borrowing in 2027
Borrowing should solve a genuine financial need rather than create another financial problem.
RBI's financial-awareness material recommends responsible borrowing and encourages consumers to assess repayment ability and use legitimate regulated lending channels.
Ask yourself these five questions
-
Why do I need this loan?
-
Can I repay the EMI every month?
-
What is the total cost of the loan?
-
Do I already have too much debt?
-
Have I checked the lender and loan documents?
If the answer to the repayment question is uncertain, consider reducing the loan amount or waiting until your finances are stronger.
Vizzve Financial: Loan Support for Borrowers
Vizzve Financial is a loan support and comparison platform that connects borrowers with banks and NBFCs. Its website states that users can explore loan offers from multiple lending institutions, while final approval and disbursal depend on the relevant lender's eligibility and policies.
Vizzve's official website also describes an online application process involving PAN-based profile information, loan offers, bank details and digital KYC.
Explore: www.vizzve.com
Important: Do not treat any platform as a guarantee of loan approval. Always review the actual lender, loan agreement, interest/APR, fees and repayment terms before accepting an offer.
Key Takeaways
-
Self-employed borrowers can be eligible for loans in 2027.
-
Income stability and repayment capacity are important.
-
CIBIL score and credit history can influence loan evaluation.
-
Bank statements can help demonstrate financial activity.
-
KYC and income-related documents should be accurate and current.
-
Existing EMIs affect how much additional debt you can comfortably take.
-
Requirements differ between lenders and loan products.
-
Compare the total cost of borrowing rather than focusing only on the interest rate.
-
Check digital loan apps and lenders carefully.
-
Borrow only an amount that you can realistically repay.
Summary Box
Loan Eligibility for Self-Employed Borrowers in 2027 — In Simple Words
A self-employed borrower may qualify for a loan when the lender is satisfied with their income, credit history, documents and repayment capacity. The best preparation is to maintain clean financial records, pay existing EMIs on time, check your credit report and choose a loan that fits your budget.
Remember: Loan approval is never guaranteed simply because you meet a general eligibility condition. The final decision belongs to the lender.
Frequently Asked Questions
1. Can self-employed people get personal loans in 2027?
Yes. Self-employed individuals may qualify for personal loans if they satisfy the lender's eligibility and documentation requirements.
2. What is the most important factor for self-employed loan eligibility?
There is no single factor. Income, repayment capacity, credit history, existing obligations, documentation and lender-specific criteria can all matter.
3. What CIBIL score is needed for a self-employed personal loan?
There is no universal score that guarantees approval. A stronger credit history can improve the chances of suitable loan options. CIBIL states that the higher the score, the better the chances of loan approval, while the final decision remains with the lender.
4. What documents are needed for a self-employed loan?
Common documents may include KYC documents, bank statements, income-tax records, financial statements and business or address proof. Requirements vary by lender.
5. Can a freelancer apply for a loan?
Yes. Freelancers may apply for loans, subject to the lender's criteria and their ability to demonstrate income and repayment capacity.
6. Does bank balance affect loan eligibility?
Bank activity can help lenders understand income and cash flow, but having a high balance alone does not guarantee loan approval.
7. Can I get a loan with an irregular income?
Possibly. The lender may assess your overall financial history and repayment ability rather than relying on one month's income.
8. Does an existing EMI reduce loan eligibility?
Yes. Existing EMIs represent current financial commitments and can reduce the amount of additional debt you can comfortably afford.
9. How can I improve my loan eligibility?
Pay EMIs on time, maintain a healthy credit profile, keep financial documents organised, reduce unnecessary debt and apply for an amount that fits your repayment capacity.
10. Is a digital loan always safe?
No. Borrowers should verify the lender, understand the total cost, review permissions and privacy information, and use legitimate lending channels. RBI advises consumers to exercise caution when using digital lending services.
Internal Linking Suggestions
For the Vizzve website, consider linking this article naturally to related pages such as:
-
Personal Loan Eligibility Guide
-
Digital Loan KYC Guide
-
Digital Loan Data Privacy
-
Digital Loan Data Storage
-
Digital Loan Credit Reporting
-
Loan Repayment Guide
-
CIBIL Score and Loan Eligibility
-
Loan Documents Checklist
-
Responsible Borrowing Guide
Use descriptive anchor text instead of generic phrases such as “click here.”
External Linking Suggestions
For authority and trust, consider linking to:
-
RBI: Digital lending and responsible borrowing guidance
-
RBI Financial Education: Consumer awareness resources
-
TransUnion CIBIL: Credit score and loan-approval guidance
-
Relevant government portals: Income-tax or business-registration information where applicable
Authoritative external references help readers verify important financial information independently.
References
-
Reserve Bank of India — Digital Lending and borrower-protection guidance.
-
Reserve Bank of India — Responsible Borrowing financial-awareness material.
-
TransUnion CIBIL — Loans and documentation guidance.
-
TransUnion CIBIL — Credit Score and Loan Basics.
-
Vizzve Financial — Official platform and loan information.
Conclusion
Loan eligibility for self-employed borrowers in 2027 is easier to understand when you break it into a few simple areas: income, credit history, documents, existing debt and repayment capacity.
You do not need a traditional salary to apply for a loan. What matters is whether you can provide reliable financial information and demonstrate that the proposed repayment fits your financial situation.
Before borrowing, compare the total cost, read the loan terms carefully and make sure the EMI is manageable.
For borrowers who want to explore available loan options, Vizzve Financial provides a digital platform for connecting with banks and NBFCs. Final approval, interest rates, loan amounts and terms remain subject to the applicable lender's policies and eligibility assessment.
Explore loan options: Vizzve Financial
Financial decisions should be based on your individual circumstances. Always verify the lender, costs and applicable terms before accepting a loan.
Published on : 7th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed