

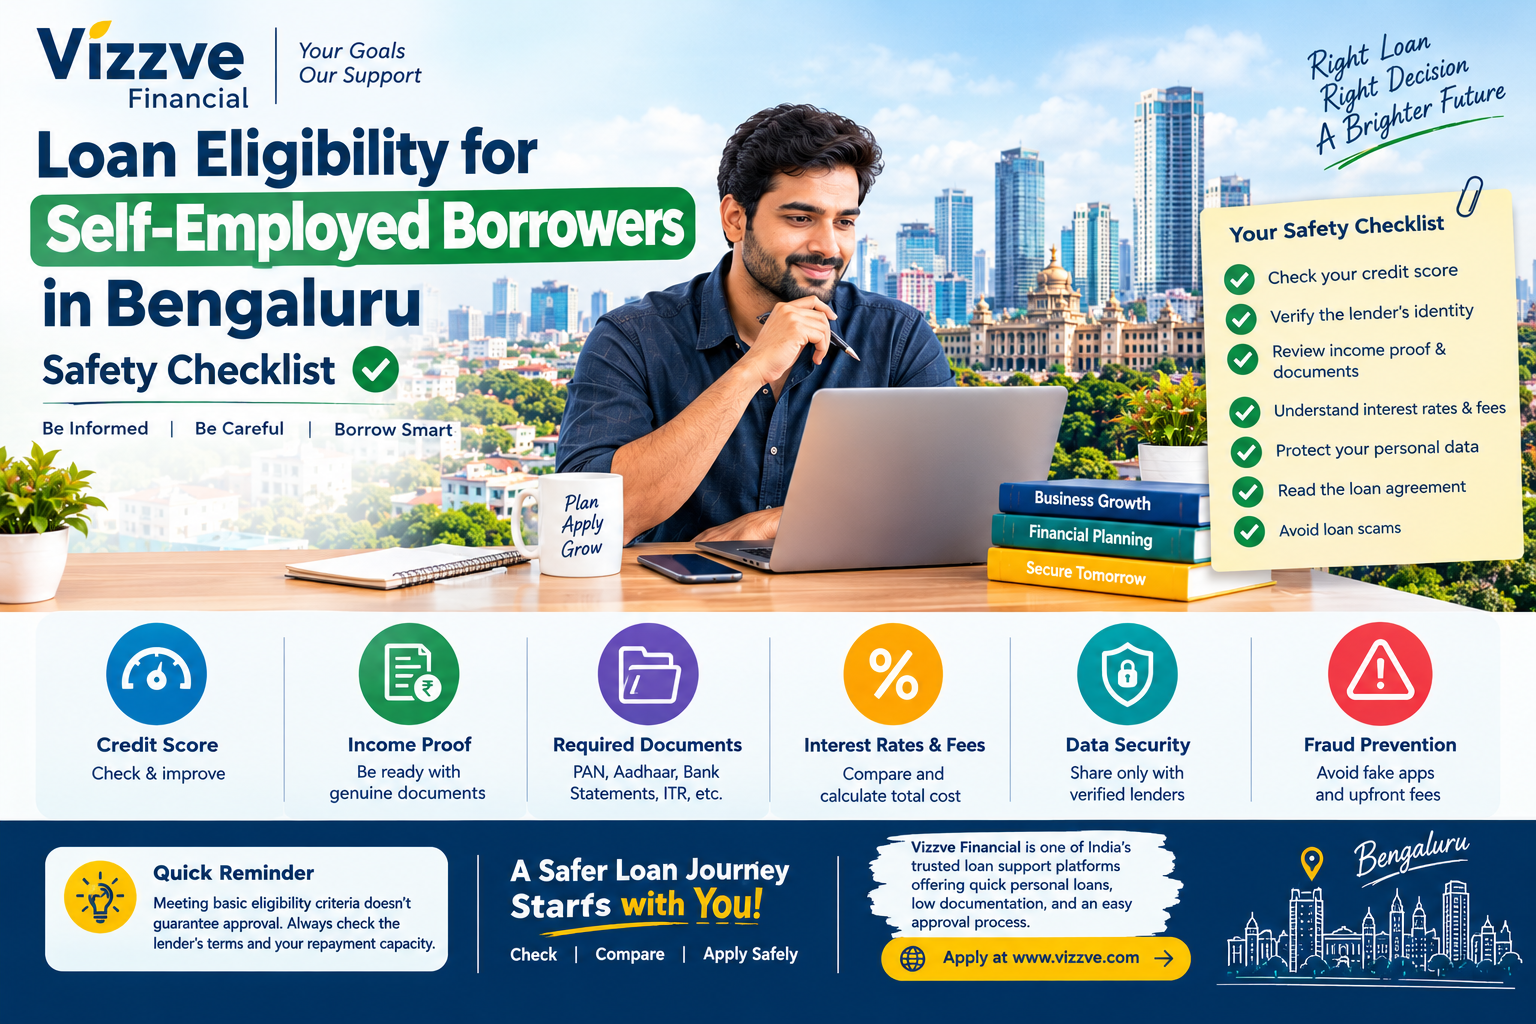
Self-employed professionals in Bengaluru—including consultants, freelancers, shop owners, traders, independent service providers and small business owners—may need personal loans to manage business-related expenses, medical costs, household needs or unexpected financial commitments.
However, being eligible for a loan and applying for one safely are two different things. A borrower might meet a lender’s income and credit criteria but still face risks from misleading loan advertisements, hidden charges, fake loan apps, unnecessary data collection or repayment obligations that exceed their budget.
A loan eligibility safety checklist helps you review your financial readiness, verify the lender, understand the loan agreement and protect your personal information before applying.
This guide explains the key checks self-employed borrowers in Bengaluru should complete before submitting a personal loan application. It also covers practical ways to identify warning signs, compare loan costs and make an informed borrowing decision.
Important: Loan eligibility criteria differ by lender and product. Meeting general requirements does not guarantee approval, and no particular credit score or income level guarantees a loan.
AI Answer Box: How Can Self-Employed Borrowers Check Loan Eligibility Safely?
Self-employed borrowers in Bengaluru can check loan eligibility safely by reviewing their income stability, credit history, existing EMIs and repayment capacity. They should prepare genuine income documents, verify that the lender is a legitimate regulated entity or authorised lending partner, read the Key Facts Statement (KFS), compare the annualised borrowing cost and understand all fees before accepting an offer.
Before applying, borrowers should also confirm the lender’s privacy practices, avoid sharing OTPs or banking passwords, and never pay suspicious upfront charges to an unverified person or app. Approval depends on the lender’s individual eligibility criteria and credit assessment.
Key Takeaways
-
Check your finances first: Review income, expenses, existing EMIs and emergency savings.
-
Prepare genuine documents: Keep identity, address, bank and business or income records ready.
-
Verify the lender: Confirm the identity of the bank or regulated non-banking financial company (NBFC) responsible for the loan.
-
Understand the complete cost: Review interest, processing fees, taxes, late-payment charges and other applicable costs.
-
Protect your information: Never share OTPs, PINs or banking passwords with an agent.
-
Read before accepting: Check the KFS, loan agreement, repayment schedule and grievance contact details.
-
Borrow within your means: An eligible loan amount may still be unaffordable for your business or household budget.
1. What Does Loan Eligibility Mean for Self-Employed Borrowers?
Loan eligibility refers to the conditions a lender uses to decide whether an applicant qualifies for a particular loan and how much they may be able to borrow.
For self-employed applicants, the assessment may include income consistency, business vintage, bank transactions, tax records, credit history, current liabilities and repayment capacity.
Unlike salaried employees, who may have regular payslips, self-employed applicants often need to demonstrate their earnings through several financial records.
Common eligibility factors
|
Eligibility factor |
What the lender may review |
Your safety check |
|---|---|---|
|
Age |
Whether you meet the product's age criteria |
Confirm the minimum and maximum age |
|
Income |
Business income, professional earnings and cash flow |
Use genuine, consistent records |
|
Business history |
How long you have been operating |
Keep registration or business records where applicable |
|
Credit history |
Past repayments and outstanding credit |
Review your credit report for errors |
|
Existing obligations |
Current EMIs, credit-card dues and other debts |
Calculate the total monthly burden |
|
Bank statements |
Deposits, withdrawals and transaction patterns |
Submit authentic, unaltered statements |
|
Documents |
Identity, address and income verification |
Share documents only through verified channels |
Important: These are common assessment factors, not universal eligibility rules. Each lender may have different requirements for its personal loan products.
2. The Essential Loan Eligibility Safety Checklist
Before applying for a personal loan in Bengaluru, use the following checklist to review both eligibility and safety.
Your pre-application checklist
Financial readiness
Documents and credit history
Lender and offer verification
Privacy and fraud protection
Reset checklistCompleting the checklist does not guarantee loan approval. It helps you identify gaps and reduce avoidable risks before you submit an application.
3. How Can Self-Employed Borrowers in Bengaluru Verify a Lender?
Lender verification is one of the most important safety steps. A professional-looking website, online advertisement or mobile app is not proof that a loan offer is legitimate.
The Reserve Bank of India (RBI) has issued the Reserve Bank of India (Digital Lending) Directions, 2025, which address digital lending practices, disclosures and borrower protection. The RBI also provides a directory of digital lending apps associated with regulated entities. The directory can help borrowers check an app's claimed association, but the RBI says the directory is based on information submitted by regulated entities and should not be treated as an endorsement of an app.

Lender verification steps
-
Identify the actual lender. Find the name of the bank or NBFC that will issue the loan. A loan app or lending service provider may facilitate the process without being the lender itself.
-
Use official sources. Visit the lender's official website independently rather than relying only on a link in a text message or social media advertisement.
-
Check the relationship. If an app claims to work with a bank or NBFC, verify that relationship using the lender's own website and, where applicable, the RBI's digital lending app directory.
-
Verify contact details. Check whether the customer-support details and grievance-redressal information match the official lender's information.
-
Read the offer carefully. Confirm the loan amount, interest rate, fees, tenure and repayment dates before accepting.
-
Stop if anything appears suspicious. Do not proceed if someone pressures you to pay a personal account, install an unknown file or share security credentials.
For general information on suspicious digital lending platforms, the RBI's consumer guidance warns against sharing KYC documents with unidentified people or unverified apps.
Warning signs you should never ignore
-
A promise of guaranteed approval regardless of income or credit history.
-
Pressure to pay an unexplained fee before the lender has provided clear loan terms.
-
Requests for OTPs, UPI PINs, card PINs or net-banking passwords.
-
An app demanding unnecessary access to contacts, call logs, photos or other personal information.
-
No clear identification of the lender or no accessible grievance contact.
-
Threats, abusive messages or pressure to make an immediate payment.
One warning sign does not by itself establish every detail about an organisation, but it is a good reason to stop and independently verify the offer.
4. Documents Self-Employed Borrowers Should Prepare
The documents required depend on the lender, loan type and applicant's circumstances. Preparing accurate records can help reduce delays and make income verification easier.
|
Document category |
Examples |
Safety tip |
|---|---|---|
|
Identity proof |
PAN and other accepted identity documents |
Upload only through an authorised channel |
|
Address proof |
Accepted address documents |
Ensure your details are current |
|
Bank statements |
Recent statements for the period requested by the lender |
Download from your bank or use an approved statement-sharing process |
|
Income proof |
Income tax returns, computation of income or other accepted records |
Ensure amounts match the underlying records |
|
Business proof |
Registration, licence, GST records or other applicable documents |
Provide only what is relevant and requested |
|
Existing loan details |
EMI schedules or outstanding loan statements |
Disclose current obligations accurately |
|
Photographs or digital KYC |
Only where required by the lender |
Check why the information is needed |
How to organise your income documents
For freelancers and consultants: Keep invoices, client payment records, bank credits and applicable tax records organised.
For shop owners and traders: Maintain business bank statements, sales records, tax filings where applicable, and evidence of regular business activity.
For professionals with seasonal earnings: Keep a clear record of income across stronger and weaker months. A single high-income month may not accurately reflect your repayment capacity.
Never modify financial documents to improve eligibility
Do not inflate income, edit bank statements, fabricate invoices or submit another person's records as your own. Misrepresentation can lead to rejection and may create legal or financial consequences.
If your income is irregular, explain it honestly and ask the lender which documents it accepts.
5. Check Your Credit Report Before Applying
Your credit history helps lenders assess how you have managed borrowing in the past. Repayment records, outstanding balances and other information in a credit report may influence the lender's decision, alongside income and other eligibility factors. Credit scores are not the only factor in loan approval.
A safe credit-check routine
-
Obtain your credit report through an authorised credit information company or official channel.
-
Check whether your name, personal details and loan accounts are accurate.
-
Review any overdue payments or accounts you do not recognise.
-
Raise a dispute with the relevant credit bureau or lender if you identify an error.
-
Avoid submitting multiple applications indiscriminately in the hope of securing approval.
A credit score threshold is not universal. A lender may also consider your documented income, business stability, debt obligations and its own credit policy.
What if your credit score is lower than expected?
First, check the report for errors. If the information is correct, focus on paying obligations on time, reducing expensive outstanding debt where possible and avoiding new borrowing you cannot comfortably repay.
Do not pay anyone who promises to erase accurate negative credit information or guarantee approval.
6. Assess Repayment Capacity Before Choosing a Loan
Loan eligibility does not automatically mean a loan is affordable. For self-employed borrowers, this distinction matters because income can vary from month to month.
Start by estimating income after business operating costs and essential household expenses. Then subtract existing EMIs and other recurring debt payments.
Example: A practical monthly affordability check
Consider a hypothetical self-employed consultant in Bengaluru.
|
Monthly calculation |
Amount |
|---|---|
|
Average income received |
₹90,000 |
|
Business operating expenses |
₹20,000 |
|
Essential household expenses |
₹25,000 |
|
Existing monthly debt payments |
₹10,000 |
|
Amount remaining before a new EMI and savings |
₹35,000 |
The ₹35,000 remainder is not a recommended EMI amount. The borrower still needs to account for taxes where applicable, emergency savings, irregular expenses and months when income is lower than average.
A safer approach is to test the proposed EMI against a conservative income estimate, not just the best month.
Questions to ask yourself
-
Could I pay the EMI if one or two clients delayed payment?
-
Would repayments leave enough for business expenses and household essentials?
-
Do I have an emergency buffer?
-
Will I need to borrow again to make the next EMI?
-
Is the loan necessary now, or can the expense be delayed or funded another way?
If the repayment plan depends on optimistic income projections, consider a smaller loan, a longer planning period or postponing the application.
7. Understand the KFS, Interest Rate and Hidden-Cost Risks
Before accepting a covered retail term loan, review the Key Facts Statement (KFS) provided by the lender. RBI requirements include disclosure of the Annual Percentage Rate (APR) and key loan information so borrowers can understand the cost of borrowing. Check the applicable rules and the terms of your particular product.
The advertised interest rate alone does not necessarily show the full cost.
What should you compare?
|
Loan detail |
What to check |
|---|---|
|
Interest rate |
Is it fixed or variable, and how is it applied? |
|
APR |
What is the disclosed annualised cost of the loan? |
|
Processing fee |
What amount or percentage is charged? |
|
Taxes |
Which taxes apply to the disclosed fees? |
|
Net disbursal |
How much will actually reach your account? |
|
Tenure |
How many monthly instalments will you pay? |
|
Total repayment |
What is the total payable over the full tenure? |
|
Late-payment charges |
What happens if an EMI is delayed? |
|
Foreclosure or prepayment |
Are charges applicable, and what conditions apply? |
|
Cooling-off period |
Is there an exit option, and what conditions and charges apply? |
Compare two hypothetical loan offers
The following figures are illustrative only, not current offers from any lender.
|
Detail |
Offer A |
Offer B |
|---|---|---|
|
Principal |
₹1,00,000 |
₹1,00,000 |
|
Illustrative annual interest rate |
14% |
16% |
|
Illustrative tenure |
12 months |
12 months |
|
Processing fee |
2% |
1% |
|
Other charges |
Check lender terms |
Check lender terms |
Offer A has a lower illustrative interest rate, but you should not decide on that figure alone. Calculate the EMI, net amount received, applicable taxes and fees, and total repayment using each lender's actual written offer.
Safety rule: Do not accept an offer until you understand how much you will receive, how much you will repay and what happens if you miss a payment.
8. Protect Your Personal and Financial Data
Digital applications can make loan processing convenient, but they also require careful handling of sensitive information.
The RBI's digital lending framework addresses borrower consent, data collection, disclosures and the responsibilities of regulated entities and their lending service providers. Borrowers should still review the permissions and privacy information presented by the particular app or website.
Safe data-sharing practices
-
Apply through the verified lender's website, official app or confirmed lending partner.
-
Read the privacy policy and understand what information is collected and why.
-
Grant permissions only when justified and permitted by applicable rules.
-
Avoid sending PAN, Aadhaar or bank documents to unidentified WhatsApp numbers or personal email addresses.
-
Never disclose OTPs, PINs, passwords or remote-access codes to an agent.
-
Do not install unknown APK files or remote-control apps at the request of a loan representative.
-
Save the application reference, offer documents and lender communications securely.
Is it safe to share Aadhaar and PAN details online?
It can be appropriate when a verified lender needs them for lawful identity verification, but the channel matters. Confirm the recipient, use the official application process and avoid sharing documents with an unknown intermediary.
Do not assume that an app is safe merely because it is available online or has positive-looking reviews.
9. Avoid Common Loan Scams Targeting Borrowers
Scammers may target people who need urgent funds, including small business owners and self-employed professionals whose earnings fluctuate.
The RBI has warned consumers about unauthorised lending platforms, excessive charges, misuse of mobile-phone data and improper recovery practices.
Common scam patterns
1. Guaranteed approval scams
An agent promises approval without checking your documents or finances, often in exchange for a fee. Legitimate lenders still apply their own eligibility and underwriting processes.
2. Fake processing-fee requests
Someone asks you to transfer money to a personal UPI ID or bank account to release the loan. Stop and verify any payment request directly with the lender through its official contact details.
3. Fake lender websites
A website copies a genuine financial company's name, logo or branding. Independently enter the official website address and verify the lender rather than trusting a link sent by an unknown person.
4. Data-harvesting apps
An app requests extensive phone access unrelated to the service being provided. Review permissions and stop if the data requested appears unnecessary or unexplained.
5. Harassment and threats
An individual threatens to contact your family, clients or business contacts over an alleged loan. Preserve messages, call details and payment records, and report the matter through appropriate channels.
What should you do if you suspect fraud?
-
Stop sharing documents or sending money.
-
Contact your bank or payment provider immediately if you transferred money or exposed account details.
-
Change compromised passwords and secure relevant accounts.
-
Preserve screenshots, messages, receipts, transaction references and app details.
-
Report suspected cyber financial fraud promptly through India's official cybercrime reporting channels or call 1930 for cyber financial fraud assistance.
-
Report the matter to the relevant lender, police or regulator as appropriate.
For unauthorised financial activities, the RBI's Sachet portal is another official resource. For complaints against covered regulated entities, use the RBI's Complaint Management System, subject to the applicable complaint process and eligibility requirements.
10. Step-by-Step: A Safer Loan Application Process
Use this process whether you are a freelancer, consultant, trader, shop owner or other self-employed professional in Bengaluru.
Step 1: Define the borrowing need
Decide how much you genuinely need and whether a personal loan is suitable for that purpose.
Step 2: Check income and affordability
Calculate average income, operating expenses, existing EMIs and a realistic amount available for repayment.
Step 3: Organise genuine documents
Prepare accepted identity, address, bank, tax and business records, as requested by the lender.
Step 4: Verify the lender
Confirm the actual lending institution, its official application channel and the relationship with any lending service provider.
Step 5: Compare the written offers
Review the KFS, APR, fees, net disbursal, total repayment and relevant prepayment or exit conditions.
Step 6: Review before accepting
Read the agreement and repayment schedule. Confirm that the information is correct before giving final consent.
Step 7: Plan repayments
Record EMI dates, keep funds available and contact the lender early if you anticipate a repayment problem.
11. Benefits and Limitations of Applying Safely
A careful application process does not guarantee approval, but it can help you make a more informed decision and avoid preventable mistakes.
|
Benefits |
Limitations |
|---|---|
|
Helps identify unaffordable borrowing |
Requires time to compare and verify offers |
|
Reduces exposure to suspicious lenders |
Genuine verification may involve several documents |
|
Makes fees and repayment terms easier to compare |
Lenders may still reject an application |
|
Helps protect personal and financial information |
Eligibility standards vary by lender |
|
Supports better repayment planning |
Self-employed income may remain unpredictable |
|
Creates a clearer record of the application |
Credit approval and disbursal timelines can vary |
Pros and cons of a personal loan for self-employed borrowers
Potential advantages
-
Funds may be available for eligible personal expenses without pledging an asset, depending on the product.
-
A regular EMI schedule can help organise repayment planning.
-
Some lenders offer digital application processes.
-
Responsible repayment may contribute positively to credit history over time.
Potential disadvantages
-
Interest and fees can increase the total cost.
-
Variable income can make fixed monthly repayments harder to manage.
-
Missing payments can harm credit history and lead to additional charges.
-
Unsecured loans may carry higher rates than some secured alternatives.
-
Approval depends on the lender's assessment and is never guaranteed.
12. Practical Advice for Self-Employed Borrowers in Bengaluru
Bengaluru's self-employed community includes technology consultants, independent designers, tutors, healthcare professionals, local retailers, tradespeople, entrepreneurs and gig workers. Their income patterns can differ substantially.
The following are practical scenarios to consider, rather than claims about any particular lender or borrower.
Scenario A: A freelancer with irregular client payments
A freelancer may earn ₹1 lakh in one month and considerably less in another. Using the highest month as the basis for an EMI decision could leave insufficient money when invoices are delayed.
Safer approach: Review several months of actual income, account for business costs and choose a repayment obligation that remains manageable during weaker months.
Scenario B: A shop owner with mixed personal and business transactions
Frequent transfers between personal and business accounts can make cash flow harder to interpret.
Safer approach: Maintain clear records and explain transactions accurately. Do not alter statements to make the business appear more profitable.
Scenario C: A consultant considering a loan for an urgent expense
An urgent expense may create pressure to accept the first available offer.
Safer approach: Check the lender's identity, compare the total cost and read the repayment terms even when time is limited. Avoid promises of guaranteed approval or pressure to pay an unofficial fee.
Scenario D: A borrower whose application was rejected
A rejection can be frustrating, but submitting applications repeatedly without understanding the reason may not help.
Safer approach: Ask the lender whether it can provide a reason, review your credit report, check the completeness of your documents and reconsider the amount you can afford before applying elsewhere.
13. What to Do If Your Loan Application Is Rejected
A rejection does not necessarily mean you will never qualify for a loan. It may reflect the lender's current criteria, the information submitted or its assessment of repayment risk.
Consider these steps:
-
Review any reason supplied by the lender.
-
Check whether your application contains missing or inconsistent information.
-
Review your credit report for errors or unfamiliar accounts.
-
Reassess your existing debt and the amount requested.
-
Prepare better-supported income records if the lender accepts them.
-
Apply again only when you understand the likely issue and have a suitable product to consider.
Avoid agents who claim they can guarantee approval by changing documents, manipulating a credit score or paying an unofficial fee.
14. Expert Commentary: Safety Is Part of Eligibility
A useful way to assess a loan is to ask two separate questions:
-
Can I qualify? This depends on the lender's criteria, credit assessment, income evidence and other relevant factors.
-
Can I repay safely? This depends on the amount borrowed, the full cost of credit, the stability of your income and your ability to meet payments without sacrificing essential expenses.
The second question is just as important as the first.
For a self-employed borrower, the safest loan is not necessarily the largest amount offered or the fastest approval. It is a loan from a verified lender whose terms are understood and whose repayments fit the borrower's realistic budget.
This is general financial education, not a guarantee of approval or a personalised recommendation. Borrowers should review the actual loan agreement and seek qualified advice when they are uncertain about significant financial commitments.
15. Frequently Asked Questions (FAQs)
1. What is the loan eligibility safety checklist for self-employed borrowers in Bengaluru?
It is a set of checks covering income, credit history, documents, repayment capacity, lender verification, loan charges and data privacy. Completing these checks helps you make a safer borrowing decision but does not guarantee approval.
2. Can self-employed people in Bengaluru apply for personal loans?
Yes. Self-employed people may apply for personal loans from lenders that accept their applicant category. Approval depends on the lender's eligibility criteria, documented income, credit history and other relevant factors.
3. What documents are generally required for a self-employed personal loan?
Commonly requested documents include PAN, accepted identity and address proof, bank statements, income tax returns or other income records, and business-related documents where applicable. Requirements vary by lender.
4. Is there a minimum credit score for a personal loan?
There is no single minimum score that applies to every lender and personal loan product. Lenders may consider credit history alongside income stability, existing debt, documentation and other underwriting criteria.
5. How can I verify whether an online loan app is legitimate?
Identify the bank or NBFC responsible for the loan, verify the app's relationship with that institution through official sources and check the RBI's digital lending app directory where applicable. The directory helps verify claimed associations but is not an RBI endorsement.
6. Should I pay an advance fee to guarantee loan approval?
Be cautious of any person demanding an unexplained advance payment in exchange for guaranteed approval. Verify all charges directly with the lender through its official channels and review the written loan terms before paying anything.
7. What is a Key Facts Statement (KFS)?
A KFS is a standardised disclosure document for covered loans that presents important loan information, including the APR and applicable charges. Review it before entering into the loan contract and ask the lender to explain anything you do not understand.
8. How can self-employed borrowers prove irregular income?
Depending on the lender's requirements, applicants may provide bank statements, invoices, tax returns, business records and evidence of client payments. Use genuine documents that accurately reflect earnings and explain significant fluctuations where requested.
9. How much personal loan can a self-employed person get?
The eligible amount depends on the lender's product limits and assessment of income, repayment capacity, existing obligations, credit history and other factors. Do not assume that the maximum amount offered is the amount you can comfortably afford.
10. Is an online personal loan safe?
It can be safe when the borrower uses a verified lending channel, understands the terms, shares information through authorised processes and protects security credentials. An online presence alone does not establish legitimacy.
11. What should I do if a loan app misuses my personal information?
Preserve evidence, contact the relevant lender and report suspected fraud or unlawful conduct to the appropriate authorities. If financial credentials or funds are at risk, contact your bank promptly and use official cybercrime reporting channels where appropriate.
12. Can I apply again after a personal loan rejection?
You may be able to apply again, subject to lender policies. First review the reason for rejection, check your credit report and improve incomplete or inaccurate documentation where possible. Avoid repeated applications without addressing the underlying issue.
13. What happens if I miss a loan EMI because my income is delayed?
You may face applicable late-payment charges and negative credit-reporting consequences. Contact the lender as early as possible to discuss available options. Do not assume that a payment extension or restructuring will be approved automatically.
14. Where can I complain about a suspicious digital lending service?
Depending on the issue, you can report suspected cyber financial fraud through official cybercrime channels, use the RBI's Sachet portal for relevant unauthorised financial activity, or submit an eligible complaint against a regulated entity through the RBI Complaint Management System. Keep copies of all supporting evidence.
15. Does completing a loan safety checklist guarantee approval?
No. A checklist helps you identify potential risks and prepare your application. The lender makes the final decision based on its own eligibility requirements, verification and underwriting process.
16. Internal and External Linking Suggestions
Recommended internal links for Vizzve
Use these suggestions if the relevant pages exist on your website. Confirm each URL before publishing.
|
Suggested anchor text |
Recommended destination |
|---|---|
|
Personal loan eligibility guide |
Personal loan eligibility article |
|
Documents required for a personal loan |
Loan documentation guide |
|
How credit scores affect loan approval |
Credit score education article |
|
Understanding personal loan interest rates |
Interest rate and APR guide |
|
Personal loan repayment planning |
EMI and repayment guide |
|
Digital lending safety tips |
Digital lending safety article |
|
Loan eligibility for self-employed borrowers in Bengaluru |
Related Bengaluru eligibility guide |
Authoritative external references
-
RBI Digital Lending Directions, 2025: Reserve Bank of India official website — search the official site for the Digital Lending Directions, 2025.
-
RBI Digital Lending App Directory: Use the directory available through the RBI's official website to check claimed app associations.
-
RBI Sachet portal: Sachet — RBI financial activity reporting portal.
-
RBI Complaint Management System: RBI CMS — complaints against regulated entities.
-
TransUnion CIBIL: TransUnion CIBIL official website — credit information and credit-related educational resources.
RBI digital lending requirements and borrower safeguards are explained in its official directions and related publications.
17. Brand Promotion: Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before proceeding with any loan application, review the actual lending institution, its eligibility criteria, applicable fees and repayment conditions. Approval and disbursal depend on the relevant lender's assessment and terms.
Conclusion
A loan eligibility safety checklist can help self-employed borrowers in Bengaluru prepare their documents, understand their credit profile, compare borrowing costs and avoid suspicious loan offers.
Before applying, confirm that your income evidence is accurate, your proposed EMI is affordable during weaker months and the lender's identity and terms are independently verifiable. Read the KFS and loan agreement carefully, protect your financial credentials and keep a copy of your application records.
The safest borrowing decision is one that meets a genuine need without putting your future cash flow at risk. Explore available information at Vizzve Financial, compare your options carefully and apply only when you understand the full commitment.
18. Schema JSON-LD
Replace the sample URL, publication dates, author details and publisher logo with verified website information before publishing. Keep the structured data consistent with the visible article. FAQ structured data does not guarantee an FAQ rich result in Google Search.
BlogPosting Schema
Published on : 17th October 2026
Published by : Shanlee JV
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed