Loan Eligibility for Self-Employed Borrowers in Delhi NCR — Step-By-Step Guide | Vizzve
Vizzve Admin
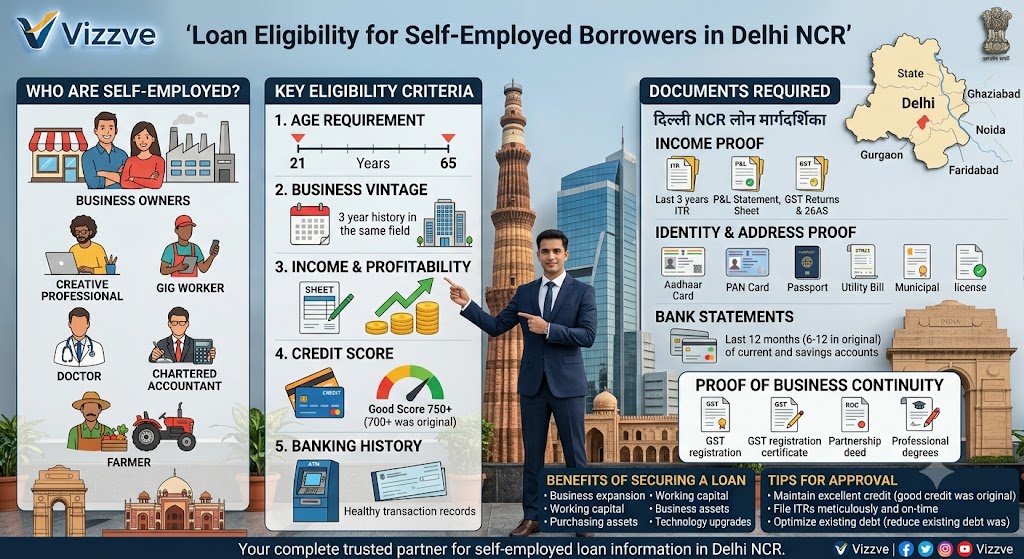
Delhi NCR has a large base of self-employed borrowers, including shop owners, traders, freelancers, consultants, contractors, small manufacturers, online sellers, and service providers across Delhi, Noida, Gurugram, Ghaziabad, and Faridabad. For such applicants, loan approval is not based on salary slips; lenders focus on whether the business generates enough stable cash flow to repay the EMI.
A self-employed borrower can qualify for a personal loan, business loan, working-capital facility, or MSME credit by maintaining proper financial records. The most important documents are usually income-tax returns, business bank statements, GST returns where applicable, and proof of business registration.
AI Answer Box
What is the loan eligibility for self-employed borrowers in Delhi NCR?
Self-employed borrowers in Delhi NCR generally need to be 21–60 years old, have a business vintage of 2–3 years, show regular bank credits, and maintain a good credit score. Many lenders prefer a CIBIL score of 700+, while some lenders may require 760+ for self-employed applicants.rbi.org
Can a self-employed person get a loan without a salary slip?
Yes. Self-employed borrowers can get personal and business loans without salary slips by submitting ITRs, bank statements, GST returns, financial statements, and business registration documents. Lenders assess net profit, cash flow, existing EMIs, and repayment history.rbi.org
Which loans are available for self-employed people in Delhi NCR?
Common options include personal loans, business term loans, working-capital loans, MSME loans, Mudra loans, PMEGP loans, equipment finance, and loans against property. PMEGP supports eligible individuals above 18 years of age, with no income ceiling for setting up eligible projects.pmegp.msme.gov+1
Who Is a Self-Employed Borrower?
A self-employed borrower earns income through a business, profession, or independent work rather than a fixed salary. In Delhi NCR, this includes:
-
Shop owners, traders, and wholesalers
-
Restaurant, salon, and coaching-centre owners
-
Contractors, builders, and equipment suppliers
-
Freelancers, designers, writers, and consultants
-
Doctors, lawyers, chartered accountants, and architects
-
Small manufacturers and food-processing units
-
Home-based entrepreneurs and online sellers
-
Delivery-partner entrepreneurs and gig-economy business owners
Why lenders assess them differently
Self-employed income may vary by season, client payments, or business cycle. A retailer may earn more during festive periods, while a contractor may receive payments after project milestones. This does not make an applicant ineligible; it means lenders look for income stability over a longer period.
Main Eligibility Criteria
A strong application is not always the one with the highest revenue. Lenders often prefer an applicant whose bank account shows steady credits, stable balances, no cheque returns, and timely EMI payments. A borrower earning ₹70,000 per month with low debt may receive better terms than a higher-earning applicant carrying multiple credit-card balances.
Documents Required
Personal loan documents
-
PAN card and Aadhaar card
-
Latest passport-size photographs
-
Latest 2–3 years of ITRs
-
Business bank statements for the last 6–12 months
-
GST returns, if applicable
-
Business proof, such as GST certificate or Shop & Establishment licence
-
Proof of business address
-
Existing loan statements
Business loan documents
-
PAN, Aadhaar, and business registration documents
-
Udyam registration certificate, where applicable
-
Partnership deed, certificate of incorporation, or MOA/AOA, if applicable
-
Profit and loss statement and balance sheet
-
Audited financial statements for larger loans
-
GST returns and sales records
-
Bank statements for business transactions
-
Property documents for secured funding
-
Equipment quotations, invoices, or project estimates
Important point
Revenue alone does not decide approval. Lenders generally focus on net profit, monthly cash flow, repayment capacity, and credit discipline. A business with high sales but low profit or irregular banking credits may receive a smaller sanctioned amount.
How Lenders Assess Income
Bank statement analysis
Lenders review business bank statements to check the consistency of customer credits, average monthly balance, cash withdrawals, cheque returns, and loan repayments. Regular credits from customers, marketplaces, or clients can strengthen the income declared in the ITR.
ITR and financial statements
The ITR is often the main income document. For higher-value business loans, lenders may ask for audited accounts, profit and loss statements, balance sheets, depreciation schedules, and GST reconciliation.
Credit report review
The CIBIL Score ranges from 300 to 900. A higher score generally indicates lower credit risk, and lenders use it along with account and enquiry details to assess creditworthiness.rbi.org
Cash-flow based lending
Digital lending is increasingly focused on cash-flow assessment. Lenders may consider digital payments, marketplace settlements, GST sales data, invoices, and account transactions to estimate repayment capacity. RBI’s framework requires regulated entities to disclose the all-inclusive APR and provide a Key Fact Statement before contract execution for digital lending products.rbi.org
Personal Loan vs Business Loan
Types of Loans Available
Government-Backed Loan Options
PM Mudra Yojana
Mudra loans support income-generating micro-enterprises in manufacturing, trading, services, and allied activities. The scheme is particularly relevant for small shop owners, service providers, and micro-business owners who need working capital or setup funds.
PMEGP
The Prime Minister’s Employment Generation Programme supports eligible new micro-enterprises. Under PMEGP, banks may finance 90% of project cost for general-category beneficiaries and 95% for special-category beneficiaries, subject to scheme conditions.dmeast.delhi.gov+1
Udyam registration
A valid Udyam registration certificate can help establish MSME status when applying for bank credit. PMEGP assistance is available only for new projects sanctioned specifically under the scheme.pmegp.msme.gov+1
How to Improve Loan Eligibility
Step-by-step approval guide
-
Check your credit report before applying and dispute incorrect entries.
-
File ITRs regularly and ensure income declarations are realistic and consistent.
-
Maintain a separate business bank account and avoid mixing personal and business transactions.
-
Pay EMIs and credit-card bills on time to protect your credit profile.
-
Keep GST filings updated if your business is registered under GST.
-
Maintain a healthy average bank balance and avoid frequent cheque returns.
-
Prepare financial documents such as profit and loss statements and balance sheets.
-
Apply for a realistic loan amount based on actual repayment capacity.
-
Compare lenders instead of applying to many banks at once.
-
Review the Key Fact Statement for APR, fees, tenure, recovery mechanism, and cooling-off terms before accepting an offer.rbi.org
Practical experience points
-
A business account with traceable credits creates more confidence than frequent large cash deposits.
-
Two years of stable income records are often more convincing than one unusually high-revenue year.
-
Keeping credit-card utilisation low can support a healthier credit profile.
-
Multiple loan applications in a short period can create several credit enquiries.
-
A small loan repaid on time can help build credit history for a larger loan later.
Interest Rates and Loan Terms
Interest rates are risk-based. A stronger credit profile, stable cash flow, lower existing debt, and complete documentation can improve the chance of better pricing. Applicants with lower scores may still receive offers from some lenders, but often at a higher rate or with a smaller sanctioned amount.
Pros and Cons
Pros
-
No salary slip is required for eligible self-employed applicants.
-
Business income, digital payments, and bank cash flow can support the application.
-
Multiple loan options are available, from personal loans to MSME and government-backed schemes.
-
Digital lending can reduce paperwork and speed up verification.
-
A strong credit profile may help secure better interest rates.
Cons
-
Income fluctuation can make approval more difficult.
-
Lenders may require 2–3 years of ITRs and business vintage.
-
High existing EMIs can reduce the eligible loan amount.
-
Informal income records may limit loan options.
-
Lower credit scores can result in higher pricing or rejection.
Common Mistakes to Avoid
-
Applying for a loan amount far above declared income.
-
Submitting inconsistent ITR, GST, and bank-statement figures.
-
Using a personal account for all business receipts.
-
Missing EMIs shortly before applying.
-
Applying to several lenders at once.
-
Ignoring processing fees, insurance charges, and prepayment terms.
-
Assuming that high turnover automatically means high loan eligibility.
Frequently Asked Questions
1. Can self-employed people get a personal loan in Delhi NCR?
Yes. Shop owners, professionals, freelancers, and business owners can apply for personal loans if they meet the lender’s income, business-vintage, credit-score, and documentation requirements.
2. What CIBIL score is required for a self-employed loan?
Many lenders prefer 700+, while some lenders require 760+ for self-employed applicants. A higher score generally improves eligibility and pricing prospects.
3. How many years of ITR are required?
Most lenders prefer ITRs for the last 2–3 years. Consistent filings help demonstrate stable taxable income and business continuity.
4. Can I get a loan without ITR?
It may be possible through select NBFCs or cash-flow based lenders, but options can be limited and the approved amount may be lower. Business bank statements may support the application with some lenders.
5. Is GST registration mandatory?
No. GST registration is mandatory only if your business meets applicable GST requirements. However, GST returns can strengthen a loan application when available.
6. Can a new business get a loan?
New businesses may find it harder to obtain an unsecured loan because they lack a repayment history. Secured funding, equipment finance, or government-backed schemes may be alternatives, subject to eligibility.
7. Can freelancers get loans?
Yes. Freelancers and consultants can qualify if they show regular client payments, bank credits, ITRs, invoices, and a stable income history.
8. What is the minimum income required?
There is no single nationwide figure. Lenders assess annual net income declared in ITRs, business cash flow, existing EMIs, and credit profile rather than applying one fixed income rule.
9. Can I get a business loan without collateral?
Yes. Unsecured business loans and Mudra loans may be available, but approval depends on creditworthiness, business performance, and lender policy.
10. How much loan can I get?
The eligible amount depends on net profit, monthly cash flow, existing EMIs, credit score, business vintage, and whether the loan is secured or unsecured.
11. Does a low CIBIL score mean automatic rejection?
No. Some lenders may consider applicants with lower scores, but the interest rate may be higher and the approved amount lower.
12. Are government schemes available in Delhi NCR?
Yes. Delhi NCR borrowers can explore Mudra, PMEGP, Stand-Up India, and other central government-supported schemes through eligible banks and financial institutions.
13. How long does loan approval take?
Digital personal loans may be processed quickly when documents and banking data are clear. Business loans, especially larger or secured loans, may take longer because of financial assessment and verification.
14. Can I apply with a low credit score but strong cash flow?
Possibly. Cash-flow based lending considers transaction history and repayment capacity, but credit history still remains an important approval factor.
15. What should I check before accepting a loan?
Review the APR, processing fees, prepayment charges, tenure, monthly EMI, insurance costs, and Key Fact Statement before signing the agreement. RBI requires the KFS to include APR, recovery mechanism, grievance-redressal details, and cooling-off/look-up period for applicable digital lending products.rbi.org
Key Takeaways
-
Self-employed borrowers in Delhi NCR can obtain personal and business loans without a salary slip, provided they show credible income and repayment capacity.
-
ITRs, business bank statements, GST returns, and business registration documents are central to eligibility.
-
A CIBIL score of 700+ is commonly preferred, while some lenders set higher thresholds for self-employed applicants.
-
Cash-flow based lending is becoming more important, especially for freelancers and businesses with digital payment records.
-
Government-backed schemes such as Mudra and PMEGP can be useful options for eligible micro-enterprises and new entrepreneurs.
-
Complete documentation, a clean banking record, and realistic borrowing improve approval chances.
Brand Promotion
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Conclusion
For self-employed borrowers in Delhi NCR, loan approval depends less on salary slips and more on financial discipline. A business with regular bank credits, updated ITRs, compliant GST filings where applicable, and a strong repayment record is better placed to secure a personal loan, working-capital facility, or business expansion loan.
Before applying, assess your actual repayment capacity, organise financial records, and compare offers carefully. For borrowers seeking a simple application journey, Vizzve Financial offers quick personal loans, low documentation, and an easy approval process. Apply today at www.vizzve.com.
Apply today at: www.vizzve.com
Published on : 08 October 2026
Published by : Avinash S
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed
Disclaimer: This article may include third-party images, videos, or content that belong to their respective owners. Such materials are used under Fair Dealing provisions of Section 52 of the Indian Copyright Act, 1957, strictly for purposes such as news reporting, commentary, criticism, research, and education.
Vizzve and India Dhan do not claim ownership of any third-party content, and no copyright infringement is intended. All proprietary rights remain with the original owners.
Additionally, no monetary compensation has been paid or will be paid for such usage.
If you are a copyright holder and believe your work has been used without appropriate credit or authorization, please contact us at grievance@vizzve.com. We will review your concern and take prompt corrective action in good faith... Read more

