

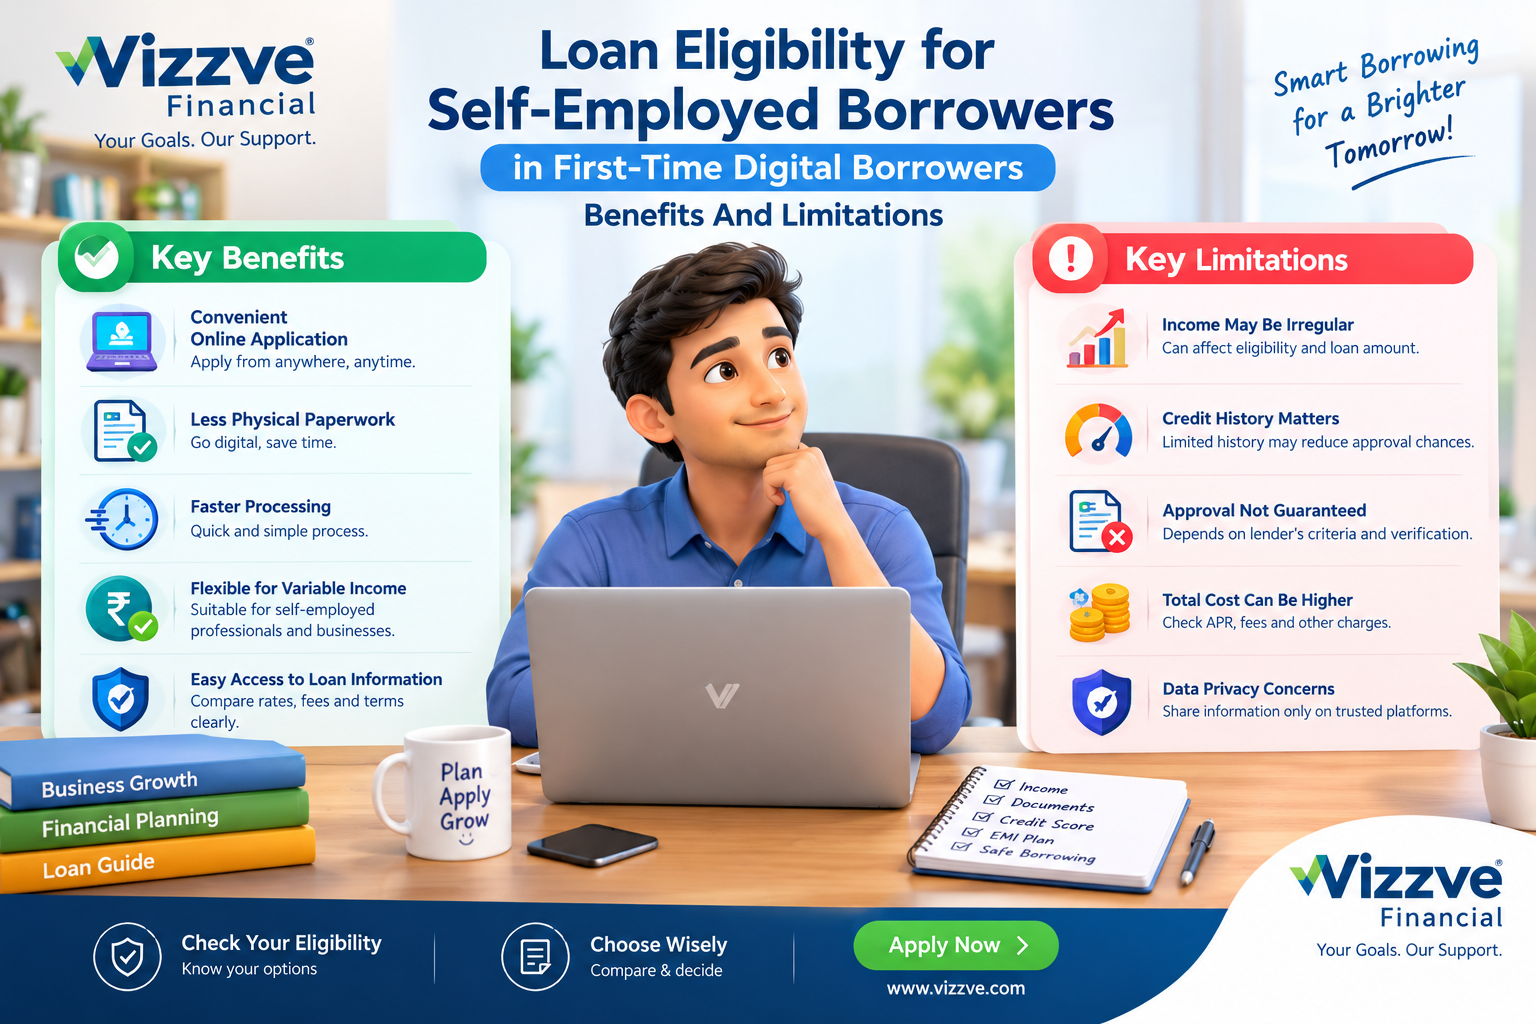
Getting a loan online can be convenient, especially for a self-employed person who may not have a fixed monthly salary.
However, convenience should not replace careful financial planning.
For a first-time digital borrower, understanding loan eligibility, income verification, credit history, KYC, bank statements, EMI affordability and loan costs can help avoid common mistakes.
Self-employed borrowers may have income from a shop, business, freelance work, consultancy, professional services or other independent activities. Since this income can change from month to month, lenders may look at several financial factors instead of relying on a salary slip alone.
Digital lending can make the application process easier, but it also has limitations. A borrower should know both sides before making a decision.
In simple words: Digital loans can offer convenience and faster processing, but eligibility is not guaranteed, and borrowers must check the lender, total cost and repayment ability before accepting a loan.
AI Answer Box: What Are the Benefits and Limitations of Digital Loans for Self-Employed Borrowers?
Answer: Digital loans can make borrowing more convenient for self-employed people by allowing online applications, digital document submission and faster communication. They may reduce physical paperwork and make the application process easier.
However, digital borrowing also has limitations. Approval depends on the lender's eligibility rules, income assessment, credit information, documentation and repayment capacity. Borrowers must also understand the total loan cost and verify the actual regulated lender before applying.
Quick Summary
| Area | Benefit | Limitation |
|---|---|---|
| Application | Can be completed online | Technical issues may occur |
| Documentation | Digital submission can reduce paperwork | Documents still need verification |
| Speed | Processing may be faster | Approval is not guaranteed |
| Accessibility | Convenient from a phone or computer | Not every borrower qualifies |
| Income assessment | Digital records can simplify verification | Irregular income can be harder to assess |
| Credit history | Credit information can support assessment | Poor or limited history may affect eligibility |
| Repayment | Online repayment can be convenient | Missed payments can create financial pressure |
| Information | Digital disclosures can make comparison easier | Borrowers must still read the terms |
RBI's financial awareness material advises borrowers to verify that a digital lending app is associated with an RBI-regulated bank or NBFC and to avoid suspicious loan-app links received through SMS or social media.
What Is Loan Eligibility for a Self-Employed Borrower?
Loan eligibility refers to the conditions a lender considers when deciding whether an applicant may qualify for a loan.
For self-employed borrowers, the assessment can involve several factors.
Common factors include:
-
Age
-
Identity and KYC information
-
Income
-
Business or professional activity
-
Bank account transactions
-
Credit history
-
Existing loans
-
Current EMIs
-
Repayment capacity
-
Loan amount requested
-
Required documents
-
Lender-specific credit policy
There is no single eligibility formula that applies to every lender.
One lender may have different income requirements, documentation rules or credit policies from another.
This means that not being eligible with one lender does not automatically mean you will have the same result everywhere.
Benefits of Digital Loans for Self-Employed Borrowers
1. Convenient Online Application
One of the biggest advantages is convenience.
Instead of visiting a branch for every step, borrowers may be able to complete parts of the process online.
Depending on the lender and product, the process can include:
-
Online application
-
Digital KYC
-
Document upload
-
Financial information submission
-
Credit assessment
-
Loan agreement
-
Digital communication
-
Online repayment
This can be useful for business owners, freelancers and professionals who have limited time during working hours.
2. Less Physical Paperwork
Digital processes can reduce the need to carry multiple physical documents.
A borrower may be able to submit information electronically through a secure application or website.
However, "digital" does not mean "no verification."
The lender may still ask for documents or additional information when required.
3. Faster Application Processing
Digital technology can automate several parts of an application.
For example, information can be collected electronically and passed through verification systems.
This may reduce processing time compared with some traditional processes.
But borrowers should remember:
Faster processing does not mean guaranteed approval.
A lender still needs to assess the application according to its policies.
4. Useful for People With Variable Income
Self-employed people often have income that changes from month to month.
A digital application can make it easier to submit different types of financial information where the lender supports them.
For example:
-
Bank statements
-
Business information
-
Income records
-
Existing credit information
-
KYC details
The actual documents required depend on the lender and loan product.
5. Easy Access to Loan Information
A well-designed digital lending process can provide borrowers with important information electronically.
For digital lending by regulated entities, RBI's framework includes disclosure of the all-inclusive cost through the Annual Percentage Rate (APR), as well as requirements around consent and data handling.
This can help borrowers compare the financial impact of borrowing.
Limitations of Digital Loans for Self-Employed Borrowers
Digital borrowing is convenient, but it is not suitable for every situation.
1. Irregular Income Can Affect Eligibility
A self-employed person's income may be different every month.
For example:
-
January: ₹45,000
-
February: ₹38,000
-
March: ₹52,000
-
April: ₹31,000
A borrower should not assume that the highest monthly income represents normal earnings.
Lenders may assess income using their own methods.
Better approach
Before applying, calculate a realistic average and consider regular business and household expenses.
2. Limited Credit History Can Be a Challenge
First-time borrowers may have limited credit information.
Credit history helps lenders understand past borrowing and repayment behaviour.
RBI has directed credit information companies to provide individuals with one free full credit report, including credit score, once in a calendar year when credit history is available.
Before applying, checking your credit report can help identify:
-
Incorrect personal information
-
Unknown accounts
-
Overdue payments
-
Incorrect outstanding balances
-
Reporting problems
3. Approval Is Not Guaranteed
A common misunderstanding is that completing an online application means the loan will be approved.
That is not correct.
The lender may reject or modify an application based on:
-
Income
-
Credit information
-
Existing debt
-
Documents
-
Repayment capacity
-
Internal risk policies
-
Other eligibility conditions
A digital platform can simplify the application process, but it cannot guarantee that every applicant will receive a loan.
4. Loan Cost Can Be Higher Than Expected
Borrowers sometimes focus only on the interest rate.
That can be a mistake.
Before accepting a loan, check:
-
Interest rate
-
APR
-
Processing fee
-
Applicable taxes
-
Other disclosed charges
-
Late-payment charges
-
Repayment schedule
-
Prepayment or foreclosure terms, where applicable
RBI's framework and related guidance emphasize transparent disclosure of loan costs, including APR and key loan information.
5. Digital Privacy Requires Attention
A loan application can involve personal and financial information.
Borrowers should understand:
-
What information is being collected
-
Why it is required
-
Who is processing it
-
What consent is being requested
-
How information is handled
RBI's digital lending framework includes requirements for need-based data collection, explicit borrower consent and privacy policies.
Benefits vs Limitations: A Simple Comparison
| Benefit | What It Means | Limitation |
|---|---|---|
| Online application | Apply digitally | Requires internet and a suitable device |
| Faster processing | Some checks can be automated | Final approval still depends on assessment |
| Digital documents | Easier submission | Verification is still required |
| Convenient repayment | Payments can often be made online | Missed payments can affect finances |
| Easy access | Useful for busy self-employed people | Easy access can also encourage unnecessary borrowing |
| Digital verification | Can reduce manual steps | Technical or verification issues can delay processing |
| Transparent disclosures | Important loan details can be provided digitally | Borrower must read and understand them |
What Should Self-Employed Borrowers Check Before Applying?
1. Check Your Monthly Income
Start with your actual income.
Do not use an unusually high month to decide what EMI you can afford.
Consider:
Average income – regular expenses – existing EMIs = money available for new financial commitments
This is a simple personal budgeting method, not a universal lender formula.
2. Check Your Existing EMIs
Make a list of every current repayment.
| Financial obligation | Monthly payment |
|---|---|
| Existing loan | ₹____ |
| Credit card payment | ₹____ |
| Business borrowing | ₹____ |
| Other obligations | ₹____ |
| Proposed new EMI | ₹____ |
| Total | ₹____ |
This gives you a clearer picture before taking another loan.
3. Check Your Credit History
Review your credit report before submitting applications.
A good repayment record can demonstrate responsible borrowing behaviour.
If you find an error, consider raising a correction request with the relevant credit information company or lender.
RBI's credit-reporting framework has also moved toward more frequent updating of credit information, with fortnightly reporting requirements effective from January 1, 2025.
4. Keep KYC Documents Ready
Depending on the lender, you may need:
-
PAN
-
Aadhaar or another accepted identity document
-
Address details
-
Bank information
-
Income information
-
Business or professional details
Do not send sensitive documents to unknown individuals or suspicious links.
5. Verify the Actual Lender
This is one of the most important checks.
A digital lending app may be operated by or work with a regulated bank or NBFC.
RBI specifically advises borrowers to verify the association between a digital lending app and the relevant regulated bank or NBFC through the bank/NBFC's website.
Be careful if an application:
-
Promises guaranteed approval
-
Hides the actual lender
-
Pressures you to act immediately
-
Requests unnecessary personal information
-
Comes through an unknown SMS or social-media link
-
Does not clearly explain loan charges
RBI's financial awareness material also warns borrowers about suspicious loan apps and recommends avoiding apps received through SMS or social-media links.
How to Decide Whether a Digital Loan Is Suitable
Ask yourself these five questions:
Question 1: Do I really need the loan?
Borrowing should have a clear purpose.
Question 2: Can I afford the EMI?
Consider income, expenses and existing repayments.
Question 3: Do I understand the total cost?
Check APR, fees and other charges.
Question 4: Is the lender legitimate?
Verify the actual regulated entity.
Question 5: Have I read the important terms?
Read the KFS and loan agreement before accepting.
If you cannot answer these questions clearly, take more time before proceeding.
Step-by-Step Guide for First-Time Digital Borrowers
Step 1: Understand Your Financial Position
Write down:
-
Monthly income
-
Regular expenses
-
Existing EMIs
-
Savings
-
Amount you actually need
Step 2: Review Your Credit Information
Check your credit report and identify any errors or overdue accounts.
Step 3: Prepare Your Documents
Keep required KYC and financial documents ready.
Step 4: Compare Loan Options
Do not choose only because an advertisement says "fast" or "easy."
Compare:
-
Loan amount
-
Interest rate
-
APR
-
Fees
-
Tenure
-
EMI
-
Repayment terms
Step 5: Verify the Lender
Check the actual bank or NBFC involved.
Step 6: Read the KFS
Review the key loan information before accepting the offer.
Step 7: Check Your EMI Again
Ask whether you can pay it during a weaker business month.
Step 8: Apply Carefully
Use the lender's legitimate website or application.
Step 9: Save Your Documents
Keep copies of the loan agreement, KFS, repayment schedule and payment records.
Real-World Example
Consider a freelance designer who earns around ₹40,000 to ₹55,000 in different months.
The designer wants a loan for a business requirement.
Instead of looking only at the highest income month, the borrower reviews:
-
Average income
-
Software and business expenses
-
Household expenses
-
Existing EMI
-
Proposed new EMI
-
Credit history
This gives a much clearer picture of affordability.
The lesson
Loan eligibility and loan affordability are not exactly the same thing.
You may qualify for a certain amount, but that does not automatically mean you should borrow the maximum amount available.
Expert Commentary
For self-employed borrowers, financial stability is often more important than simply showing a high income for one month.
A practical approach is to maintain clear banking records, keep documents updated, monitor existing debt and avoid taking a loan without understanding the complete repayment obligation.
Digital lending can make access to credit easier, but responsible borrowing still requires the same basic discipline:
Borrow only what you need, understand what you will repay and verify who is providing the loan.
RBI's digital-lending framework emphasizes transparency, borrower consent, responsible data practices and disclosure of important loan information.
Pros and Cons at a Glance
Pros
-
Convenient online application
-
Less physical paperwork in many cases
-
Digital document submission
-
Potentially faster processing
-
Convenient online communication
-
Easy access to loan information
-
Useful for busy self-employed borrowers
Cons
-
Approval is not guaranteed
-
Irregular income can make assessment more difficult
-
Limited credit history may affect eligibility
-
Borrowers may overlook fees
-
Easy access can encourage unnecessary borrowing
-
Personal data needs careful handling
-
Suspicious digital loan apps can create fraud risks
Key Takeaways
-
Digital loans can be convenient for self-employed borrowers.
-
Loan eligibility depends on the lender's assessment.
-
Income consistency matters when planning repayment.
-
Check your credit history before applying.
-
Keep KYC and financial documents ready.
-
Calculate existing and proposed EMIs.
-
Look at APR and total loan cost, not just the headline interest rate.
-
Read the Key Fact Statement and loan agreement.
-
Verify the actual regulated lender.
-
Never assume that online approval is guaranteed.
-
Protect personal and financial information.
-
Borrow only an amount that you can reasonably repay.
Vizzve Financial: Supporting Digital Borrowers
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before applying, borrowers should review the applicable eligibility criteria, loan costs, repayment terms and other conditions carefully.
For more information, visit Vizzve Financial.
Frequently Asked Questions
1. What are the benefits of digital loans for self-employed borrowers?
Digital loans can provide convenient online applications, digital document submission, faster processing in some cases and easier communication.
2. What are the limitations of digital loans?
Approval is not guaranteed, income verification may be more complex for people with variable earnings, and borrowers must carefully check loan costs, terms and data practices.
3. Can self-employed people apply for personal loans online?
Yes, self-employed individuals may apply for suitable personal loan products if they meet the lender's eligibility and verification requirements.
4. Does a first-time borrower need a credit score?
Requirements vary by lender. A first-time borrower may have limited credit history, so other financial information may also be considered.
5. What documents may be required from a self-employed borrower?
Depending on the lender, documents may include KYC documents, bank statements, income information and business or professional details.
6. How does income affect self-employed loan eligibility?
Lenders may assess income and repayment capacity according to their own credit policies. Regular and well-documented financial activity can help demonstrate the borrower's financial position.
7. Should I check my credit report before applying?
Yes. Checking your credit report can help you identify overdue accounts, incorrect information or other issues before applying.
8. What is APR?
APR, or Annual Percentage Rate, represents the annualised cost of credit under the applicable regulatory framework. It can help borrowers understand the overall cost of a digital loan.
9. How can I check whether a digital loan platform is legitimate?
Identify the actual regulated bank or NBFC behind the lending arrangement and verify the relationship through the institution's official website. RBI specifically recommends this approach.
10. Is fast online loan approval guaranteed?
No. Loan approval depends on the lender's eligibility criteria, verification, credit assessment, repayment capacity and other applicable conditions.
Conclusion
Digital lending can be useful for self-employed borrowers who want a convenient way to explore credit.
The biggest benefit is convenience: applications, document submission and communication can often happen online.
But convenience also comes with responsibility.
Before applying, check your income, credit history, bank records, existing EMIs, KYC documents and repayment capacity. Then verify the lender and understand the complete cost of the loan.
For first-time digital borrowers, the best decision is not necessarily the fastest loan.
It is the loan that you understand clearly, actually need and can repay comfortably.
If you are exploring digital loan support, visit Vizzve Financial and review the applicable eligibility requirements and loan terms before applying.
Published on : 3rd October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed