

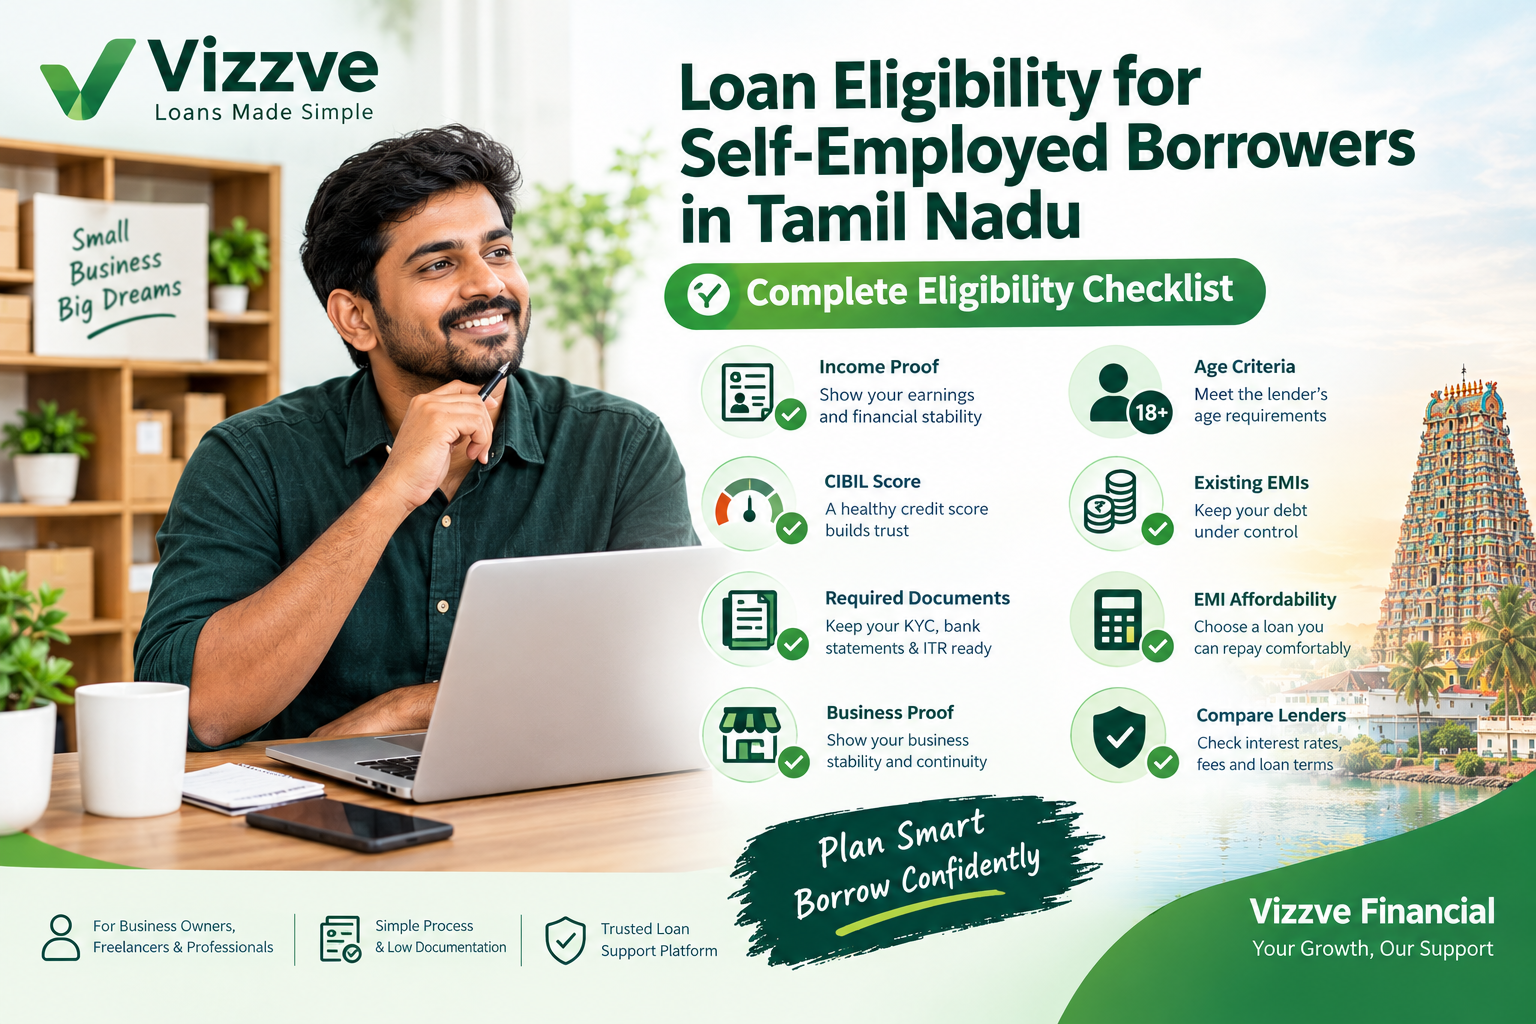
Getting a personal loan as a self-employed person can be different from applying as a salaried employee. Business owners, freelancers, consultants, traders and independent professionals may earn a regular income, but their earnings can fluctuate from month to month. This can make income verification an important part of the loan approval process.
For self-employed borrowers in Tamil Nadu, understanding eligibility requirements before applying can help reduce avoidable delays and improve the quality of a loan application.
Whether you operate a retail shop in Chennai, run a manufacturing business in Coimbatore, provide professional services in Madurai or work independently in Tiruchirappalli, lenders generally want to understand three things: how much you earn, whether your income is reasonably stable, and whether you can repay the loan on time.
The exact requirements vary by bank, non-banking financial company (NBFC), loan product and borrower profile. There is no single eligibility rule that applies to every lender.
This step-by-step guide explains how to check your eligibility, prepare the right documents, understand credit scores and apply responsibly.
AI Answer Box: What are the loan eligibility criteria for self-employed borrowers in Tamil Nadu?
Self-employed individuals in Tamil Nadu may qualify for a personal loan if they can demonstrate sufficient income, stable business activity, acceptable credit history and the ability to repay monthly instalments.
Lenders commonly assess:
-
Age: Must fall within the lender's permitted age range.
-
Income: Business or professional earnings sufficient to support repayments.
-
Business stability: Evidence that the business or professional activity has operated for an acceptable period.
-
Credit score: A stronger CIBIL score can improve the chances of approval.
-
Existing obligations: Current EMIs, credit card dues and other debts.
-
Documents: PAN, identity and address proof, bank statements, income tax returns and business documents, as applicable.
There is no universal minimum income, CIBIL score or business age for every lender. Applicants should check the specific lender's eligibility conditions before submitting an application.
1. Who is considered a self-employed borrower?
A self-employed borrower is someone who earns income through a business, professional practice, freelance work or independent commercial activity rather than relying solely on a regular salary from an employer.
In Tamil Nadu, this may include:
-
Shopkeepers and retail business owners.
-
Small manufacturers and wholesalers.
-
Restaurant and food-service operators.
-
Freelancers, designers and independent consultants.
-
Doctors, architects and other professionals in private practice.
-
Contractors, traders and service providers.
-
Online sellers and independent entrepreneurs.
A self-employed person can earn a good income without receiving the same amount every month. Lenders therefore assess the broader financial picture, including income records, banking transactions, business continuity and repayment capacity.
2. Basic eligibility criteria for self-employed borrowers
The following table provides a practical starting point. These are common assessment areas, not universal approval requirements.
|
Eligibility factor |
What lenders may assess |
|---|---|
|
Age |
Whether the applicant falls within the lender's age limits |
|
Business vintage |
How long the business has been operating |
|
Annual income |
Declared income and its consistency |
|
CIBIL score |
Credit history and repayment behaviour |
|
Bank statements |
Business receipts, cash flow and account conduct |
|
Income tax returns |
Reported income and financial consistency |
|
Existing EMIs |
How much income is already committed to debt |
|
Business proof |
Registration, licences or other evidence, where applicable |
Lenders may also consider the requested loan amount, tenure, occupation, location and the type of loan. Some products have stricter conditions than others.
What CIBIL score should a self-employed borrower have?
A CIBIL score ranges from 300 to 900. A higher score generally indicates a stronger credit history, but it does not guarantee approval. Lenders consider the score alongside income, existing debts and other application details.
As a practical guide:
-
Check your credit report before applying.
-
Pay existing EMIs and credit card bills on time.
-
Correct inaccurate account information or unfamiliar enquiries.
-
Avoid making numerous loan applications within a short period.
-
Keep credit card balances manageable.
A borrower with a limited credit history may still have options, depending on the lender's policy and the rest of the financial profile.
3. Documents required for a self-employed loan in Tamil Nadu
Preparing documents in advance can make the application process smoother. The exact list depends on the lender and loan product.
|
Document |
Why it may be required |
|---|---|
|
PAN card |
Tax identification and financial verification |
|
Aadhaar or another accepted identity document |
Identity verification, where accepted |
|
Address proof |
Confirmation of residential address |
|
Recent bank statements |
Review of income, cash flow and financial conduct |
|
Income tax returns (ITRs) |
Evidence of declared income |
|
Profit and loss statement |
Understanding business performance |
|
Balance sheet |
Reviewing assets, liabilities and financial position |
|
GST returns, if applicable |
Supporting evidence of business activity and turnover |
|
Business registration or licence |
Evidence of business identity and operations |
|
Office or business address proof |
Verification of business location |
Credit bureau guidance also lists bank statements, KYC documents and tax returns among documents commonly relevant to self-employed applicants. Requirements vary between lenders.
How can you organise your documents?
Step 1: Keep digital copies of your identity and address documents.
Step 2: Collect the bank statements for the period requested by the lender.
Step 3: Arrange available ITR acknowledgements and supporting financial statements.
Step 4: Check that your name, PAN details and business information match across the documents.
Step 5: Make sure uploaded files are clear, complete and current.
Step 6: Submit only the information requested through the lender's verified application channel.
A common avoidable problem is a mismatch between declared income and the cash flow visible in bank statements. Review these records before applying so you can explain legitimate differences, such as seasonal sales or business expenses.
4. Step-by-step guide to checking loan eligibility
Step 1: Identify your loan requirement
Decide whether you need a personal loan for an eligible personal expense or a business loan for working capital, equipment, inventory or expansion. The purpose can determine which product is most suitable.
Step 2: Calculate your actual income
Review your income after business expenses, taxes and other essential commitments. Do not assume that total sales or turnover is the same as personal income available for EMI payments.
Step 3: Review your credit profile
Obtain your credit report and review payment history, outstanding balances, loan accounts and recent enquiries. Resolve errors where possible before submitting a new application.
Step 4: Prepare financial documents
Gather your bank statements, ITRs, business proof and identity documents. Make sure the information is consistent and reflects your current financial circumstances.
Step 5: Estimate an affordable EMI
Use a loan calculator to estimate the monthly payment at different loan amounts, interest rates and tenures. Allow for months when business income may be lower.
Step 6: Compare suitable lenders
Check eligibility rules, interest rates, annual percentage rate (APR), processing fees, repayment terms and prepayment conditions. Do not choose an offer based on advertised speed alone.
Step 7: Submit your application carefully
Apply through the verified lender or its authorised partner. Read the loan terms before accepting an offer, and verify the final EMI and total repayment amount.
What should you check before submitting the application?
5. How do income and business stability affect eligibility?
For a self-employed applicant, income is not always as straightforward as a salary slip. A business may have busy and slow seasons, delayed customer payments, or expenses that vary from month to month.
Lenders may consider several indicators:
-
Income consistency: Whether earnings are reasonably stable over time.
-
Profitability: Whether the business generates income after expenses.
-
Banking behaviour: Whether account activity supports the income declared.
-
Business continuity: Whether there is evidence of ongoing operations.
-
Financial obligations: Whether the applicant has enough income left after existing repayments.
Example: A small business owner in Coimbatore
Consider a hypothetical textile trader whose monthly business receipts fluctuate between ₹1.5 lakh and ₹2.5 lakh. These figures represent turnover, not personal take-home income.
After paying suppliers, rent, wages, taxes and other expenses, the trader must calculate the amount genuinely available for household needs and debt repayments.
If the trader applies for a personal loan, the lender may review income tax returns, bank statements and existing EMIs to assess repayment capacity. Strong turnover alone does not guarantee approval.
Practical lesson: Maintain clear business accounts and separate personal and business transactions where feasible. Well-organised financial records can make income easier to explain and verify.
6. How much personal loan can a self-employed person afford?
There is no fixed loan amount available to every self-employed borrower in Tamil Nadu. The appropriate amount depends on verified income, current liabilities, the proposed interest rate, tenure and lender policy.
One useful starting point is to calculate your monthly repayment commitments:
For self-employed borrowers, the income figure should be realistic and consistent with the way the lender assesses income. A lender may use a different calculation from your own household budget.
Illustrative affordability comparison
Suppose an applicant has ₹60,000 per month available as assessed income and already pays ₹15,000 in EMIs.
|
Item |
Amount |
|---|---|
|
Monthly assessed income |
₹60,000 |
|
Existing monthly EMIs |
₹15,000 |
|
Existing EMI burden |
25% |
|
Proposed new EMI |
₹6,000 |
|
Total monthly EMIs after borrowing |
₹21,000 |
|
Combined EMI burden |
35% |
These figures are illustrative, not an eligibility threshold or a promise of approval. Even when the ratio appears manageable, the borrower must still account for household expenses, taxes, business cash-flow needs and emergency savings.
Estimate a possible EMI
Use this calculator to explore an example loan. It does not check actual lender eligibility.
Personal loan EMI calculator
₹3,00,000
16%
36 months
Estimated monthly EMI
₹10,547
Total repayment
₹3,79,696
Total interest
₹79,696
Illustrative calculation using a fixed annual interest rate and monthly reducing balance. Fees, taxes, insurance and other charges are excluded. Actual lender terms may differ.
7. Personal loan vs business loan: Which is more suitable?
Self-employed people often consider personal loans and business loans for different financial needs. Choosing the right product can help prevent unnecessary borrowing costs.
|
Feature |
Personal loan |
Business loan |
|---|---|---|
|
Typical purpose |
Eligible personal expenses |
Business expenses and growth |
|
Income assessment |
Personal repayment capacity |
Business cash flow and financials, plus any personal assessment required |
|
Common documents |
KYC, bank statements and income proof |
Business records, bank statements, financial statements and KYC |
|
Collateral |
Often unsecured, subject to product terms |
May be secured or unsecured |
|
Interest and fees |
Vary by lender and borrower profile |
Vary by lender, product and risk profile |
|
Best consideration |
Personal need that fits the product terms |
Business need that fits the product terms |
Neither option is automatically cheaper or easier to obtain. Compare the complete cost and repayment terms before choosing.
8. Benefits and limitations of personal loans for self-employed borrowers
Benefits
-
Flexible use: An eligible personal loan can cover a variety of personal expenses.
-
No collateral in many products: Unsecured personal loans generally do not require property or other collateral.
-
Structured repayments: Fixed EMIs can make budgeting easier.
-
Potential online application: Some lenders support digital applications and document submission.
-
Credit-building opportunity: Timely repayments may support a positive credit history over time.
Limitations
-
Income verification can be detailed: Lenders may request several years of financial records or other evidence.
-
Rates may vary significantly: An applicant's credit profile and income affect available offers.
-
EMIs continue during slow months: Repayments can put pressure on seasonal businesses.
-
Approval is not guaranteed: Meeting basic criteria does not oblige a lender to sanction a loan.
-
Late payments can damage credit history: Missed instalments may affect future borrowing options.
CIBIL's personal loan guidance highlights the importance of credit history, income, existing EMI commitments and responsible repayment.
9. How can self-employed borrowers improve their loan eligibility?
Improving eligibility is not about presenting a perfect financial profile. It is about showing a lender that your income is verifiable, your finances are organised and your proposed repayments are affordable.
Practical steps to strengthen your application
-
File income tax returns accurately. Consistent, genuine financial records can help demonstrate your earnings.
-
Maintain healthy banking records. Record business receipts and payments clearly, and avoid unnecessary account irregularities.
-
Pay existing EMIs on time. A good repayment history can strengthen your credit profile.
-
Reduce outstanding debt where practical. Lower monthly obligations may leave more room for a new EMI.
-
Request a realistic loan amount. Borrowing less than the maximum potentially available can help manage repayment pressure.
-
Avoid multiple applications at once. Compare offers first and submit applications selectively.
-
Explain unusual income fluctuations. If your business is seasonal, keep genuine records that explain the changes.
-
Choose an appropriate tenure. A longer tenure may reduce the EMI but can increase total interest paid.
No action guarantees approval. The final decision rests with the lender's underwriting criteria and assessment of your application.
10. Important loan safety checks before applying online
Online loan applications can be convenient, but borrowers should verify the lender and understand the complete cost before accepting an offer.
The Reserve Bank of India (RBI) issued its Digital Lending Directions, 2025, addressing borrower creditworthiness, disclosures, lending-service-provider arrangements and customer protection.
Before accepting a digital loan:
-
Verify the actual bank or NBFC providing the loan.
-
Check whether the app or platform is associated with the lender it names.
-
Read the Key Facts Statement (KFS) and review the Annual Percentage Rate (APR).
-
Check processing fees, applicable taxes, late-payment charges and prepayment conditions.
-
Read the privacy policy and understand what information you are consenting to share.
-
Never pay an unknown person a supposed advance fee to guarantee loan approval.
-
Do not share your OTP, PIN or banking password with an agent.
-
Confirm that disbursement and repayment arrangements follow the lender's disclosed process.
The RBI's digital lending framework requires regulated lenders to provide a Key Facts Statement in accordance with applicable requirements. The KFS helps borrowers understand key loan terms and costs before committing.
For further information, consult the Reserve Bank of India and its digital lending app directory.
11. Vizzve Financial: Loan support for self-employed borrowers
Vizzve Financial is presented as a loan support platform for people exploring borrowing options. Self-employed applicants can use the information available through its official website to learn about relevant loan options and application requirements.
If you are exploring a personal loan, prepare your income records, review your credit profile and calculate an affordable EMI before beginning the process.
Explore Vizzve Financial: www.vizzve.com
Before submitting an application, verify the lender, applicable eligibility conditions, interest rate, fees and repayment terms. Approval, interest rates and disbursal timelines depend on the relevant lender and your individual profile; no outcome is guaranteed.
12. Expert guidance: What matters most for self-employed borrowers?
A practical way to assess a loan application is to look beyond turnover and focus on the income available for repayment.
For example, a consultant in Chennai may have high annual billings but also significant operating expenses and irregular client payments. A retailer in Salem may have consistent sales but substantial inventory costs. In both cases, the lender needs a reasonable picture of the applicant's financial capacity.
The following principles can help applicants make stronger decisions:
-
For eligibility: Keep income and business records accurate.
-
For affordability: Assess cash flow after essential expenses, not just gross receipts.
-
For creditworthiness: Maintain timely repayments and review your credit report.
-
For safety: Compare the complete borrowing cost, not only the advertised interest rate.
-
For long-term financial health: Maintain an emergency reserve where possible and avoid taking a loan simply because an offer is available.
These are practical financial-planning principles, not a guarantee that any lender will approve a loan.
13. Key takeaways
14. Frequently asked questions (FAQs)
1. Can self-employed people get a personal loan in Tamil Nadu?
Yes. Business owners, freelancers and independent professionals may qualify if they satisfy the lender's income, credit history, documentation and repayment-capacity requirements.
2. What is the minimum income required for a self-employed personal loan?
There is no universal minimum income across all lenders. Requirements depend on the loan product, requested amount, existing liabilities and the lender's assessment criteria.
3. What CIBIL score is needed for a self-employed loan?
A higher CIBIL score generally improves the likelihood of being considered favourably, but the minimum acceptable score varies by lender. A good score does not guarantee approval.
4. Can I get a personal loan without salary slips?
Yes. Self-employed applicants typically demonstrate income through documents such as income tax returns, bank statements and financial statements rather than salary slips.
5. Which documents are required for a self-employed loan?
Common requirements include PAN, accepted identity and address proof, bank statements, income tax returns and business documents. The exact list depends on the lender.
6. How many years should my business have been operating?
Some lenders require a minimum period of business activity, while others have different conditions. Check the specific product's requirements before applying.
7. Can a freelancer apply for a personal loan?
Yes. Freelancers may qualify if they can demonstrate sufficient income, an acceptable credit profile and repayment capacity through the documents requested by the lender.
8. Can I get a loan if my income changes every month?
Possibly. Lenders may review your income over time and assess its consistency, business continuity and available repayment capacity. Fluctuating earnings do not automatically mean rejection.
9. Does business turnover determine personal loan eligibility?
Not by itself. Turnover represents business receipts, whereas profitability and personal repayment capacity depend on expenses, liabilities and other financial factors.
10. Will checking my loan eligibility affect my CIBIL score?
Using an eligibility calculator generally does not require a hard credit enquiry. However, submitting a formal application may trigger a credit enquiry depending on the lender's process. Confirm this before proceeding.
11. Can I apply for a personal loan if I already have another loan?
Yes, potentially. The lender will assess your outstanding obligations and whether your available income can support the additional EMI.
12. Is a personal loan better than a business loan?
Neither is automatically better. A personal loan may suit eligible personal expenses, while a business loan may be more appropriate for business purposes. Compare costs and conditions for your specific need.
13. Can I apply online through Vizzve Financial?
You can visit Vizzve's official website to explore the services it offers. Verify the actual lending institution, eligibility rules and loan terms before submitting personal or financial information.
14. How long does loan approval take?
Processing times vary by lender, product, verification requirements and the completeness of your application. An online application does not guarantee instant approval or disbursal.
15. What should I do if my loan application is rejected?
Ask the lender about the reason where possible, review your credit report, correct documentation issues, reduce outstanding debt if practical and reassess affordability. Apply again when the underlying issue has been addressed rather than submitting repeated applications immediately.
15. Conclusion
Loan eligibility for self-employed borrowers in Tamil Nadu depends on more than the amount of money a business receives. Lenders need to understand income stability, financial records, credit history and the applicant's ability to manage monthly repayments.
By preparing accurate documents, checking your CIBIL report, estimating an affordable EMI and comparing loan offers carefully, you can approach the application process with greater confidence.
Whether you are a freelancer in Chennai, a trader in Coimbatore or a small business owner in Madurai, the goal should be to choose a loan that meets your needs without placing unnecessary pressure on your finances.
Ready to explore your options? Visit Vizzve Financial to learn more about its services. Always verify the lender's identity and review all loan terms before making a borrowing decision.
Internal and external linking suggestions
Internal links
Add links to relevant articles on your website using descriptive anchor text. Replace these suggested paths with the actual published URLs on Vizzve.
|
Suggested anchor text |
Suggested article URL |
|---|---|
|
Loan eligibility for self-employed borrowers in India |
|
|
Personal loan eligibility criteria |
|
|
How to improve your CIBIL score |
|
|
Documents required for an instant loan |
|
|
Understanding instant loan APR |
|
|
How to calculate personal loan EMI |
|
External links
-
TransUnion CIBIL — Personal Loans: Credit profile, loan factors and common documentation.
-
TransUnion CIBIL — Credit Score FAQs: Credit score basics and creditworthiness.
-
Reserve Bank of India: Official regulatory information.
-
RBI digital lending app directory: Check reported digital lending apps and their associated regulated entities.
16. Schema markup: BlogPosting + FAQPage
The following JSON-LD is a starting template for the published article. Replace the example image URL, canonical article URL, author details and publication dates with accurate values before publishing. Ensure that the structured data matches the visible article.
{
  "@context": "https://schema.org",
  "@graph": [
    {
      "@type": "BlogPosting",
      "@id": "https://www.vizzve.com/loan-eligibility-self-employed-borrowers-tamil-nadu/#article",
      "mainEntityOfPage": {
        "@type": "WebPage",
        "@id": "https://www.vizzve.com/loan-eligibility-self-employed-borrowers-tamil-nadu/"
      },
      "headline": "Loan Eligibility for Self-Employed Borrowers in Tamil Nadu — Step-By-Step Guide",
      "description": "Learn about loan eligibility for self-employed borrowers in Tamil Nadu, including income proof, credit score, required documents and application steps.",
      "author": {
        "@type": "Organization",
        "name": "Vizzve Financial"
      },
      "publisher": {
        "@type": "Organization",
        "name": "Vizzve Financial",
        "url": "https://www.vizzve.com/"
      },
      "datePublished": "REPLACE_WITH_ACTUAL_PUBLICATION_DATE",
      "dateModified": "REPLACE_WITH_ACTUAL_MODIFICATION_DATE",
      "image": "REPLACE_WITH_ACTUAL_ARTICLE_IMAGE_URL",
      "inLanguage": "en-IN",
      "keywords": [
        "loan eligibility for self-employed borrowers in Tamil Nadu",
        "self-employed personal loan",
        "self-employed loan documents",
        "CIBIL score for personal loan",
        "personal loan eligibility"
      ],
      "articleSection": [
        "Loan Eligibility",
        "Personal Finance",
        "Self-Employed Borrowers"
      ]
    },
    {
      "@type": "FAQPage",
      "@id": "https://www.vizzve.com/loan-eligibility-self-employed-borrowers-tamil-nadu/#faq",
      "mainEntity": [
        {
          "@type": "Question",
          "name": "Can self-employed people get a personal loan in Tamil Nadu?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Yes. Self-employed people may qualify if they meet the lender's income, credit history, documentation and repayment-capacity requirements."
          }
        },
        {
          "@type": "Question",
          "name": "What is the minimum income required for a self-employed personal loan?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "There is no universal minimum income across all lenders. Requirements depend on the loan product, requested amount, existing liabilities and lender criteria."
          }
        },
        {
          "@type": "Question",
          "name": "What CIBIL score is needed for a self-employed loan?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "A higher CIBIL score generally improves an applicant's prospects, but the minimum acceptable score varies by lender and does not guarantee approval."
          }
        },
        {
          "@type": "Question",
          "name": "Can I get a personal loan without salary slips?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Yes. Self-employed applicants can often demonstrate income through income tax returns, bank statements and financial statements instead of salary slips."
          }
        },
        {
          "@type": "Question",
          "name": "Which documents are required for a self-employed loan?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Common documents include PAN, accepted identity and address proof, bank statements, income tax returns and business documents. Requirements vary by lender."
          }
        },
        {
          "@type": "Question",
          "name": "How many years should my business have been operating?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Minimum business vintage requirements vary by lender and loan product. Applicants should check the specific eligibility criteria."
          }
        },
        {
          "@type": "Question",
          "name": "Can a freelancer apply for a personal loan?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Yes. Freelancers may qualify if they demonstrate sufficient income, an acceptable credit profile and repayment capacity."
          }
        },
        {
          "@type": "Question",
          "name": "Can I get a loan if my income changes every month?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Possibly. Lenders may review income over time, business continuity, financial records and available repayment capacity."
          }
        },
        {
          "@type": "Question",
          "name": "Does business turnover determine personal loan eligibility?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "No. Turnover alone does not establish repayment capacity. Lenders may also assess expenses, profitability, liabilities and personal income."
          }
        },
        {
          "@type": "Question",
          "name": "Will checking my loan eligibility affect my CIBIL score?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "An eligibility calculator generally does not require a hard enquiry, but a formal loan application may trigger a credit enquiry depending on the lender's process."
          }
        },
        {
          "@type": "Question",
          "name": "Can I apply for a personal loan if I already have another loan?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Yes, potentially. The lender will assess existing obligations and whether income can support the additional EMI."
          }
        },
        {
          "@type": "Question",
          "name": "Is a personal loan better than a business loan?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Neither is automatically better. Compare loan purpose, interest, fees, eligibility and repayment terms before choosing."
          }
        },
        {
          "@type": "Question",
          "name": "Can I apply online through Vizzve Financial?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "You can visit Vizzve's official website to explore its services. Verify the lending institution, eligibility rules and terms before applying."
          }
        },
        {
          "@type": "Question",
          "name": "How long does loan approval take?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Processing times vary by lender, product, verification requirements and the completeness of the application."
          }
        },
        {
          "@type": "Question",
          "name": "What should I do if my loan application is rejected?",
          "acceptedAnswer": {
            "@type": "Answer",
            "text": "Review the reason for rejection, check your credit report, correct documentation issues, reassess affordability and apply again when appropriate."
          }
        }
      ]
    }
  ]
}
SEO publishing note: Validate the JSON-LD with Google's Rich Results Test and Schema.org Validator before publishing. Structured data does not guarantee indexing or enhanced search results. Google currently limits FAQ rich results primarily to well-known, authoritative government and health websites, so adding FAQ markup does not guarantee an FAQ display for a financial website.
For stronger search visibility, publish the article at its final canonical URL, add relevant internal links, include a descriptive featured-image alt text, ensure the page is mobile-friendly, and submit the sitemap through Google Search Console. These steps can support discovery, but no technique guarantees fast indexing or a particular ranking.
Title
Loan Eligibility for Self-Employed Borrowers in Tamil Nadu — Step-by-Step Guide | Vizzve
Hashtags
#LoanEligibility #SelfEmployedLoans #TamilNadu #PersonalLoan #LoanForSelfEmployed #VizzveFinancial #LoanApplication #CIBILScore #PersonalFinance #LoanDocuments #BusinessOwners #SmallBusinessLoans #Freelancers #FinancialPlanning #LoanApproval #InstantLoan #CreditScore #TamilNaduFinance #SmartBorrowing #FinancialAwareness
Use this image for your blog featured image or social media post about Loan Eligibility for Self-Employed Borrowers in Tamil Nadu — Step-by-Step Guide | Vizzve.
Suggested image alt text: Loan eligibility for self-employed borrowers in Tamil Nadu, showing the steps to prepare documents, maintain a good credit score and apply for a personal loan.
Loan Eligibility for Self-Employed Borrowers in Tamil Nadu — Eligibility Checklist | Vizzve
SEO-optimised blog guide • Tamil Nadu, India • 2026
1. SEO metadata
-
Meta Title: Self-Employed Loan Eligibility Checklist in Tamil Nadu
-
Meta Description: Check loan eligibility for self-employed borrowers in Tamil Nadu with this practical checklist covering income, CIBIL score, documents, business proof and EMIs.
-
Slug:
self-employed-loan-eligibility-checklist-tamil-nadu -
Primary keyword: Loan eligibility for self-employed borrowers in Tamil Nadu
-
Secondary keywords: Self-employed loan eligibility checklist, personal loan for business owners, loan documents for self-employed, CIBIL score for personal loan.
-
OG Title: Self-Employed Loan Eligibility Checklist in Tamil Nadu | Vizzve
-
OG Description: Use this step-by-step eligibility checklist to prepare your income proof, financial documents and credit profile before applying for a loan.
-
Tags: Self-Employed Loans, Tamil Nadu Finance, Loan Eligibility, Personal Loan, CIBIL Score, Loan Documents, Small Business Finance, Financial Planning, Vizzve Financial
Keywords and long-tail keywords
-
Loan eligibility for self-employed borrowers in Tamil Nadu
-
Self-employed loan eligibility checklist
-
Personal loan for self-employed individuals
-
Loan eligibility criteria in Tamil Nadu
-
Self-employed personal loan documents
-
CIBIL score for self-employed loan
-
Business owner loan eligibility
-
Loan for freelancers in Tamil Nadu
-
Personal loan for shop owners
-
Income proof for self-employed borrowers
-
Bank statement requirements for personal loans
-
Business income verification for loans
-
Loan application checklist for business owners
-
How to improve loan eligibility
-
Personal finance for self-employed people
-
How to check personal loan eligibility in Tamil Nadu
-
Documents required for a self-employed personal loan in India
-
How to qualify for a loan without salary slips
-
How to check CIBIL score before applying for a loan
-
Loan eligibility checklist for small business owners
-
How to calculate EMI affordability with irregular income
-
Personal loan eligibility for freelancers in Chennai
-
How to prepare income tax returns for a loan application
2. Introduction
Getting a personal loan as a self-employed individual can require a little more preparation than applying as a salaried employee. Business owners, freelancers, consultants, traders and independent professionals may earn a good income, but their earnings can change from month to month.
For lenders, the important questions are whether your income can be verified, whether your financial position is stable enough and whether you can repay the loan comfortably.
If you run a business in Chennai, operate a shop in Coimbatore, provide professional services in Madurai or work independently in Tiruchirappalli, preparing an eligibility checklist before applying can help you identify missing documents and potential financial concerns.
The good news is that you do not necessarily need salary slips to apply for a loan as a self-employed borrower. Depending on the lender's requirements, income tax returns, bank statements and business financial records may help demonstrate your repayment capacity.
This guide explains the main eligibility factors, documents, credit checks and practical steps self-employed borrowers in Tamil Nadu should review before submitting a loan application.
3. AI Answer Box: What is the loan eligibility checklist for self-employed borrowers in Tamil Nadu?
Self-employed borrowers should review their income, business stability, credit history, existing loan obligations and documentation before applying for a personal loan.
The essential checklist includes:
-
Confirm that you meet the lender's age and other eligibility requirements.
-
Calculate your income after business expenses and taxes.
-
Review your CIBIL score and credit report.
-
Check existing EMIs and outstanding debts.
-
Prepare recent bank statements and income tax returns.
-
Keep accepted identity proof, address proof and business documents ready.
-
Calculate an affordable EMI.
-
Compare interest rates, APR, fees and repayment terms.
-
Verify the actual lending institution before applying.
There is no single income requirement, minimum business age or credit score that applies to every lender. Approval depends on the lender's criteria and your individual financial profile.
4. Why is a loan eligibility checklist important?
A checklist helps you prepare before the lender reviews your application. It can also help you identify problems that might otherwise delay processing.
For example, a small business owner may have healthy sales but limited profit after paying suppliers, rent and employee salaries. A freelancer may receive payments irregularly, while a consultant may have a strong annual income but several existing EMIs.
In each situation, the lender needs a clear picture of the applicant's ability to repay.
A pre-application checklist can help you:
-
Identify missing income documents.
-
Review your credit history before applying.
-
Estimate how much borrowing is affordable.
-
Avoid unnecessary loan applications.
-
Compare suitable loan products.
-
Understand the total cost of borrowing.
5. Complete loan eligibility checklist for self-employed borrowers
Use the following table as a practical starting point. The requirements listed are common assessment areas; the exact conditions depend on the lender and loan product.
|
Eligibility factor |
What you should check |
Ready? |
|---|---|---|
|
Age |
Meets the lender's permitted age range |
☐ |
|
Business activity |
Business or professional work can be verified |
☐ |
|
Income |
Earnings are documented and sufficient for repayment |
☐ |
|
Credit score |
Credit report has been reviewed |
☐ |
|
Repayment history |
Existing EMIs and bills are paid on time |
☐ |
|
Existing debt |
Current liabilities have been calculated |
☐ |
|
Bank statements |
Required statements are available |
☐ |
|
Income tax returns |
Requested ITRs are available |
☐ |
|
Business proof |
Applicable registration or licence documents are ready |
☐ |
|
KYC documents |
Accepted identity and address proof are ready |
☐ |
|
EMI affordability |
The proposed EMI fits your budget |
☐ |
|
Lender verification |
The lender and its terms have been checked |
☐ |
5.1 Age and basic eligibility
Banks and NBFCs set their own minimum and maximum age requirements. Before applying, check whether you fall within the permitted range for the selected loan.
Other basic requirements may include Indian residency, valid KYC documents and a verifiable source of income. These conditions vary by lender.
5.2 Business stability
Lenders may consider how long you have been operating your business or professional practice.
Evidence may include:
-
Business registration, where applicable.
-
GST registration or returns, where applicable.
-
Professional licences, where relevant.
-
Business bank statements.
-
Financial statements and income tax returns.
-
Records showing ongoing business activity.
A business registration certificate alone does not prove that the business generates sufficient income. Lenders may review several types of evidence together.
5.3 Income and repayment capacity
Your income should be assessed realistically. Business turnover is not the same as profit, and profit is not always the same as cash available for monthly repayments.
Calculate what remains after business expenses, taxes, household costs and existing loan commitments.
TransUnion CIBIL identifies income, credit history and EMI repayment patterns among factors lenders may consider when assessing personal loan applications.
6. Documents required for a self-employed personal loan
Having the right documents ready can make the application process easier.
|
Document |
Purpose |
|---|---|
|
PAN card |
Tax identification |
|
Aadhaar or another accepted identity document |
Identity verification |
|
Accepted address proof |
Residential address verification |
|
Recent bank statements |
Assessment of cash flow and account activity |
|
Income tax returns |
Evidence of declared income |
|
Profit and loss statement |
Assessment of business profitability |
|
Balance sheet, if applicable |
Overview of business assets and liabilities |
|
GST records, if applicable |
Supporting evidence of business activity |
|
Business registration or licence, if applicable |
Verification of business details |
|
Business address proof, if requested |
Verification of business location |
CIBIL's personal loan guidance lists KYC documents, bank statements, financial records and business-related information among common documentation considerations. The exact requirements may differ by lender.
Document preparation checklist
Practical tip: Keep personal and business transactions clearly recorded. Separate accounts, where feasible, can make it easier to explain business income and household expenses.
7. CIBIL score checklist: What should you review?
Your CIBIL score is one part of your credit profile. A stronger credit history may improve your chances of receiving favourable consideration, but it does not guarantee loan approval.
Before applying, review the following:
-
Payment history: Check for missed or delayed payments.
-
Outstanding balances: Review current loans and credit card dues.
-
Credit accounts: Confirm that listed accounts are accurate.
-
Recent enquiries: Check whether recent applications have generated enquiries.
-
Errors: Raise a dispute for inaccurate information through the appropriate credit bureau process.
There is no universal CIBIL score threshold for all self-employed personal loans. A lender may consider your income, repayment obligations and other factors alongside your score.
How can you improve your credit profile before applying?
-
Pay EMIs and credit card bills by their due dates.
-
Reduce high outstanding balances where practical.
-
Avoid submitting numerous applications in a short period.
-
Correct inaccuracies in your credit report.
-
Borrow only what your income can support.
8. How to calculate loan affordability with irregular income
Self-employed borrowers should not choose a loan solely because a lender appears willing to offer a particular amount. Monthly income can fluctuate, so affordability deserves special attention.
Use this simple calculation as a starting point:
The remaining amount must also account for taxes or other obligations not already deducted, emergency savings and unexpected business expenses.
Example: A self-employed business owner in Tamil Nadu
Consider a hypothetical business owner in Coimbatore with the following monthly figures:
|
Financial item |
Amount |
|---|---|
|
Income after business expenses and taxes |
₹70,000 |
|
Household and essential expenses |
₹25,000 |
|
Existing EMIs |
₹10,000 |
|
Amount remaining before new EMI and savings |
₹35,000 |
The ₹35,000 remainder is not automatically an appropriate EMI budget. The borrower still needs to account for savings, emergencies and fluctuations in business income.
A prudent applicant would test whether the proposed EMI remains manageable during a weaker business month.
Personal loan EMI calculator
Adjust the figures to estimate your monthly instalment and total interest. This is an illustration, not a loan eligibility assessment.
Estimate your loan EMI
₹2,00,000
16%
Estimated monthly EMI
₹7,031
Total repayment
₹2,53,131
Total interest
₹53,131
Estimates use a fixed annual rate and monthly reducing balance. Fees, taxes, insurance and other charges are excluded. Actual loan te
#LoanEligibility #SelfEmployedLoans #TamilNadu #VizzveFinancial #PersonalLoan #LoanEligibilityChecklist #SelfEmployedBorrowers #CIBILScore #LoanDocuments #PersonalFinance #SmallBusinessLoans #BusinessOwners #Freelancers #LoanApplication #CreditScore #FinancialPlanning #LoanApproval #TamilNaduFinance #SmartBorrowing #FinancialAwareness
Disclaimer: This article may include third-party images, videos, or content that belong to their respective owners. Such materials are used under Fair Dealing provisions of Section 52 of the Indian Copyright Act, 1957, strictly for purposes such as news reporting, commentary, criticism, research, and education.
Vizzve and India Dhan do not claim ownership of any third-party content, and no copyright infringement is intended. All proprietary rights remain with the original owners.
Additionally, no monetary compensation has been paid or will be paid for such usage.
If you are a copyright holder and believe your work has been used without appropriate credit or authorization, please contact us at grievance@vizzve.com. We will review your concern and take prompt corrective action in good faith... Read more