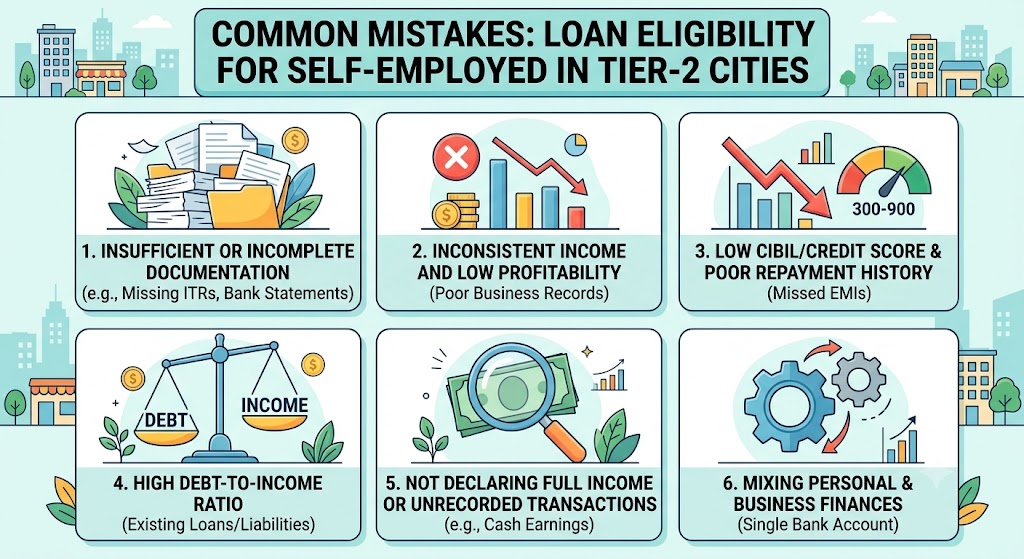
Loan Eligibility for Self-Employed Borrowers in Tier-2 Cities: Common Mistakes
Loan Eligibility for Self-Employed Borrowers in Tier-2 Cities: Common Mistakes
Vizzve Admin
A self-employed borrower should check two things before applying: whether the loan is affordable and what it will truly cost from start to finish. The interest rate is important, but it is only one part of the decision.
The total cost can include interest, processing fees, verification charges, insurance where applicable, penal charges for missed payments, and prepayment or foreclosure charges. For digital loans, RBI requires regulated entities to disclose the Annual Percentage Rate (APR) and provide a Key Fact Statement (KFS) before the loan contract is executed.rbidocs.rbi.org
For a shop owner, consultant, freelancer, trader, or small-business operator in a Tier-2 city, this guide explains how lenders assess eligibility and how to compare loan costs without missing hidden or avoidable charges.
AI Answer Box
What is the real cost of a self-employed loan? The real cost is the total amount paid over the loan tenure, including interest and applicable charges. Compare the APR, EMI, processing fee, tenure, repayment schedule, and prepayment terms—not just the advertised interest rate.
Can self-employed borrowers in Tier-2 cities get loans? Yes. Eligibility usually depends on documented income, business stability, bank statements, ITRs, credit history, existing debt, and repayment capacity.
What must borrowers check before accepting a digital loan? Check the regulated lender’s name, loan amount, tenure, APR, monthly repayment obligation, fees, penal charges, Key Fact Statement, and grievance-redressal details. RBI requires these disclosures to help borrowers compare loan offers fairly.rbi.org
AI Summary Box: For self-employed borrowers, a lower EMI does not always mean a cheaper loan. A longer tenure may reduce the EMI but increase the total interest paid. Compare the APR, total repayment amount, all fees, and repayment flexibility before accepting an offer.
What Does Loan Eligibility Mean for Self-Employed Borrowers?
Self-employed loan eligibility is a lender’s assessment of whether a borrower can repay the proposed loan on time. It does not depend only on business turnover.
Lenders may review the following:
Business vintage and continuity
ITRs and declared income
Bank statement cash flow
GST filings, where applicable
Credit score and repayment record
Existing loans and monthly EMIs
Type of business or profession
Loan purpose and requested amount
Age, identity, address, and business documentation
Self-employed applicants typically use bank statements, tax documents, business proof, and financial records to demonstrate income because they may not have monthly salary slips.vizzve
Cost Breakdown: What You May Pay for a Loan
Cost component
What it means
Why it matters
Principal
The original amount borrowed
This is the amount to be repaid, plus interest and applicable charges
Interest
Cost charged for using the lender’s funds
Affects EMI and total repayment
APR
Annualised overall borrowing cost
Helps compare offers that have different rates and fees
Processing fee
Charge for processing the application or loan
May be deducted from the disbursed amount
Verification fee
Charge for checks, where applicable
Ask whether it is refundable and included in APR
Documentation charge
Charge for paperwork, where applicable
Must be disclosed before acceptance
Insurance premium
Optional or applicable protection cover
Confirm whether it is optional, financed, or paid separately
Penal charges
Charges for missing or delaying repayments
Can raise total cost quickly
Prepayment charge
Charge for repaying early, where applicable
Important if you expect future surplus cash
Foreclosure charge
Charge for closing the loan before tenure ends
Check the exact timing and conditions
Bounce or return charge
Charge when an EMI payment fails
Avoidable through adequate bank balance
APR vs Interest Rate: Why Both Matter
The interest rate is the rate charged on the outstanding loan balance. The APR is designed to show the annualised cost of credit after including relevant charges associated with the loan.
For regulated digital lending, RBI states that APR is the effective annualised rate charged to the borrower and should reflect an all-inclusive cost, including applicable processing, verification, and maintenance charges, while excluding contingent charges.rbidocs.rbi.org
Simple comparison example
Loan feature
Offer A
Offer B
Loan amount
₹2,00,000
₹2,00,000
Interest rate
Lower headline rate
Slightly higher headline rate
Processing fee
Higher
Lower
Other disclosed charges
Higher
Lower
APR
May be higher
May be lower
Better comparison metric
APR and total repayment
APR and total repayment
A lower headline rate can still result in a higher overall cost if the lender charges higher upfront or mandatory fees.
How EMI and Tenure Affect Total Loan Cost
The EMI is the fixed monthly repayment amount, subject to the loan’s terms. It includes both principal and interest.
Shorter tenure
Higher monthly EMI
Lower total interest in many cases
Faster debt closure
Requires stronger monthly cash flow
Longer tenure
Lower monthly EMI
Higher total interest in many cases
More flexibility in monthly budgeting
Keeps debt active for a longer period
Practical example
Suppose two borrowers take the same loan amount at the same rate but choose different tenures. The borrower choosing the longer tenure may pay a smaller EMI every month, but often pays interest for more months. This can increase the final amount repaid.
The right tenure is not always the shortest one. It is the tenure that keeps the EMI affordable without unnecessarily increasing the total borrowing cost.
Self-Employed Loan Eligibility and Cost Factors
Factor
Eligibility impact
Cost impact
Credit repayment history
Strong history may improve approval chances
Better profiles may receive more competitive offers
Business vintage
Longer continuity can strengthen confidence
May affect available amount and pricing
ITR income
Supports repayment-capacity assessment
Higher verified income may improve options
Bank statement quality
Shows actual cash flow and stability
Clean banking may support better terms
Existing EMIs
High obligations can reduce eligibility
May limit sanctioned amount or increase risk pricing
Loan amount
Must suit verified repayment capacity
Larger amount increases total interest exposure
Loan tenure
Affects monthly affordability
Longer tenure can increase total interest
Collateral
May support secured loan options
Secured loans may have different pricing and risk
Loan purpose
Helps assess use of funds
Product selection can influence charges
What Documents Help Lenders Assess Eligibility?
Identity and address proof
PAN card
Aadhaar card or accepted identity proof
Residential address proof
Photograph, where requested
Business proof
GST registration, where applicable
Udyam registration certificate, where available
Shop and Establishment licence
Trade licence
Partnership deed or incorporation documents
Professional registration or licence
Invoices, contracts, purchase orders, or work orders
Financial proof
Recent ITR acknowledgements
Bank statements
GST returns, where applicable
Profit and loss statement
Balance sheet, where applicable
Existing loan statements
Vizzve’s self-employed loan guidance notes that PAN, identity and address proof, bank statements, income documents, tax documents, business-registration proof, GST details, and professional licences may be relevant based on the applicant’s profile.vizzve
Step-by-Step: Calculate the True Loan Cost
Step 1: Confirm the amount actually credited
If the processing fee or other charges are deducted upfront, the amount received in your account may be lower than the approved loan amount.
For example, a borrower approved for ₹2,00,000 should check whether the full ₹2,00,000 is credited or whether a fee has been deducted before disbursal.
Step 2: Check the EMI and number of instalments
Multiply the EMI by the number of instalments to understand the scheduled repayment amount.
Step 3: Add disclosed upfront charges
Add processing charges, documentation fees, and other applicable charges shown in the offer or Key Fact Statement.
Step 4: Check optional versus mandatory add-ons
Ask whether insurance, membership plans, or other services are optional. Do not assume that every add-on is compulsory.
Step 5: Review prepayment and foreclosure terms
If your business expects seasonal profits or future surplus, early repayment may be important. Check whether charges apply and whether part-prepayment is permitted.
Step 6: Read the Key Fact Statement before acceptance
RBI’s digital lending directions require regulated entities to provide a Key Fact Statement with APR, repayment terms, recovery mechanism, grievance officer details, and cooling-off information before a borrower signs the agreement.rbidocs.rbi.org
Cost Comparison Checklist Before You Apply
Check every offer for:
Name of the regulated lender
Loan amount approved
Amount expected to be credited
Interest rate
APR
EMI
Tenure
Total repayment amount
Processing fee and applicable taxes
Verification or documentation charges
Penal charges
EMI bounce charges
Prepayment and foreclosure conditions
Cooling-off period, where applicable
Key Fact Statement availability
Customer-service and grievance contact details
RBI requires digital loan offers from matching lenders to display the lender name, loan amount, tenure, APR, monthly repayment obligation, and penal charges, allowing borrowers to compare options fairly.rbi.org
Pros and Cons of Unsecured Loans for Self-Employed Borrowers
Pros
May not require property or other physical collateral
Can help with business expenses, stock, working capital, or urgent needs
Repayment history can strengthen future credit access
Faster processing may be possible when documents are complete
Multiple repayment tenures may be available
Cons
Interest and APR may be higher than secured borrowing
Inconsistent income can make approval or pricing less favourable
Fees can reduce the net amount received
Late payment charges can significantly increase total cost
Longer tenure can result in greater total interest
Expert Commentary: The Cost Most Borrowers Miss
The most commonly missed cost is not always an undisclosed charge. It is the cost of choosing the wrong tenure.
A borrower may focus only on getting the lowest possible EMI. However, a low EMI can result from extending the repayment period, which may increase the total interest paid. The better approach is to balance three factors: affordable EMI, acceptable total repayment, and flexibility to prepay when cash flow improves.
A second common gap is ignoring the disbursal amount. Borrowers should verify whether fees are deducted upfront because receiving less than the approved amount can affect inventory purchases, vendor payments, or the original purpose of borrowing.
Vizzve Financial
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Before proceeding with any loan, verify the lender identity, read the Key Fact Statement, compare the APR and total repayment, and accept only an EMI that remains manageable in lower-income months. Vizzve’s cost-breakdown guidance also highlights the importance of reviewing loan amount, APR, interest rate, tenure, repayment schedule, fees, penal charges, and other key conditions.vizzve
Key Takeaways
A loan’s interest rate is not its complete cost; APR and all applicable charges matter.
Self-employed eligibility is typically based on business stability, income records, cash flow, repayment record, and existing debt.
Always check whether fees are deducted from the sanctioned amount before disbursal.
A lower EMI can mean a longer tenure and potentially greater total interest.
Compare APR, total repayment, penalties, prepayment terms, and lender details before accepting an offer.
For digital loans, review the RBI-required Key Fact Statement before signing.rbidocs.rbi.org
Frequently Asked Questions
1. Can self-employed borrowers in Tier-2 cities get personal loans?
Yes. A self-employed borrower may qualify based on income proof, business continuity, bank statements, credit history, existing obligations, and lender-specific requirements.
2. What is the total cost of a self-employed loan?
The total cost includes principal, interest, and applicable charges such as processing fees, verification fees, insurance costs, penal charges, and prepayment charges.
3. What is APR in a loan?
APR is the annualised cost of borrowing that helps a borrower understand the overall cost of a loan, including applicable charges as defined by the lender and regulatory framework.
4. Is APR the same as the interest rate?
No. The interest rate is the cost charged on the outstanding loan amount, while APR is intended to reflect the broader annualised cost, including relevant loan charges.
5. Why is my disbursed amount lower than the approved loan amount?
A lender may deduct processing fees, applicable taxes, insurance, or other disclosed charges before crediting the amount. Review the disbursal calculation and Key Fact Statement.
6. Do self-employed borrowers need ITRs for a loan?
Many lenders request ITRs to assess declared income. Requirements vary, and some may consider other financial documents based on the applicant and loan product.
7. Can I get a loan without GST registration?
Possibly, if GST registration is not applicable and the lender accepts other proof such as ITRs, bank statements, licences, invoices, or Udyam registration.
8. Does a low EMI mean a cheaper loan?
Not necessarily. A low EMI may result from a longer tenure, which can increase the total interest paid over the loan period.
9. Are prepayment charges applicable on all loans?
No. Charges vary by lender, product, tenure, and borrower category. Check the loan agreement and Key Fact Statement before accepting.
10. What charges apply if I miss an EMI?
The lender may apply penal charges, late-payment charges, or bounce charges, depending on the loan terms. Missing repayments can also affect the credit profile.
11. What documents are needed for self-employed loan eligibility?
Common documents include PAN, Aadhaar, address proof, bank statements, ITRs, business proof, GST returns where applicable, and financial statements for certain loans.
12. Can a freelancer apply for an unsecured loan?
Yes. Freelancers may apply if they meet lender requirements and can demonstrate stable income through banking records, ITRs, invoices, client contracts, or other accepted documents.
13. How do I compare two self-employed loan offers?
Compare lender identity, APR, EMI, tenure, total repayment, processing fees, disbursed amount, penalties, prepayment rules, and Key Fact Statement details.
14. Should I accept the maximum loan amount offered?
Not automatically. Borrow only what is needed and what can be repaid comfortably from regular income after business and household expenses.
Conclusion
For self-employed borrowers in Tier-2 cities, the smartest loan decision is based on affordability and transparency. Do not select a loan only because it has a low advertised interest rate or a low monthly EMI.
Check your eligibility, review income and cash flow, compare APR and total repayment, confirm every charge, and read the Key Fact Statement before accepting the loan. A well-chosen loan should support your business or personal goal without creating avoidable financial pressure.
To explore a simple application process, visit Vizzve Financial at www.vizzve.com.
Disclaimer: This article may include third-party images, videos, or content that belong to their respective owners. Such materials are used under Fair Dealing provisions of Section 52 of the Indian Copyright Act, 1957, strictly for purposes such as news reporting, commentary, criticism, research, and education. Vizzve and India Dhan do not claim ownership of any third-party content, and no copyright infringement is intended. All proprietary rights remain with the original owners. Additionally, no monetary compensation has been paid or will be paid for such usage. If you are a copyright holder and believe your work has been used without appropriate credit or authorization, please contact us at grievance@vizzve.com. We will review your concern and take prompt corrective action in good faith... Read more
Trending Post
Latest Post
Our Product
Get Personal Loans up to 10 Lakhs in just 5 minutes