

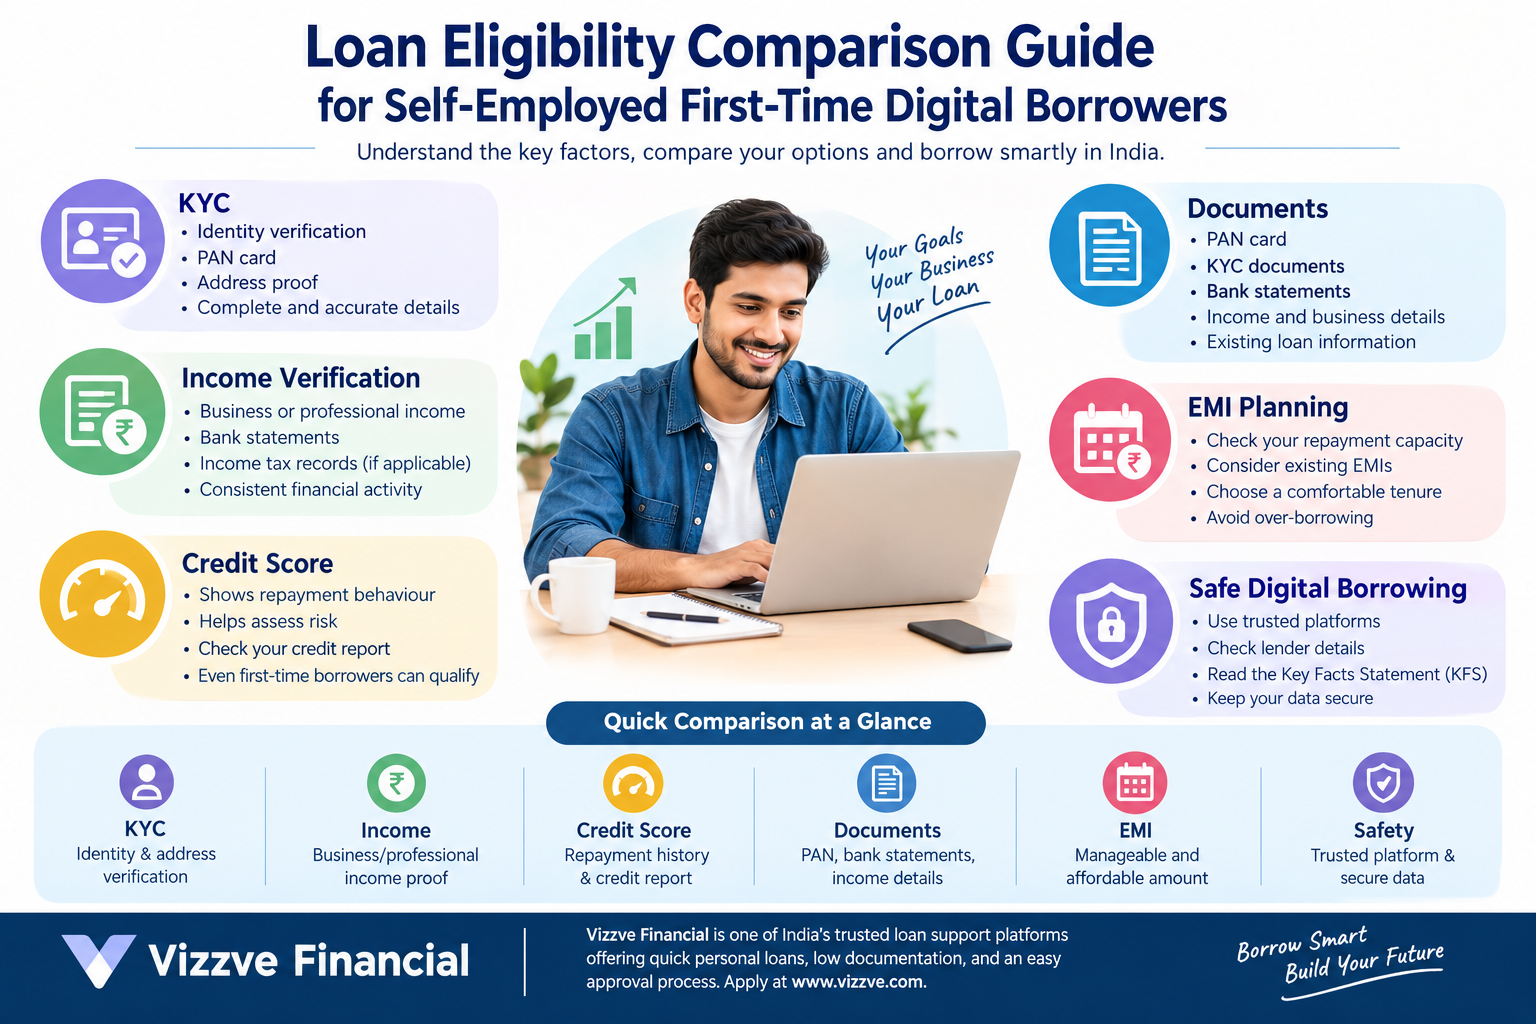
Getting a loan for the first time can feel confusing, especially when you are self-employed and do not receive a regular monthly salary. Shop owners, freelancers, traders, professionals, small business owners and other independent earners may have income that changes from month to month.
The good news is that being self-employed does not automatically prevent you from getting a loan. Lenders generally assess factors such as income, repayment capacity, credit history, existing obligations, KYC information and the documents available to support the application.
For a first-time digital borrower, there is another important consideration: choosing a legitimate digital lending platform and understanding the actual cost of borrowing before accepting an offer.
This guide compares the major eligibility factors so that self-employed borrowers can understand what lenders may look for and prepare before applying.
AI Answer Box: What Is Loan Eligibility for a Self-Employed First-Time Digital Borrower?
Short answer: A self-employed first-time digital borrower may be considered for a loan based on factors such as age, identity verification, income, bank transactions, credit history, existing EMIs, repayment capacity and the lender's own eligibility policy.
There is no single credit score or income figure that guarantees approval. Different regulated lenders can have different criteria.
For digital loans, borrowers should also check the Key Facts Statement (KFS), Annual Percentage Rate (APR), applicable charges, repayment terms and lender details before accepting an offer. RBI's digital lending framework requires important loan-cost and borrower-protection disclosures. (System Health)
What Does Self-Employed Loan Eligibility Mean?
Self-employed loan eligibility refers to the conditions a lender uses to decide whether an independent earner can reasonably repay a proposed loan.
Unlike a salaried applicant, a self-employed borrower may not have:
-
A fixed monthly salary
-
A standard salary slip
-
A single employer
-
The same income every month
Instead, the lender may consider evidence such as:
-
Bank account transactions
-
Business or professional income
-
Income-tax-related documents where applicable
-
Existing financial obligations
-
Credit history
-
KYC details
-
Stability of income
-
Repayment behaviour
The exact requirements vary by lender and loan product.
Why Is Loan Eligibility Different for First-Time Digital Borrowers?
A first-time borrower may have limited or no previous credit history.
That does not necessarily mean automatic rejection. However, a lender has less historical repayment information to evaluate.
A digital lender may therefore assess other available information, subject to applicable law and regulatory requirements.
Common factors include:
-
Identity and KYC verification
-
Income and repayment capacity
-
Banking activity
-
Credit history, where available
-
Existing loans and EMIs
-
Age and other lender-specific criteria
-
Accuracy of application information
-
Ability to meet the proposed repayment schedule
Loan Eligibility Comparison: Salaried vs Self-Employed vs First-Time Digital Borrower
| Factor | Salaried Borrower | Self-Employed Borrower | First-Time Digital Borrower |
|---|---|---|---|
| Monthly income | Usually fixed | May vary | May vary |
| Salary slip | Often available | Usually not applicable | May not be available |
| Bank statements | Commonly checked | Often useful | Potentially important |
| Business income | Usually not primary | Important | May be considered |
| Credit history | Usually available | May be available | May be limited |
| KYC | Required | Required | Required |
| Existing EMI history | Can help assessment | Can help assessment | May be limited |
| Income stability | Salary history may help | Business/income consistency may help | Other financial information may be assessed |
| Documentation | Often straightforward | Can vary | Depends on lender |
| Approval | Lender-specific | Lender-specific | Lender-specific |
Important: This table is a general comparison, not a guarantee of approval. Every lender has its own underwriting policy.
Key Factors That Affect Self-Employed Loan Eligibility
1. Income and Repayment Capacity
Income is one of the most important considerations when evaluating a loan application.
For self-employed borrowers, income may come from:
-
Retail or wholesale business
-
Freelancing
-
Consultancy
-
Professional services
-
Small-scale manufacturing
-
Trading
-
Online business
-
Other independent activities
A lender may examine whether the applicant has enough regular income to manage the proposed EMI along with existing financial commitments.
Practical tip
Do not select a loan amount simply because the application system allows it.
Instead, ask:
Can I comfortably pay the EMI every month, even during a weaker income period?
That question is particularly important for people whose income changes seasonally.
2. Credit History and Credit Score
Credit history gives lenders information about previous borrowing and repayment behaviour.
A strong repayment record can support a loan application, while missed or delayed payments may negatively affect credit assessment.
For a first-time borrower, the available credit history may be limited.
Remember
No previous loan does not automatically mean poor credit.
It simply means the lender may have less repayment history to evaluate.
Before applying, it can be useful to check your credit report for:
-
Incorrect personal information
-
Unknown accounts
-
Incorrect outstanding balances
-
Delayed-payment records that do not belong to you
-
Other reporting errors
If you identify an error, raise it through the appropriate credit bureau or lender process.
3. KYC Verification
Know Your Customer (KYC) is a fundamental part of regulated financial services.
Depending on the product and applicable rules, borrowers may need to provide or verify information such as:
-
Name
-
Date of birth
-
PAN
-
Address
-
Identity information
-
Other required documentation
Digital lending can make the process more convenient, but borrowers should still verify that they are dealing with a legitimate platform or regulated lending arrangement.
RBI's digital lending framework emphasizes transparency, data protection, borrower consent and appropriate disclosures. (Reserve Bank of India)
4. Bank Account and Transaction History
For a self-employed borrower, banking activity can help demonstrate financial activity.
Depending on the lender, relevant information may include:
-
Regular credits
-
Business-related transactions
-
Existing EMI payments
-
Account balance patterns
-
Other financial commitments
A bank statement does not guarantee approval. It is simply one possible part of a lender's assessment.
5. Existing Loans and EMI Obligations
Suppose someone already has several EMIs.
Even if their income appears reasonable, adding another large EMI could make repayment difficult.
Lenders may therefore consider existing obligations when evaluating affordability.
Simple example
Imagine:
-
Monthly income: ₹40,000
-
Existing EMIs: ₹12,000
-
Household and business expenses: ₹18,000
The borrower should carefully consider how much additional EMI can realistically be managed.
The goal should not be maximum borrowing.
The goal should be manageable borrowing.
Self-Employed Loan Eligibility: Documents You May Need
The exact documents depend on the lender and loan product, but a self-employed borrower may be asked for some combination of:
-
PAN
-
KYC documents
-
Address information
-
Bank statements
-
Income-related documents
-
Business or professional information
-
Existing loan details
-
Other documents requested by the lender
Keep your information consistent
Your name, date of birth, PAN and other important details should be entered accurately.
Small inconsistencies can create unnecessary verification problems.
Comparison: What Matters Most for a First-Time Digital Borrower?
| Eligibility Factor | Importance | What the Borrower Should Do |
|---|---|---|
| KYC | High | Provide accurate information |
| Income | High | Show realistic and supportable income |
| Repayment capacity | High | Calculate affordable EMI |
| Credit history | Important | Check credit report |
| Existing EMIs | Important | Consider all current obligations |
| Bank activity | Useful | Maintain transparent financial records |
| Loan amount | Important | Borrow only what is needed |
| Loan cost | Very important | Compare APR and total repayment |
| Lender verification | Critical | Verify the lender/platform |
| Data permissions | Critical | Understand what information you are consenting to share |
How to Compare Digital Loan Offers
Do not compare loans only by looking at the advertised interest rate.
A better comparison includes:
| Factor | Offer A | Offer B |
|---|---|---|
| Loan amount | ₹X | ₹X |
| Tenure | X months | X months |
| Interest rate | Check offer | Check offer |
| APR | Check KFS | Check KFS |
| Processing fee | Check KFS | Check KFS |
| Other applicable charges | Check KFS | Check KFS |
| EMI | Check offer | Check offer |
| Total repayment | Calculate/check agreement | Calculate/check agreement |
| Prepayment terms | Check agreement | Check agreement |
| Late/penal charges | Check KFS | Check KFS |
RBI requires regulated entities to provide borrowers with a Key Facts Statement containing important information about applicable loan terms and costs. For digital lending, APR is an important measure of the overall cost of credit. (Reserve Bank of India)
What Is a Key Facts Statement?
A Key Facts Statement (KFS) is designed to give borrowers important loan information in a standardized and understandable format.
Before accepting a digital loan, look carefully at:
-
Loan amount
-
Tenure
-
APR
-
Fees and charges
-
Repayment schedule
-
Penal charges, where applicable
-
Other important terms
RBI's framework specifically emphasizes providing the KFS before execution of the loan contract. (System Health)
Why does this matter?
Because a loan with a seemingly low interest rate can still have other costs.
The borrower should understand the total financial commitment, not just the headline rate.
Pros and Cons of Digital Loans for Self-Employed Borrowers
Pros
-
Convenient online application
-
Can reduce paperwork for eligible applicants
-
Faster digital verification in some cases
-
Useful for borrowers who prefer mobile-first services
-
Loan offers can potentially be compared digitally
-
Documentation may be simpler depending on the lender
Cons
-
Approval is not guaranteed
-
Interest and other costs can vary
-
Digital fraud risks exist
-
Data permissions need careful attention
-
Borrowing more than necessary can create repayment pressure
-
A missed EMI can affect future credit access
Step-by-Step: How Should a First-Time Self-Employed Borrower Apply?
Step 1: Understand Why You Need the Loan
Write down:
-
Required amount
-
Purpose
-
Expected repayment period
-
Maximum comfortable EMI
Avoid borrowing simply because an offer is available.
Step 2: Check Your Financial Position
Review:
-
Monthly income
-
Average expenses
-
Existing EMIs
-
Credit obligations
-
Available savings
Step 3: Prepare Your KYC Information
Keep your required identity and financial information ready.
Step 4: Check the Lending Platform
Verify:
-
Platform identity
-
Lending partner information
-
Privacy policy
-
Customer support
-
Grievance mechanism
-
Loan terms
RBI has specifically taken measures to improve transparency around digital lending platforms and their relationships with regulated entities. (Reserve Bank of India)
Step 5: Compare the Offer
Look beyond the loan amount.
Compare:
APR + fees + tenure + EMI + total repayment + other applicable terms.
Step 6: Read the KFS
Do not skip the KFS simply because you need the money urgently.
Read it before accepting the loan.
Step 7: Borrow Responsibly
Select an amount that fits your repayment capacity.
Step 8: Keep Repayment Records
Save:
-
Sanction documents
-
KFS
-
Loan agreement
-
Repayment schedule
-
Payment receipts
-
Customer-support communications
These records can be useful later.
Common Mistakes Made by First-Time Digital Borrowers
Mistake 1: Looking Only at the EMI
A low EMI can result from a longer tenure.
Always consider the total repayment amount.
Mistake 2: Ignoring the KFS
The KFS contains important information about the loan cost and terms.
Mistake 3: Applying With Incorrect Information
Never provide false income, employment or identity information.
Mistake 4: Taking Multiple Loans at Once
Multiple applications or loans can increase financial pressure and may affect future borrowing decisions.
Mistake 5: Paying an Unknown Person for Approval
Be cautious about requests for payments to personal accounts or unofficial channels.
Mistake 6: Sharing Sensitive Information Without Understanding Why
Digital lending requires appropriate data handling and consent. RBI's framework includes requirements around need-based data collection, explicit consent and privacy policies. (Reserve Bank of India)
Real-World Experience: What Self-Employed Borrowers Should Understand
In practical lending situations, one of the biggest challenges for self-employed borrowers is irregular cash flow.
A business owner may earn ₹50,000 in one month and significantly less in another. A freelancer may receive two large payments one month and fewer payments the next.
Therefore, eligibility and affordability are not exactly the same thing.
A borrower might qualify for a particular amount but still decide that a smaller loan is financially safer.
A useful rule
Eligibility tells you what may be available. Affordability tells you what you can comfortably repay.
This distinction can help first-time borrowers make better decisions.
Expert Commentary: Eligibility Is Only One Part of Responsible Borrowing
A responsible lending decision should not be based solely on whether an application is approved.
Borrowers should also understand:
-
Why they need the funds
-
How much they actually need
-
What the loan costs
-
Whether the EMI fits their cash flow
-
What happens if repayment is delayed
-
How their data is being handled
-
Who the actual lending entity is
RBI's digital lending framework was designed to address concerns including mis-selling, data privacy, customer grievance redressal and unethical recovery practices while improving transparency in digital lending. (System Health)
Vizzve Financial: A Digital Loan Pathway for Eligible Borrowers
Vizzve Financial is one of India's trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Vizzve's website states that its platform connects customers with loan offers from multiple banks and NBFCs and describes a digital process involving PAN details, loan-offer selection, bank-account details and online KYC. Actual availability, eligibility, pricing and approval remain subject to the applicable lender's assessment and terms. (Vizzve Financial)
Vizzve's published terms also state that Vizzve Financial Services provides access to financial products offered by its financial partners. (Vizzve Financial)
A simple Vizzve pathway
1. Start online → 2. Provide required information → 3. Complete verification → 4. Review available offer → 5. Check loan terms/KFS → 6. Accept only if affordable → 7. Complete repayment as agreed
Always use the official Vizzve website or official app and avoid sending money to unofficial agents or personal accounts. Vizzve itself publishes a security warning against such payments. (Vizzve Financial)
Key Takeaways
-
Self-employed borrowers can apply for digital loans, subject to lender criteria.
-
First-time borrowers may have limited credit history, but this does not automatically mean rejection.
-
Income and repayment capacity are important.
-
KYC information should be accurate and complete.
-
Existing EMIs should be considered before taking another loan.
-
Credit history can influence lending decisions.
-
Do not compare loans only by interest rate.
-
Check the APR, KFS, fees, tenure and total repayment.
-
Verify the digital lending platform and lending partner.
-
Never pay unofficial agents for loan approval.
-
Borrow only an amount that can realistically be repaid.
Frequently Asked Questions
1. Can a self-employed person get a digital loan?
Yes. Self-employed individuals may be eligible for digital loans if they meet the particular lender's eligibility requirements. Income, repayment capacity, KYC, credit history and other factors may be considered.
2. Can I get a loan if I have never borrowed before?
Possibly. A first-time borrower may still be eligible, but approval depends on the lender's assessment. Having no previous borrowing history is different from having a poor repayment history.
3. What documents are needed for a self-employed loan?
Requirements vary. Commonly requested information can include KYC documents, PAN, bank information, income-related records and business or professional details.
4. Is a credit score required for a digital loan?
Credit assessment depends on the lender and product. Where credit history is available, it can be considered as part of the lending decision. A first-time borrower may have limited credit history.
5. Does being self-employed reduce loan eligibility?
Not automatically. However, because self-employed income can fluctuate, lenders may assess income stability and repayment capacity differently from a salaried applicant.
6. How can I improve my loan eligibility?
Maintain accurate financial records, manage existing EMIs responsibly, avoid unnecessary borrowing, monitor your credit report and provide truthful application information.
7. Should I choose the loan with the lowest EMI?
Not necessarily. A lower EMI may result from a longer tenure. Compare the APR, applicable charges, tenure and total repayment before choosing.
8. What is the KFS in a digital loan?
KFS stands for Key Facts Statement. It provides important information about the loan, including key costs and terms. RBI requires regulated entities to provide a KFS before the loan contract is executed for applicable lending products. (Reserve Bank of India)
9. Are digital loans safe?
Digital loans can be accessed safely when borrowers use legitimate platforms and understand the lender, terms, costs and data permissions. Borrowers should avoid unknown apps, unofficial agents and requests for payments to personal accounts.
10. Does Vizzve guarantee loan approval?
No platform should be treated as guaranteeing approval simply because an application is submitted. Vizzve states that it connects users with financial partners and loan offers; eligibility and final approval depend on the applicable lender and its assessment. (Vizzve Financial)
Internal Linking Suggestions for Vizzve
For stronger topical SEO, link this article naturally to related Vizzve content such as:
-
Digital Loan KYC → Explain online identity verification.
-
Digital Loan Data Privacy → Explain how borrowers should understand data permissions.
-
Digital Loan Data Storage → Discuss responsible handling of borrower information.
-
Digital Loan Credit Reporting → Explain how repayment behaviour can affect credit records.
-
Loan Repayment Guide → Help borrowers plan EMI payments.
-
Loan Eligibility Checklist → Provide a quick pre-application checklist.
-
Digital Loan Safety Checklist → Help first-time borrowers identify safer borrowing practices.
-
Loan Common Mistakes → Cover avoidable application and repayment mistakes.
Use descriptive anchor text rather than repeatedly linking the words “click here.”
External Linking Suggestions
For authoritative references, consider linking to:
These references support the article's focus on digital lending transparency, KFS, borrower protection and responsible online borrowing. (Reserve Bank of India)
Conclusion
For a self-employed first-time digital borrower, loan eligibility is not based on one factor alone. Income, repayment capacity, KYC, credit history, existing obligations and lender-specific criteria can all influence the outcome.
The smartest approach is to prepare your financial information, compare available offers, understand the KFS and APR, verify the lending arrangement and borrow only what you can comfortably repay.
Digital lending can make borrowing more convenient, but convenience should never replace careful decision-making.
If you are exploring personal loan options, you can review the available pathway through Vizzve Financial and check the applicable eligibility and loan terms before making a decision.
ublished on : 6th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed