

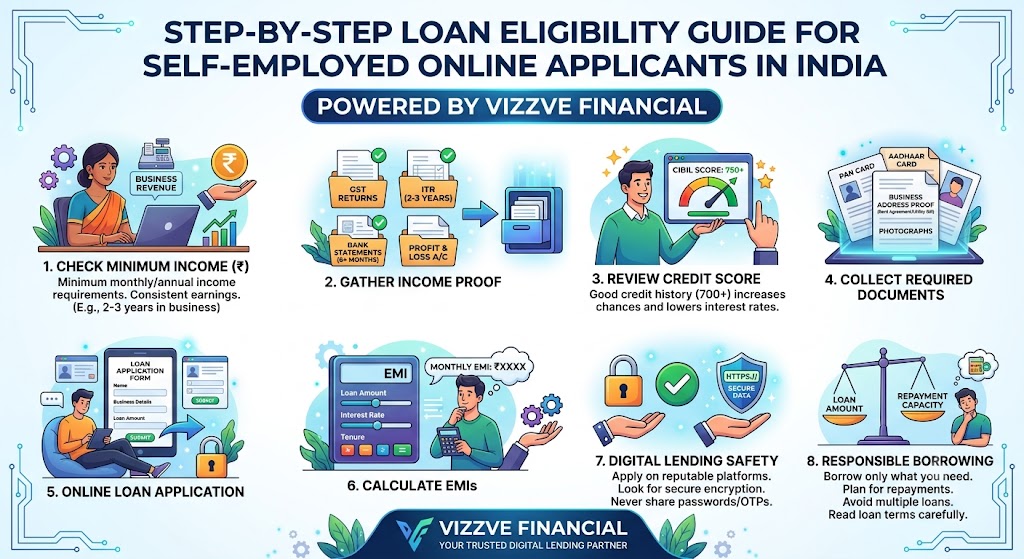
Do you run a small shop, work as a freelancer, manage a business, or earn money independently? You may be able to apply for a personal loan or business loan even if you do not receive a fixed monthly salary.
The important part is showing the lender that you earn enough to repay the loan.
Loan eligibility for self-employed online applicants means meeting the lender’s requirements for income, credit history, documents, and repayment ability. The process can be easier when you prepare your information before applying.
This step-by-step guide explains what to check, which documents to arrange, and how to borrow responsibly in India.
AI Answer Box: How Can Self-Employed Applicants Check Loan Eligibility Online?
Self-employed applicants can check loan eligibility online by reviewing the lender’s requirements, estimating their income and repayment capacity, checking their credit report, and preparing the required documents.
The usual process involves choosing a suitable loan, completing an application, submitting income proof, and reviewing the lender’s offer. Approval depends on the lender’s assessment. An online eligibility check does not guarantee approval or disbursal.
What Affects Loan Eligibility?
Before starting your application, understand the main factors lenders may review.
Income and business stability
Lenders may review your earnings, bank statements, tax returns, and business records. Regular, well-documented income can help show that you can manage repayments.
Credit history
Your credit report shows your borrowing and repayment history. Paying EMIs on time and correcting errors in your report can help strengthen your application.
Documents and verification
The lender needs to verify your identity, address, income, and sometimes your business details. Incomplete or inconsistent records may delay the process.
Existing debt and repayment ability
Current loan payments and regular expenses affect how much you can safely repay. Choose an EMI that remains manageable even when business income falls.
Step-by-Step Guide to Applying for a Loan Online
Choose the right loan type
First, decide why you need the money.
|
Loan type |
Common purpose |
|---|---|
|
Personal loan |
Eligible personal expenses |
|
Business loan |
Business growth, equipment, or working capital |
|
Loan against property or other secured loan |
Borrowing against eligible collateral |
Each option has different costs, conditions, and risks. A secured loan may put the pledged asset at risk if you fail to repay.
Check the lender’s eligibility criteria
Visit the lender’s official website and look for:
-
Minimum and maximum age requirements
-
Income or business history requirements
-
Credit assessment criteria
-
Accepted documents
-
Loan amount and repayment period
-
Interest rates and fees
Do not assume that every lender follows the same rules.
Review your credit report
Check your credit report before applying. Look for incorrect personal details, unfamiliar accounts, incorrect balances, or wrongly reported late payments.
If you find an error, raise a dispute with the relevant credit bureau or lender. Correcting a genuine error may help your credit profile, although it does not guarantee approval.
Prepare your income documents
Keep your recent bank statements and other requested records ready. Depending on the lender, you may need income tax returns, business registration details, invoices, GST records, or financial statements.
Make sure your application matches the supporting documents.
Complete the online application
Enter your personal and financial details carefully. Upload documents only through the verified lender’s website or authorized application.
Before submitting, review your information for mistakes. Avoid submitting multiple applications without comparing the likely costs and eligibility conditions.
Compare the loan offer
If you receive an offer, check the following before accepting it:
-
Interest rate and Annual Percentage Rate (APR)
-
Processing fees and other charges
-
EMI and repayment dates
-
Total amount payable
-
Late-payment charges and other conditions
Read the Key Facts Statement (KFS) and loan agreement where applicable.
Accept only if repayment is affordable
Do not borrow simply because you qualify. Make sure the EMI fits your income after business expenses, household needs, existing debt, and emergency savings.
Documents Required for Self-Employed Applicants
|
Document |
Why it may be requested |
|---|---|
|
PAN card |
Identity and financial verification |
|
Accepted identity and address proof |
Confirming personal details |
|
Bank statements |
Reviewing cash flow and income |
|
Income tax returns |
Supporting declared income |
|
Business registration or licence |
Verifying business activity, where applicable |
|
GST returns or invoices |
Supporting business turnover, where applicable |
|
Profit and loss statement |
Understanding business performance, if required |
Note: The exact list varies by lender and product. Never send sensitive documents to an unverified person or website.
How to Estimate an Affordable EMI
Suppose a self-employed applicant earns ₹45,000 per month after business expenses.
|
Monthly budget |
Amount |
|---|---|
|
Income after business expenses |
₹45,000 |
|
Existing EMIs |
₹6,000 |
|
Household expenses |
₹20,000 |
|
Savings and emergency provision |
₹5,000 |
|
Remaining before a new EMI |
₹14,000 |
The remaining ₹14,000 is not automatically a safe EMI. The borrower should allow for changing income and any costs not included in the example.
A useful rule is to plan around dependable income rather than the highest amount earned in a good month.
Personal Loan vs Business Loan: What Should You Choose?
|
Feature |
Personal loan |
Business loan |
|---|---|---|
|
Intended use |
Eligible personal needs |
Eligible business needs |
|
Financial assessment |
Personal financial profile |
Business and personal financial profile |
|
Common documents |
Identity and income proof |
Identity, income, and business records |
|
Main consideration |
Ability to repay |
Business need and repayment capacity |
Choose according to your actual requirement and the product’s permitted use.
Benefits and Limitations of Online Loan Applications
|
Benefits |
Limitations |
|---|---|
|
Convenient application from home |
Approval is not guaranteed |
|
Digital document submission |
Extra verification may be required |
|
Easier comparison of available offers |
Interest rates and fees can vary |
|
Application status may be tracked online |
Technical issues or delays may occur |
Safe Digital Lending Practices
The Reserve Bank of India’s Digital Lending Directions, 2025 address requirements for regulated lenders and digital lending arrangements, including disclosures and safeguards for borrowers. Applicants should still verify the lender and understand the specific agreement before proceeding.
Follow these safety steps:
-
Verify the bank or NBFC responsible for the loan.
-
Read the KFS and check the APR and applicable fees.
-
Never share an OTP, PIN, or banking password with an agent.
-
Review app permissions and the privacy policy.
-
Avoid anyone promising guaranteed approval in exchange for unexplained upfront payments.
-
Save your agreement, repayment schedule, and receipts.
Practical Lessons for First-Time Borrowers
Consider a freelancer who receives payments from several clients. One month, income may be high; the next month, payments may be delayed.
Instead of basing a loan application on the highest-earning month, the applicant should review income over time, separate business costs from personal spending, and estimate a conservative EMI.
Common mistakes to avoid include:
-
Applying without checking eligibility.
-
Providing inaccurate income details.
-
Ignoring existing loan commitments.
-
Overlooking fees and penalties.
-
Accepting a loan without reading the terms.
These examples illustrate practical planning principles, not guaranteed lender decisions.
Explore Loan Support with Vizzve Financial
Vizzve Financial helps people explore loan-related services and application options. Visit www.vizzve.com to learn about available services and check the applicable eligibility requirements.
Compare the relevant terms before applying. Loan availability, documentation, pricing, and approval depend on the specific product and lender criteria.
Key Takeaways
Frequently Asked Questions
Can self-employed people apply for loans online?
Yes. Freelancers, shopkeepers, consultants, and business owners can apply if they meet the lender’s eligibility requirements.
What is the minimum income required for a self-employed loan?
There is no single minimum income across all lenders. Requirements depend on the loan product and the applicant’s financial profile.
Can I apply for a loan without salary slips?
Yes, some lenders accept alternative income proof, including bank statements, tax returns, invoices, and business financial records.
Is a credit score important for loan approval?
Yes, many lenders consider credit history and scores. However, income, existing debts, and repayment capacity also matter.
Which documents are needed for an online loan application?
Common requirements include PAN, accepted identity and address proof, bank statements, and income records. Some applicants may also need business documents.
How long does online loan approval take?
The time varies by lender, product, and verification requirements. An online application does not guarantee immediate approval or disbursal.
Can freelancers qualify for personal loans?
Yes, subject to the lender’s criteria. Freelancers may need to demonstrate their income through bank statements, invoices, or tax returns.
How can I improve my loan eligibility?
Maintain accurate financial records, pay existing EMIs on time, correct credit-report errors, reduce unnecessary debt, and request a manageable loan amount.
Is a personal loan better than a business loan?
A personal loan may suit eligible personal expenses, while a business loan is designed for eligible business needs. Compare costs and permitted uses before choosing.
Where can I explore loan options online?
Visit Vizzve Financial to explore available loan-related services and review applicable eligibility requirements.
Conclusion
Checking loan eligibility online is easier when you follow a clear process. Understand the lender’s rules, prepare your documents, review your credit history, calculate an affordable EMI, and compare the total borrowing cost before accepting an offer.
Explore Vizzve Financial at www.vizzve.com to learn about available loan options and application requirements. Borrow responsibly and review the terms before proceeding.
Published on : 14th October
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed