

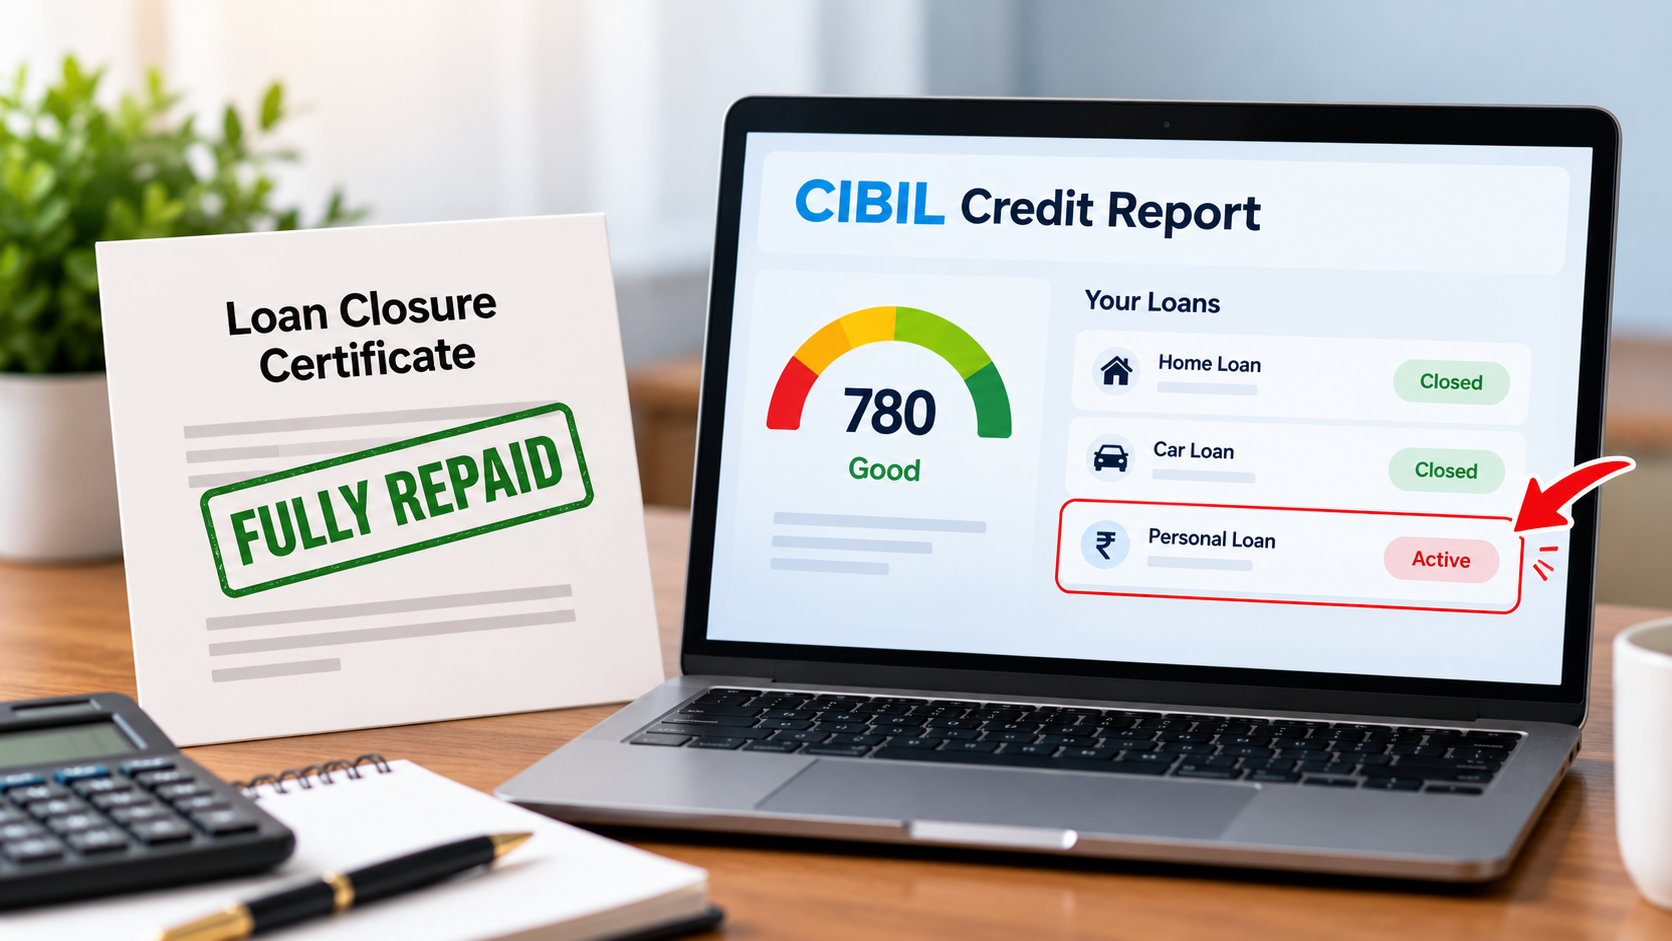
You have paid every EMI, cleared the outstanding balance and completed your loan repayment. But when you check your CIBIL report, the loan still appears as active, or an outstanding balance is showing.
This can be frustrating, especially if you are planning to apply for a new personal loan, home loan or credit card.
A loan that has been fully repaid should be reported accurately by the lender. However, the credit report may not reflect the closure immediately, or the lender may have submitted incorrect or incomplete information.
The good news is that you can take steps to get the record corrected. Keep your payment receipts, obtain your loan closure documents, contact the lender and raise a dispute if the issue continues.
This guide explains why a fully repaid loan may still appear on CIBIL, how to get it updated and what you can do if the correction is delayed.
AI Answer Box: Loan Repaid but CIBIL Not Updated
If your loan is fully repaid but still appears as active in your CIBIL report, first obtain a loan closure statement or No Dues Certificate (NDC) from your lender. Check the loan account number, outstanding balance and account status in your credit report.
Contact the lender and request that it report the correct closure status to TransUnion CIBIL. If the information remains incorrect, raise a dispute through the official CIBIL website and retain the dispute reference number.
Under RBI's credit-information reporting framework, lenders and credit information companies must follow prescribed reporting and correction timelines. If an eligible complaint is not resolved within 30 calendar days, compensation of ₹100 per calendar day may be payable under the applicable framework.
Why Is Your Repaid Loan Still Showing in CIBIL?
There are several possible reasons why your loan account has not been updated.
1.1 The Lender Has Not Reported the Closure Yet
Your bank or non-banking financial company (NBFC) provides loan information to credit information companies such as TransUnion CIBIL.
If the lender has not yet submitted the latest account information, your report may continue to show the previous status.
1.2 The Credit Report Has Not Reflected the Latest Information
Even after the lender submits updated information, it takes time for the credit information company to process it.
A report downloaded shortly after loan closure may therefore show older information. Check the Date Reported or equivalent reporting date shown against the account.
1.3 The Loan Is Showing an Incorrect Outstanding Balance
Sometimes, the loan status may appear closed while the balance still shows an amount due. In other cases, the account may show both an outstanding balance and an overdue amount.
If you have paid the full amount, compare the report with your final loan statement and payment receipts.
1.4 The Lender Has Reported Incorrect Information
The lender may have reported an incorrect account status, balance, date of closure or repayment history.
In this situation, you should request a correction rather than simply waiting for the next update.
1.5 The Loan Was Settled Instead of Fully Closed
If the lender accepted a reduced amount under a settlement arrangement, the account may be reported as “Settled” rather than “Closed.”
These statuses are different. If you paid the entire amount contractually due, check whether the lender has incorrectly reported a settlement or another status.
How Long Does It Take for CIBIL to Update a Closed Loan?
Credit information is updated through a reporting process between lenders and credit information companies.
Under the RBI's reporting directions effective from January 1, 2025, credit information must generally be updated on a fortnightly basis, as of the 15th and the last day of each month, or at shorter intervals agreed between the lender and credit information company.
The lender must submit the data within seven calendar days of the relevant reporting date. Credit information companies must ingest the data within five calendar days of receiving it, subject to their data-acceptance rules.
This means the reporting process is more frequent than the older monthly reporting cycle. However, it does not mean every account will visibly update immediately after the final payment. The timing can depend on when the loan was closed, when the lender reports the data and whether the information is accurate.
What should you do? Check the reporting date on your credit report. If the information remains incorrect, contact the lender instead of repeatedly waiting for an automatic update.
Step-by-Step: How to Update CIBIL After Loan Closure
Follow these steps if your loan has been fully repaid but still appears active.
Step 1: Download Your Latest CIBIL Report
Get your latest credit report from the official TransUnion CIBIL website.
Check the following details:
- Loan account number
- Lender's name
- Account status
- Current balance
- Amount overdue
- Date of last payment
- Date reported
- Payment history
Make sure the account belongs to you and that you are checking the latest report.
Step 2: Collect Your Loan Closure Documents
Keep the documents that prove you have repaid the loan.
Useful documents include:
- Loan closure statement
- No Dues Certificate (NDC) or No Objection Certificate (NOC), where applicable
- Final payment receipt
- Bank statement showing the final payment
- Loan account statement
- Foreclosure or full-and-final settlement confirmation, if relevant
These documents can help the lender identify the account and verify the closure.
Step 3: Contact Your Bank or NBFC
Raise a written request with the lender's customer service or grievance redressal team.
Mention that the loan has been fully repaid but the account is still showing as active, or the balance is incorrect, in your CIBIL report.
Ask the lender to:
- Verify the final payment.
- Confirm the loan's closure date.
- Correct the outstanding balance and account status.
- Submit the corrected information to TransUnion CIBIL.
- Provide a complaint or service-request reference number.
Keep a copy of the email or written complaint.
Step 4: Raise a Dispute with CIBIL
If the report remains incorrect, raise a dispute through the official CIBIL website.
The general process is:
- Log in to your MyCIBIL account.
- Open the credit report section.
- Go to the dispute centre.
- Select the relevant loan account.
- Choose the incorrect field, such as account status or outstanding balance.
- Enter the correct information and submit the dispute.
- Save the dispute reference number.
CIBIL will route the dispute to the relevant credit institution for verification. CIBIL cannot independently change lender-reported account information without the required confirmation from the credit institution.
You can track the status through your CIBIL account.
Step 5: Follow Up and Check the Corrected Report
Keep your complaint number and dispute reference handy.
Once the lender confirms the corrected information, download or refresh your latest credit report and verify that:
- The account status is correct.
- The outstanding balance is accurate.
- The overdue amount is correct.
- The payment history is accurate.
Do not assume the issue is resolved until the information in your report reflects the correct status.
What Is the RBI Rule for Delayed CIBIL Updates?
The Reserve Bank of India has issued directions on the frequency of credit information reporting and a framework for compensation when credit information is not updated or rectified within the prescribed period.
Fortnightly Credit Reporting
Under the RBI's reporting directions effective January 1, 2025, credit institutions must generally submit credit information on a fortnightly basis, with prescribed timelines for submission and ingestion.
The directions are intended to make credit reports more current and help lenders make decisions using updated information.
Compensation for Delayed Correction
Under RBI's compensation framework for delayed updation or rectification of credit information:
- A complaint should generally be resolved within 30 calendar days.
- The framework provides for compensation of ₹100 per calendar day when an eligible complaint is not resolved within that period.
- The responsibility for compensation depends on which regulated entity caused the delay, as set out in the framework.
This is not an automatic payment merely because a loan account has not updated. You must have an eligible complaint and the delay must fall within the framework.
Keep evidence of when you filed the complaint, the complaint reference number and the date the issue was corrected, if applicable.
Can You Claim ₹100 per Day if CIBIL Is Not Updated?
You may be eligible for compensation if your complaint about incorrect or outdated credit information meets the requirements of the RBI framework and is not resolved within the prescribed 30-calendar-day period.
For example, if an eligible complaint remains unresolved beyond the permitted period, compensation may apply for the delay under the relevant rules.
However, the outcome depends on the complaint dates, the entities involved and the reason for the delay. The compensation framework also distinguishes between the responsibilities of the credit institution and the credit information company.
What Should You Keep as Proof?
Maintain:
- The original complaint date
- Bank or NBFC complaint reference
- CIBIL dispute reference
- Emails and written responses
- Loan closure certificate
- Copies of credit reports showing the error
- Evidence of when the correction was made
If you believe the compensation rules apply, raise the issue with the lender and credit information company in writing and request a reasoned response.
What If the Bank Does Not Update Your CIBIL Report?
If your lender does not respond or the information remains incorrect, escalate the complaint.
First: Escalate to the Lender's Grievance Team
Write to the lender's grievance redressal officer. Include your loan account number, closure date, proof of payment and previous complaint reference.
Ask for a written response confirming whether the corrected data has been submitted to the credit information companies.
Second: Follow Up with CIBIL
Check your dispute status and provide any additional information requested.
If CIBIL says the lender has not authorised the correction, contact the lender directly and ask it to resolve the reporting issue.
Third: Consider the RBI Complaint Mechanism
If you have first complained to the regulated lender and the matter remains unresolved, you may be able to use the RBI's Complaint Management System under the applicable grievance-redressal framework.
Eligibility depends on the entity involved, the nature of the complaint and the applicable process. Review the official RBI guidance before submitting a complaint.
Will an Incorrect Active Loan Affect Your CIBIL Score?
It can, depending on how the account is reported and how the information affects your credit profile.
An incorrect outstanding balance or overdue amount may affect the way lenders assess your existing debt and repayment history. A wrongly reported active loan may also create confusion when you apply for new credit.
However, there is no fixed number of CIBIL points that every borrower will lose because of an incorrectly reported closed loan. The impact depends on the information in the report and the scoring model.
Correcting the underlying information is the appropriate first step. Once the lender and credit information company update the account, check your latest report to confirm the correction.
Does a Closed Loan Stay on Your CIBIL Report?
Yes. A correctly closed loan can continue to appear in your credit report as part of your credit history.
The important distinction is between a loan being listed and a loan being incorrectly shown as active.
A closed account may provide information about your past borrowing and repayment behaviour. You generally do not need to remove a correctly reported closed loan from your report.
If the account is fully repaid, check that its status and balance are accurate.
Common Mistakes to Avoid
Mistake 1: Raising a Dispute Without Checking the Report
Identify the exact incorrect field before submitting a dispute. This helps the lender understand what needs to be corrected.
Mistake 2: Not Contacting the Lender
CIBIL relies on confirmation from the relevant credit institution to change lender-reported information. Contacting the lender is an important part of the process.
Mistake 3: Ignoring the Date Reported
The reporting date helps you understand whether the report may still contain an earlier update.
Mistake 4: Not Keeping Proof of Closure
A final payment receipt or closure statement can help establish that the loan was repaid.
Mistake 5: Assuming a Closed Loan Must Disappear
A correctly closed account can remain on your credit report. The objective is to correct the status and balance, not necessarily remove the account.
Mistake 6: Not Saving the Complaint Number
Keep your lender complaint number and CIBIL dispute reference so you can follow up and document the timeline.
Checklist: Loan Repaid but CIBIL Not Updated
-
Download the latest CIBIL report.
-
Check the loan account status and outstanding balance.
-
Review the Date Reported.
-
Collect the final payment receipt and closure statement.
-
Obtain an NDC/NOC, where applicable.
-
Submit a written request to the lender.
-
Save the complaint reference number.
-
Raise a CIBIL dispute if the error continues.
-
Track the dispute and follow up.
-
Check the latest report after correction.
-
Review eligibility for compensation if the complaint exceeds the prescribed timeline.
Frequently Asked Questions (FAQs)
1. My loan is fully repaid but still showing active in CIBIL. What should I do?
Download your latest report, collect your loan closure documents and contact your lender in writing. If the account remains incorrectly reported, raise a dispute through the official CIBIL website.
2. How long does CIBIL take to update a closed loan?
The timing depends on when the lender reports the closure and when the credit information company processes it. RBI's reporting framework requires regular fortnightly reporting and sets timelines for submission and ingestion, but an individual account may not update immediately after payment.
3. Can I update my CIBIL report myself?
You can raise a dispute with CIBIL, but lender-reported account information generally requires verification and confirmation from the relevant credit institution before it can be changed.
4. What documents are required to update a closed loan in CIBIL?
Keep your loan closure statement, final payment receipt, bank statement, loan account statement and NDC/NOC, where applicable. The lender or credit information company may request additional details.
5. Can I raise a CIBIL dispute online?
Yes. You can raise a dispute through the official CIBIL website or your MyCIBIL account and track its status.
6. What if the bank does not update my loan closure?
Send a written complaint to the lender's grievance redressal team. If the issue remains unresolved, follow up with CIBIL and consider the applicable RBI complaint mechanism.
7. Can I get ₹100 per day for a delayed CIBIL update?
You may be eligible under the RBI compensation framework if your complaint meets the applicable conditions and is not resolved within 30 calendar days. The responsible entity and compensation depend on the circumstances of the delay.
8. Will an active loan shown incorrectly reduce my CIBIL score?
It may affect your credit profile depending on the reported balance, overdue status and other information. The exact impact varies, so correct the underlying error and check the updated report.
9. Does a closed loan disappear from CIBIL?
Not necessarily. A correctly closed loan can remain in your credit history. What matters is that the account status, outstanding balance and repayment history are accurate.
10. What is the difference between “Closed” and “Settled” in CIBIL?
“Closed” generally indicates that the loan has been fully repaid according to the lender's records. “Settled” generally indicates that the lender accepted a settlement amount under agreed terms, which may be less than the full contractual dues.
11. Can I apply for a new loan while my CIBIL report shows an old loan as active?
You can apply, but an incorrect active loan or balance may affect how a lender assesses your existing obligations. Consider requesting a correction before applying, especially if the reported balance is substantial.
12. How can I check whether my loan closure has been updated?
Download or refresh your latest credit report and verify the account status, outstanding balance, overdue amount and reporting date. Keep a copy of the corrected report for your records.
13. What should I do if CIBIL rejects my dispute?
Read the reason provided, contact the lender for clarification and submit supporting evidence if needed. You may raise another dispute where appropriate or escalate the matter through the lender's grievance process.
14. Can I remove a correctly closed loan from my CIBIL report?
A correctly reported closed account does not generally need to be removed. Credit reports are intended to reflect credit history, including past accounts, subject to applicable reporting and retention rules.
15. Where can I check official CIBIL dispute instructions?
Visit the official TransUnion CIBIL website and use its consumer dispute-resolution section. Avoid sharing sensitive financial information with unofficial websites or agents.
Published on : 29th September
Published by : SMITA
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed