

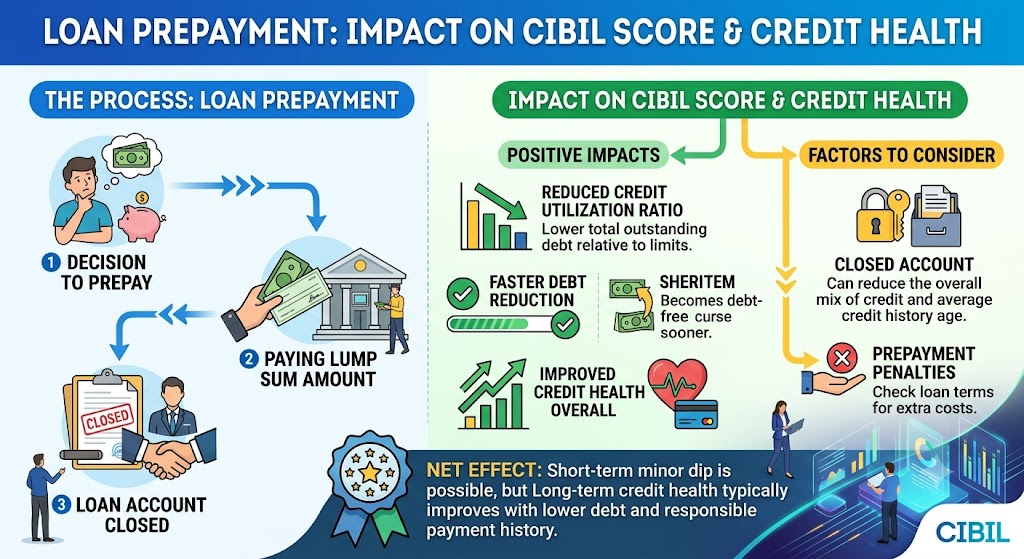
Loan prepayment is a financial strategy that allows borrowers to repay part or all of their outstanding loan amount before the scheduled repayment period ends. Many borrowers in India consider prepayment to reduce interest costs, become debt-free sooner, and improve their overall financial health. However, one common question is whether loan prepayment directly improves the CIBIL score.
Understanding the relationship between loan prepayment and your CIBIL score can help you make better borrowing decisions. While early repayment may support a healthy credit profile, its direct impact on your credit score depends on your repayment history, credit utilisation, loan type, and overall credit behaviour.
What Is Loan Prepayment?
Loan prepayment refers to paying back a portion or the entire outstanding loan amount before the original repayment schedule. It can be done using savings, bonuses, additional income, or other available funds.
There are two main types of loan prepayment:
-
Partial prepayment: You pay a portion of the outstanding principal, potentially reducing your EMI or loan tenure.
-
Full prepayment: You repay the entire outstanding balance before the loan's scheduled maturity date, closing the loan account.
Prepayment terms, charges, and eligibility depend on the loan agreement, lender policies, and applicable regulations.
What Is a CIBIL Score?
A CIBIL score is a three-digit number ranging from 300 to 900 that represents an individual's credit history and creditworthiness. Lenders use this score, along with other financial information, when evaluating loan and credit card applications.
A higher CIBIL score generally indicates a stronger credit profile and may improve your chances of qualifying for credit on favourable terms. Your score is influenced by several factors, including repayment history, credit utilisation, length of credit history, credit mix, and recent credit enquiries.
Does Loan Prepayment Improve Your CIBIL Score?
Loan prepayment does not automatically increase your CIBIL score. Its impact depends on how the repayment is reported by your lender and how the loan fits into your overall credit profile.
Here are some ways prepayment may influence your credit score:
1. Helps Maintain a Positive Repayment History
Repaying your loan on time is one of the most important aspects of maintaining a healthy credit profile. When you prepay a loan, you settle your outstanding obligations earlier than scheduled. Consistent repayment behaviour can support a positive credit history.
However, prepayment itself does not erase previous late payments or guarantee an immediate increase in your CIBIL score.
2. Reduces Outstanding Debt
Partial prepayment reduces the outstanding principal on a loan. This can lower your overall debt burden and improve your financial flexibility.
Although a lower outstanding balance may benefit your overall financial position, the reduction does not necessarily translate into an immediate improvement in your CIBIL score.
3. May Affect Your Credit Mix
Your credit mix refers to the different types of credit you have, such as secured loans, unsecured personal loans, and credit cards.
Closing your only active loan through full prepayment may change your credit mix and the composition of your credit history. This does not automatically mean your score will fall, but the effect can vary depending on your overall credit profile.
4. Can Change the Length of Your Active Credit History
When you close a loan early, it may affect the mix of active and closed accounts shown in your credit report. However, a closed account does not necessarily disappear immediately from your credit history.
The age and reporting status of your accounts can influence how lenders assess your credit profile, so the effect of early closure should be considered alongside your other credit activities.
Loan Prepayment vs Regular EMI Payments
Both regular EMI payments and early loan repayment can support responsible financial management, but they serve different purposes.
| Factor | Regular EMI Payments | Loan Prepayment |
|---|---|---|
| Repayment schedule | Follows the agreed schedule | Pays principal earlier |
| Interest cost | Continues as scheduled | May reduce future interest |
| Outstanding balance | Declines over time | Declines faster |
| CIBIL impact | Timely payments support credit health | No guaranteed score increase |
| Loan closure | At the scheduled maturity date | May close the loan earlier |
The best option depends on your financial goals, the interest rate, applicable prepayment charges, and your need for accessible savings.
Should You Prepay a Loan to Improve Your CIBIL Score?
Loan prepayment can be a sensible financial decision, but it should not be your only strategy for improving your CIBIL score.
Consider these practical steps:
-
Pay EMIs on time: Avoid missed or delayed payments across all loans and credit cards.
-
Maintain low credit utilisation: Try to keep your credit card balances low relative to their limits.
-
Review your credit report: Check that your loan balances, payment history, and account status are reported correctly.
-
Avoid unnecessary loan applications: Multiple applications within a short period may generate several hard enquiries.
-
Maintain an emergency fund: Avoid using all your savings to prepay a loan if doing so leaves you financially vulnerable.
-
Compare prepayment costs: Check applicable fees and calculate the interest savings before making a decision.
If your primary goal is to improve your CIBIL score, consistent repayment behaviour and responsible credit management are generally more important than making a single early payment.
What Happens to Your CIBIL Report After Loan Prepayment?
After you fully repay a loan, the lender should update the account status with the relevant credit bureau according to its reporting process. Depending on the lender's reporting cycle, the update may not appear immediately.
After full repayment, check your credit report to confirm that:
-
The outstanding loan balance is correctly updated.
-
The account status reflects closure, where applicable.
-
The lender has not incorrectly reported overdue amounts.
-
Any applicable closure documentation has been received.
If the information is incorrect or remains outdated, contact your lender and raise a dispute with the relevant credit bureau if necessary.
For partial prepayment, confirm how the lender has adjusted the outstanding principal, EMI, or tenure and whether the revised details are accurately reflected in your records.
Conclusion
Loan prepayment can help borrowers reduce interest costs, lower outstanding debt, and achieve financial freedom sooner. However, paying off a loan early does not guarantee an increase in your CIBIL score. The actual effect depends on your credit history, account details, and overall borrowing behaviour.
Published on : 19th October 2026
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed