

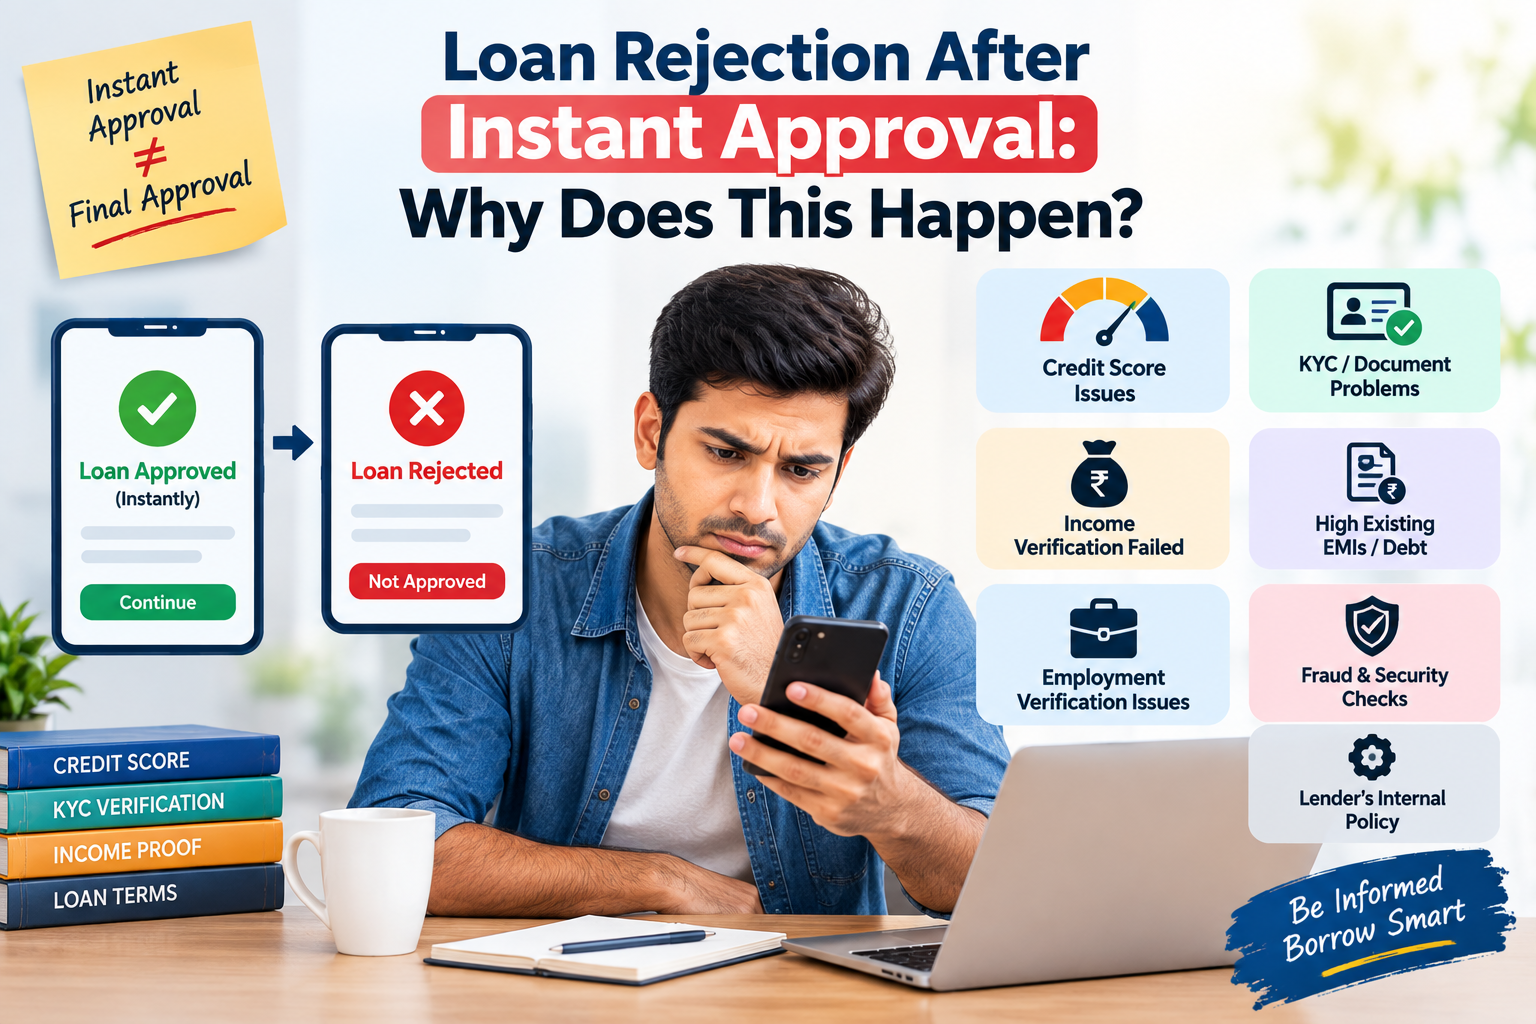
Getting an instant loan approval can feel like the loan is confirmed. However, in many cases, the first approval is only a preliminary or conditional decision. The lender may still complete detailed checks before making the final decision.
Why Can a Loan Be Rejected After Instant Approval?
1. Credit Score or Credit History
A lender may reject the application after checking the borrower's credit report, repayment history, existing loans, or recent credit enquiries.
2. Income Verification
If the income entered in the application does not match salary slips, bank statements, or other documents, the lender may stop the loan process.
3. Existing EMIs and Debt
High existing debt or multiple ongoing EMIs can affect the lender's assessment of repayment capacity.
4. KYC or Document Issues
Incorrect, expired, incomplete, or mismatched KYC documents can result in rejection.
5. Employment Verification
For salaried applicants, lenders may verify employment details. Any mismatch can affect the final decision.
6. Bank Account Verification
Problems with bank-account details, transaction history, or verification can also delay or reject the application.
7. Fraud and Security Checks
Digital lenders may perform additional security and fraud checks after the initial approval.
8. Internal Lending Rules
Each bank or NBFC has its own eligibility and risk policies. Meeting the initial criteria does not always guarantee final approval.
Instant Approval vs Final Approval
| Instant Approval | Final Approval |
|---|---|
| Usually based on initial information | Based on detailed verification |
| May be automated | Includes additional checks |
| Can be conditional | Confirms the lender's final decision |
| May change later | Usually followed by disbursal |
What Should You Do After Rejection?
- Check the reason given by the lender.
- Review your credit report for errors.
- Check your existing loans and EMI burden.
- Verify your KYC and income documents.
- Contact the actual bank or NBFC if the reason is unclear.
- Avoid submitting many loan applications at the same time.
Important RBI Guidance
The Reserve Bank of India requires regulated lenders involved in digital lending to assess a borrower's creditworthiness and disclose important loan information, including the Key Facts Statement (KFS) and Annual Percentage Rate (APR) where applicable.
Borrowers should verify who the actual lender is and carefully review the loan terms before accepting the loan.
Key Takeaways
- Instant approval does not always mean final approval.
- Credit, income, KYC and debt checks can change the decision.
- Document mismatches can lead to rejection.
- Always check the actual lender and loan terms.
- Avoid applying repeatedly without understanding why the loan was rejected.
FAQs
Can a loan be rejected after instant approval?
Yes. The initial approval may be conditional and subject to further verification.
Does loan rejection reduce my credit score?
The rejection itself is not necessarily a negative credit event, but credit enquiries associated with applications may appear on your credit report.
Why was my loan rejected after KYC?
Possible reasons include income verification, credit history, document mismatch, debt levels or internal lender policies.
What should I do after loan rejection?
Find out the reason, check your credit report and correct any documentation or financial issues before applying again.
Is instant loan approval guaranteed?
No. An instant or preliminary approval should not automatically be treated as guaranteed final approval.
Published on : 22th September
Published by : Shibam Nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed