

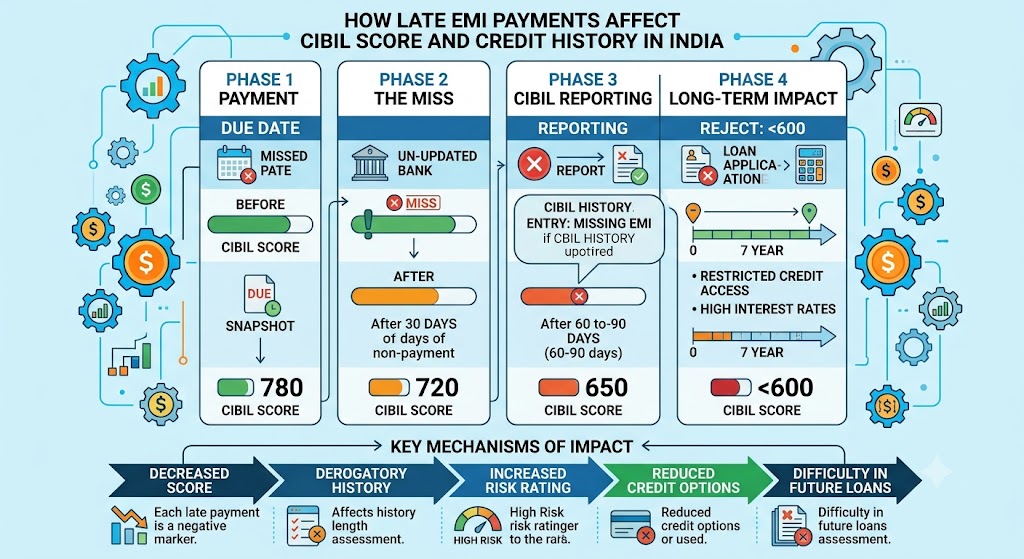
Missing an EMI (Equated Monthly Instalment) can affect your credit score, repayment history, and future loan eligibility. Whether you have a personal loan, home loan, car loan, or another credit facility, timely repayments are important for maintaining a healthy credit profile.
In India, lenders may report repayment information to credit bureaus such as TransUnion CIBIL, Experian, and Equifax. If you miss an EMI, the impact on your credit score depends on factors such as the length of the delay, your previous repayment history, and how the lender reports the payment.
Understanding what happens after a missed EMI can help you take the right steps to protect your credit profile.
What Is a Missed EMI?
A missed EMI occurs when a borrower fails to pay the required loan instalment by its scheduled due date. This may happen because of insufficient bank balance, salary delays, unexpected expenses, or simply forgetting the payment date.
When an EMI remains unpaid, the lender may charge applicable late-payment or penal charges according to the loan agreement. The overdue amount may also be reflected in your loan account and credit report, depending on the reporting timeline and applicable requirements.
A missed EMI should be addressed promptly to prevent the outstanding amount from increasing and to reduce the risk of further repayment difficulties.
How Does a Missed EMI Affect Your Credit Score?
Your credit score helps lenders evaluate your creditworthiness. In India, CIBIL scores generally range from 300 to 900, with higher scores typically indicating a stronger credit profile.
A missed EMI can affect your credit score in several ways.
1. Negative Impact on Repayment History
Your repayment history is an important part of your credit profile. If a lender reports a missed payment, it may indicate that you have not met your financial obligations on time.
Repeated missed EMIs can make your repayment history appear less reliable to potential lenders.
2. Possible Reduction in Credit Score
A reported missed EMI may lower your credit score. However, there is no fixed number of points that every borrower loses.
The impact depends on your existing credit history, the severity of the delay, the information in your credit report, and the scoring model used by the bureau.
3. Difficulty Getting Future Loans
Banks and non-banking financial companies (NBFCs) may review your credit report when you apply for a personal loan, credit card, or other credit facility.
A history of missed payments may reduce your chances of approval or affect the interest rate and terms offered. Final decisions also depend on your income, employment, existing EMIs, and repayment capacity.
4. Additional Charges and Financial Pressure
Apart from the possible credit score impact, a missed EMI may result in late-payment charges or other amounts permitted under your loan agreement.
If the overdue amount remains unpaid, the additional financial burden may make it harder to manage upcoming instalments.
Does One Missed EMI Affect Your Credit Score?
Yes, a single missed EMI can affect your credit profile if the lender reports the delay. However, the result is not identical for every borrower.
Consider two examples:
-
Borrower A: Has consistently paid EMIs on time but misses one instalment because of an unexpected expense.
-
Borrower B: Has a history of repeated repayment delays and misses another instalment.
The effect on their credit profiles may differ because their repayment histories and overall credit circumstances are different.
Paying the overdue EMI as soon as possible can help resolve the immediate outstanding amount. However, it does not guarantee that an accurate late-payment record will be removed or that the credit score will recover immediately.
How Long Can a Missed EMI Affect Your Credit Report?
A reported missed payment may remain in your credit history for several years, depending on applicable reporting and retention practices. Clearing the overdue amount does not automatically erase an accurate historical record.
If your credit report shows a missed payment even though you paid on time, check your payment receipt, bank statement, and lender account statement.
You can contact the lender and raise a dispute with the relevant credit bureau if the information is incorrect. Keep supporting documents available until the issue is resolved.
What Should You Do After Missing an EMI?
If you have missed an EMI, taking action quickly can help prevent the problem from becoming more serious.
Step 1: Check Your Loan Account
Confirm the amount due, the payment deadline, and any applicable charges. Make sure you understand whether the EMI failed because of insufficient funds, a bank issue, or another reason.
Step 2: Pay the Overdue EMI
If you can afford to do so, clear the overdue instalment promptly. Check with your lender whether any additional amount is required to bring your account up to date.
Step 3: Contact Your Lender
If you cannot make the payment immediately, explain your situation to the lender and ask about available repayment options. Avoid ignoring calls or notices regarding an overdue loan.
Step 4: Check Your Credit Report
Review your credit report to understand how the account is being reported. Check the payment history, outstanding balance, account status, and any overdue amount.
Step 5: Set Up EMI Reminders
Use calendar alerts, bank notifications, or automatic payments to reduce the risk of forgetting future instalments. Maintain sufficient funds in your account before the scheduled debit date.
How to Improve Your Credit Score After a Missed EMI
Improving your credit profile requires consistent repayment behaviour and responsible credit management.
|
Action |
Why It Helps |
|---|---|
|
Pay future EMIs on time |
Builds a positive repayment history |
|
Clear overdue amounts |
Resolves outstanding arrears |
|
Keep credit card utilisation low |
Supports responsible credit usage |
|
Avoid unnecessary loan applications |
Reduces avoidable hard enquiries |
|
Check credit reports regularly |
Helps identify errors |
|
Manage existing debt carefully |
Supports long-term repayment capacity |
Credit score improvement takes time, and results depend on your complete credit profile. Avoid applying for multiple loans simply to try to improve your score.
Missed EMI vs Loan Default
A missed EMI means an instalment has not been paid by its due date. Loan default is generally a more serious situation involving failure to meet repayment obligations, although the precise classification depends on the loan terms and applicable rules.
A short delay should not automatically be treated as equivalent to a long-term default. However, repeated or prolonged non-payment can lead to more serious consequences, including additional charges, adverse credit reporting, collection activity, and potential legal action where applicable.
If you expect difficulty making your next payment, contact your lender early rather than allowing several instalments to become overdue.
Frequently Asked Questions (FAQs)
1. Will one missed EMI reduce my CIBIL score?
It may reduce your score if the missed payment is reported. The actual impact depends on your credit history, the reporting circumstances, and the scoring model.
2. Can I recover my credit score after missing an EMI?
Yes, your credit profile can improve over time through timely repayments, clearing overdue amounts, and maintaining responsible credit usage.
3. Does paying a missed EMI remove it from my credit report?
No. Paying the overdue amount does not automatically remove an accurate historical payment record.
4. Can a missed EMI lead to loan rejection?
Yes, it may affect the lender's decision. However, lenders also assess income, existing debt, employment stability, documents, and other eligibility criteria.
5. How can I check whether my missed EMI has affected my credit score?
Review your latest credit report from the relevant bureau. Check your loan account's repayment history and reported overdue amounts.
6. What if I paid my EMI but it is still marked as missed?
Contact your lender with your payment receipt and bank statement. If the information is incorrect, request a correction and raise a dispute with the relevant credit bureau.
Conclusion
A missed EMI can affect your credit score, repayment history, and future borrowing opportunities. The impact depends on the duration of the delay, your previous credit behaviour, and how the lender reports the payment.
The best approach is to clear overdue instalments as soon as reasonably possible, contact your lender if you face financial difficulties, and review your credit report for accuracy. By paying future EMIs on time and managing debt responsibly, you can strengthen your credit profile and improve your chances of meeting lenders' eligibility requirements.
Published on : 18th October 2026
Published by : Yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed