

Introduction
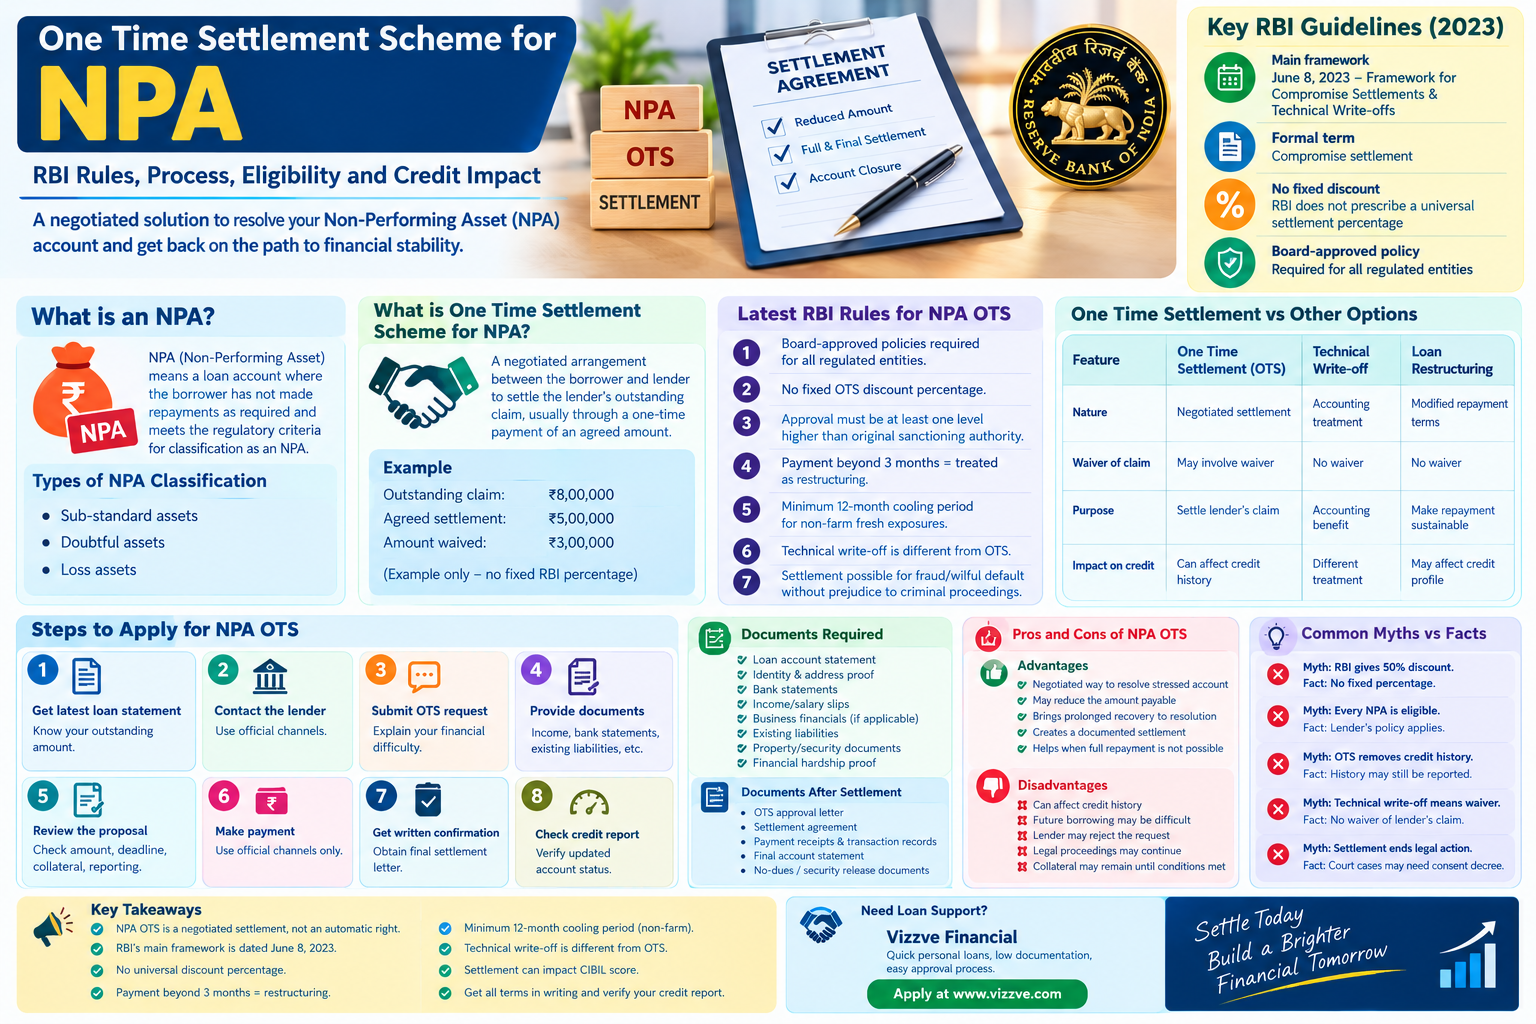
A One Time Settlement (OTS) Scheme for NPA is a negotiated arrangement through which a lender and borrower agree to settle the lender's outstanding claim, generally through payment of an agreed amount in cash.
Under RBI's current regulatory framework, the formal term is “compromise settlement.” RBI defines a compromise settlement as a negotiated arrangement with the borrower to fully settle the claims of the regulated entity in cash, which may involve the lender sacrificing part of the amount due.
RBI issued its Framework for Compromise Settlements and Technical Write-offs on June 8, 2023. The framework applies to regulated entities including commercial banks, specified cooperative banks, All-India Financial Institutions and NBFCs, including housing finance companies.
The framework also repealed the earlier 2010 RBI circular specifically titled “Compromise/Negotiated/One Time settlement of Non-Performing Assets (NPAs)”.
AI Answer Box: What Is One Time Settlement Scheme for NPA?
One Time Settlement Scheme for NPA is a negotiated settlement between a borrower and lender to resolve an outstanding stressed or non-performing loan account.
Under RBI's current framework:
- The formal regulatory term is compromise settlement.
- Regulated entities must have Board-approved policies for compromise settlements.
- RBI does not prescribe one universal OTS discount percentage.
- The settlement amount can involve a lender sacrificing part of its claim.
- The lender's policy can consider the current realisable value of available security or collateral.
- Settlement approval must follow the lender's prescribed authority structure.
- If payment of the agreed settlement amount takes more than three months, the arrangement is treated as restructuring for prudential purposes.
- For non-farm-credit exposures, the cooling period before fresh exposure has a minimum floor of 12 months.
- Settlement does not automatically remove other legal or criminal proceedings where applicable.
Quick Summary
| Feature | RBI Framework |
|---|---|
| Formal term | Compromise settlement |
| Main framework | June 8, 2023 |
| Applicable to | Covered RBI-regulated entities |
| Fixed OTS discount | No universal percentage |
| Board-approved policy | Required |
| Settlement amount | Determined under lender's policy |
| Payment beyond 3 months | Treated as restructuring |
| Non-farm cooling period | Minimum 12 months |
| Technical write-off | Different from OTS |
| Pending judicial recovery | Consent decree may be required |
What Is an NPA?
NPA stands for Non-Performing Asset.
In simple terms, a loan account becomes non-performing when the borrower does not make repayments as required and the account meets the applicable regulatory criteria for NPA classification.
An NPA is important for both the lender and borrower because it indicates serious repayment stress.
Common Types of NPA Classification
Depending on the applicable regulatory framework, NPAs can be classified into categories such as:
- Sub-standard assets
- Doubtful assets
- Loss assets
The exact classification and applicable prudential treatment depend on the relevant RBI directions and type of regulated entity.
What Is an NPA One Time Settlement?
An NPA OTS is a negotiated arrangement between the borrower and lender to resolve the outstanding claim.
For example:
Outstanding claim: ₹8,00,000
Agreed settlement amount: ₹5,00,000
If the lender's written settlement agreement states that payment of ₹5,00,000 completely settles the claim, the borrower pays that amount according to the agreed terms.
The ₹3,00,000 difference in this example represents the lender's agreed sacrifice or waiver.
Important: This is only an illustration. RBI does not prescribe a universal 40%, 50% or 60% settlement discount. The lender's Board-approved policy and account circumstances determine the settlement terms.
Latest RBI Rules for NPA One Time Settlement
1. Banks and Other Regulated Entities Need Board-Approved Policies
RBI requires regulated entities to maintain Board-approved policies for compromise settlements and technical write-offs.
These policies must establish the process and conditions applicable to settlements.
What Can the Policy Cover?
A lender's policy can address:
- Eligibility conditions
- Minimum ageing
- Security and collateral
- Recovery prospects
- Settlement authority
- Permissible sacrifice
- Approval procedures
- Reporting
- Staff accountability
- Cooling period
2. There Is No Fixed RBI OTS Discount
One of the most common misconceptions is that RBI has fixed a particular percentage for NPA settlement.
RBI does not prescribe a universal settlement percentage.
The lender's policy must provide for permissible sacrifice for different categories of exposure while prudently considering the current realisable value of security or collateral where available.
Therefore, statements such as “RBI has ordered banks to settle every NPA at 50%” should not be treated as a general RBI rule.
3. OTS Approval Must Follow the Lender's Authority Structure
RBI requires compromise-settlement approval to rest with an authority that is at least one level higher than the authority responsible for sanctioning the original credit or investment exposure.
An official who participated in sanctioning the loan cannot participate in approving the compromise settlement of that same account.
This is intended to create an appropriate separation between the original lending decision and the later settlement decision.
4. Payment Period Beyond Three Months
This is one of the important rules under the RBI framework.
If the agreed settlement amount is payable over a period exceeding three months, the compromise settlement is treated as restructuring under the applicable prudential framework.
Why Borrowers Should Check This
Before signing an OTS agreement, borrowers should carefully review:
- Total settlement amount
- Number of payments
- Payment deadlines
- Consequences of missing a payment
- Whether the arrangement qualifies as restructuring
5. Cooling Period After NPA Settlement
RBI's framework provides a cooling period before a regulated entity can assume fresh exposure to a borrower after a compromise settlement.
For exposures other than farm credit, the cooling period has a minimum floor of 12 months.
A regulated entity can prescribe a longer cooling period through its Board-approved policy.
For farm-credit exposures, the cooling period is determined according to the lender's Board-approved policy.
Important
The cooling period should not automatically be interpreted as a universal prohibition on every future loan from every lender.
It specifically concerns fresh exposure by the regulated entity under the RBI framework.
6. Can Fraud or Wilful-Default Accounts Be Settled?
RBI permits regulated entities to undertake compromise settlements or technical write-offs for accounts categorised as fraud or wilful default.
However, this is without prejudice to criminal proceedings against the concerned borrower or debtor.
Therefore, financial settlement and criminal proceedings are separate matters.
7. What Happens If the NPA Case Is in Court?
Where a regulated entity has already commenced recovery proceedings before a judicial forum and those proceedings are pending, a settlement is subject to obtaining a consent decree from the concerned judicial authority.
Borrowers should therefore obtain professional legal advice where the account involves:
- Court proceedings
- Recovery tribunals
- SARFAESI proceedings
- Insolvency proceedings
- Security enforcement
- Multiple creditors
One Time Settlement vs Technical Write-Off
These two concepts are frequently confused.
| One Time Settlement | Technical Write-Off |
|---|---|
| Negotiated settlement | Accounting treatment |
| Borrower agrees to settlement terms | Loan remains outstanding at borrower-account level |
| May involve waiver/sacrifice | Does not itself waive the lender's claim |
| Intended to settle the lender's claim | Recovery rights remain |
| Borrower generally makes agreed payment | Lender writes off for accounting purposes |
RBI specifically distinguishes technical write-offs from compromise settlements. A technical write-off does not involve waiver of the lender's claim against the borrower.
One Time Settlement vs Loan Restructuring
OTS and restructuring are also different.
| OTS | Loan Restructuring |
|---|---|
| Negotiated settlement | Modification of repayment terms |
| Intended to settle claims | Intended to make repayment sustainable |
| May involve lender sacrifice | May change tenure, repayment or other terms |
| Usually involves agreed settlement payment | Borrower continues repayment under revised terms |
| Can have credit-reporting implications | Can also affect credit profile |
An important RBI rule is that a compromise settlement where the agreed settlement amount takes more than three months to pay is treated as restructuring for prudential purposes.
Does NPA OTS Affect CIBIL Score?
Yes, an NPA and subsequent settlement can have significant implications for a borrower's credit history.
The borrower should not assume that settling an NPA makes the previous repayment history disappear.
After settlement, borrowers should:
- Obtain written confirmation from the lender.
- Check how the account has been reported.
- Review the credit report.
- Verify that the account information is accurate.
- Raise a correction request if inaccurate information is reported.
OTS and Credit History
| Situation | Credit Consideration |
|---|---|
| Regular repayment | Generally reflects positive repayment behaviour |
| NPA/default | Indicates repayment problems |
| Settled account | May be considered negatively by future lenders |
| Full repayment/closure | Different from negotiated settlement |
| Technical write-off | Does not automatically mean debt is waived |
The exact impact on future credit decisions depends on the credit report, lender policies and the borrower's overall financial profile.
Who May Consider an NPA OTS?
There is no single RBI rule stating that every NPA borrower must receive an OTS.
A lender may consider settlement depending on:
- Account status
- Age of the NPA
- Outstanding amount
- Security available
- Current collateral value
- Recovery prospects
- Borrower's circumstances
- Cost of recovery
- Legal proceedings
- Internal settlement policy
RBI's framework specifically requires lenders to consider the current realisable value of available security or collateral while formulating their settlement approach.
How to Apply for One Time Settlement of an NPA
Step 1: Obtain Your Loan Statement
Request the latest statement from the bank or financial institution.
Check:
- Principal outstanding
- Interest
- Charges
- Total dues
- Security details
- Account classification
Step 2: Contact the Lender Through Official Channels
Approach the bank branch, authorised recovery department or official customer service channel.
Avoid dealing with unauthorised intermediaries.
Step 3: Submit an OTS Request
Write a formal request explaining:
- Financial difficulty
- Current repayment capacity
- Amount you can arrange
- Proposed settlement timeline
Step 4: Submit Supporting Documents
The lender may request:
- Bank statements
- Salary or income documents
- Business financial records
- Existing debt details
- Financial hardship documents
- Asset or collateral information
Step 5: Review the Settlement Proposal
Check:
- Settlement amount
- Payment deadline
- Instalments
- Interest treatment
- Charges
- Legal conditions
- Collateral release conditions
- Account-status reporting
Step 6: Make Payment Through Official Channels
Pay only through authorised bank channels and preserve the transaction records.
Step 7: Obtain Written Settlement Confirmation
Ask the lender for appropriate documentation confirming settlement according to the agreement.
Step 8: Check Your Credit Report
After the lender updates the information, review your credit report for accuracy.
Documents Required for NPA OTS
Depending on the lender and circumstances, borrowers may need:
- Loan account statement
- Identity proof
- Address proof
- Bank statements
- Salary slips
- Income-tax documents
- Business financial statements
- Proof of financial hardship
- Existing liability details
- Property/security documents
- Legal documents, where applicable
The exact requirements vary between lenders.
Documents to Obtain After OTS
After completing the settlement, retain:
- OTS approval letter
- Settlement agreement
- Payment receipts
- Bank transaction records
- Final account statement
- Settlement confirmation
- No-dues document where applicable
- Security-release documents where applicable
- Copies of relevant correspondence
Why Written Proof Matters
An oral assurance from a recovery representative is not a substitute for the lender's formal written settlement documentation.
Example of an NPA One Time Settlement
Consider this hypothetical example:
| Particular | Amount |
|---|---|
| Outstanding loan claim | ₹10,00,000 |
| Amount agreed under OTS | ₹6,50,000 |
| Amount potentially waived | ₹3,50,000 |
| Payment deadline | As specified in agreement |
If the lender's written agreement states that ₹6,50,000 fully settles the claim and the borrower pays it according to the agreed terms, the settlement can resolve the lender's claim as specified in that agreement.
This is an illustrative example only. It is not an RBI-prescribed settlement formula.
Pros and Cons of NPA One Time Settlement
Potential Advantages
- Can provide a negotiated route for resolving a stressed account.
- May reduce the amount payable if the lender agrees to a concession.
- Can bring prolonged recovery discussions toward resolution.
- Provides a structured settlement arrangement.
- May help borrowers who cannot realistically repay the entire outstanding amount.
Potential Disadvantages
- Settlement can affect credit history.
- Future lenders may consider the settlement history.
- The lender is not required to approve every OTS request.
- Legal proceedings may require additional steps.
- Collateral may remain subject to settlement conditions until obligations are completed.
- Failure to meet OTS conditions can create additional complications.
Common Myths About NPA OTS
Myth 1: RBI Gives Every NPA Borrower a 50% Discount
Fact: RBI does not prescribe a universal OTS discount percentage.
Myth 2: Every NPA Account Is Automatically Eligible
Fact: Settlement is governed by the lender's Board-approved policy and account circumstances.
Myth 3: OTS Means the Credit History Is Deleted
Fact: Settlement does not mean previous credit information automatically disappears.
Myth 4: Technical Write-Off Means the Loan Is Forgiven
Fact: A technical write-off does not waive the lender's claim.
Myth 5: Court Cases Automatically End After OTS
Fact: Where judicial recovery proceedings are pending, the settlement may require a consent decree from the relevant judicial authority.
Important RBI Rules at a Glance
| Rule | Explanation |
|---|---|
| Board-approved policy | Required for compromise settlements |
| No fixed discount | RBI does not prescribe one universal percentage |
| Collateral | Current realisable value may be considered |
| Approval authority | At least one level above original credit sanctioning authority |
| Payment over 3 months | Treated as restructuring |
| Cooling period | Minimum 12 months for non-farm fresh exposures |
| Farm credit | Cooling period according to lender's Board-approved policy |
| Fraud/wilful default | Settlement possible without prejudice to criminal proceedings |
| Court recovery | Consent decree may be required |
| Technical write-off | Does not waive lender's claim |
Expert Commentary: What Borrowers Should Check Before Accepting OTS
The most important mistake borrowers can make is focusing only on how much money is being waived.
An OTS should be evaluated based on the complete agreement.
Before accepting a settlement, check:
- What exactly is being settled?
- Is the settlement amount final?
- What is the last date for payment?
- Are instalments permitted?
- What happens if a payment is missed?
- What happens to the collateral?
- Are there pending legal proceedings?
- How will the account be reported to credit information companies?
- What documents will be provided after payment?
- Does the agreement contain any continuing obligations?
Trust-Building Tip
Always obtain the settlement terms in writing from the lender's authorised channel. Do not rely only on verbal promises from recovery agents or intermediaries.
NPA OTS and Borrower Rights
Borrowers should:
- Request a written settlement proposal.
- Understand the complete payment obligation.
- Ask for clarification of charges.
- Maintain copies of all correspondence.
- Use official payment channels.
- Request appropriate final documentation.
- Check their credit report after settlement.
- Seek legal advice when court or security-enforcement proceedings are involved.
One Time Settlement Scheme for NPA: Step-by-Step Checklist
Before Applying
☐ Obtain the latest loan statement
☐ Understand the outstanding amount
☐ Review your repayment capacity
☐ Identify available funds
☐ Check whether legal proceedings are pending
During Negotiation
☐ Submit a written OTS request
☐ Ask for the lender's written proposal
☐ Check the settlement amount
☐ Check the payment deadline
☐ Understand collateral conditions
☐ Ask about credit reporting
After Payment
☐ Keep payment receipts
☐ Obtain settlement confirmation
☐ Obtain final account documents
☐ Collect security-release documents where applicable
☐ Check your credit report
Key Takeaways
- NPA OTS is a negotiated settlement arrangement between a borrower and lender.
- RBI's current central framework is the Framework for Compromise Settlements and Technical Write-offs dated June 8, 2023.
- The formal RBI term is compromise settlement.
- RBI does not prescribe one universal settlement percentage.
- Lenders must have Board-approved policies.
- The lender can consider the realisable value of security or collateral.
- Payment taking more than three months is treated as restructuring for prudential purposes.
- The minimum cooling period for non-farm fresh exposures is 12 months.
- Technical write-off is different from OTS.
- Settlement does not automatically erase credit history.
- Pending court proceedings may require a consent decree.
- Fraud and wilful-default accounts may be settled without prejudice to criminal proceedings.
- Borrowers should obtain all settlement terms and final documents in writing.
AI Summary for Google AI Overview, ChatGPT Search and Perplexity
One Time Settlement Scheme for NPA: RBI's current framework treats one-time settlement as a compromise settlement, meaning a negotiated arrangement to fully settle a regulated entity's claim in cash, potentially involving a waiver or sacrifice of part of the amount due. RBI's June 8, 2023 framework requires regulated entities to maintain Board-approved policies and does not prescribe a universal settlement discount. If the agreed settlement amount takes more than three months to pay, it is treated as restructuring for prudential purposes. A minimum 12-month cooling period applies to fresh non-farm exposures after compromise settlement. Borrowers should obtain written settlement terms, preserve payment records and check their credit information after settlement.
Frequently Asked Questions
1. What is One Time Settlement Scheme for NPA?
It is a negotiated arrangement between a borrower and lender to settle the lender's claim, generally through payment of an agreed cash settlement amount.
2. Is NPA OTS allowed under RBI rules?
Yes. RBI recognises compromise settlements as a valid resolution mechanism under its current framework.
3. Does RBI fix the OTS discount percentage?
No. RBI does not prescribe a universal settlement percentage.
4. Can every NPA borrower get an OTS?
Not automatically. The lender considers the account under its Board-approved compromise-settlement policy.
5. What is the current RBI framework for NPA OTS?
The main framework is RBI's Framework for Compromise Settlements and Technical Write-offs dated June 8, 2023.
6. What happens if OTS payment takes more than three months?
A compromise settlement where the agreed settlement amount takes more than three months to pay is treated as restructuring under the applicable prudential framework.
7. What is the cooling period after NPA settlement?
For exposures other than farm credit, the cooling period has a minimum floor of 12 months. A lender can prescribe a longer period through its Board-approved policy.
8. Does NPA settlement affect CIBIL Score?
A settled NPA can have an important impact on credit history and may be considered by future lenders.
9. Is technical write-off the same as NPA OTS?
No. A technical write-off is an accounting treatment and does not itself waive the lender's claim against the borrower.
10. Can a bank reject an OTS request?
Yes. RBI does not create a universal right for every borrower to demand a particular settlement amount. The lender's approved policy and account circumstances apply.
11. Can fraud or wilful-default accounts be settled?
RBI permits compromise settlements for such accounts, but this is without prejudice to criminal proceedings.
12. What if an NPA case is already in court?
Where recovery proceedings are pending before a judicial forum, the settlement is subject to obtaining a consent decree from the concerned judicial authority.
13. What documents should I obtain after OTS?
Keep the OTS agreement, payment receipts, final account statement, settlement confirmation and applicable security-release documents.
14. Does OTS completely remove an NPA from my credit history?
No. Settlement does not mean that previous repayment history automatically disappears.
15. Is One Time Settlement the same as loan closure?
No. An OTS is a negotiated settlement and can involve a lender's sacrifice or waiver, whereas regular loan closure generally follows repayment of the dues according to the loan agreement.
Vizzve Financial – Loan Support
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
Borrowers should review eligibility, interest rates, fees, repayment obligations and all applicable terms before choosing a financial product.
Conclusion
The One Time Settlement Scheme for NPA provides a structured way for lenders and borrowers to resolve stressed loan accounts through negotiated compromise settlements.
RBI's June 8, 2023 framework is the key regulatory reference. It requires regulated entities to maintain Board-approved policies, establishes approval and reporting requirements, addresses cooling periods and provides rules for compromise settlements involving fraud and wilful-default accounts.
For borrowers, the most important point is that there is no universal RBI-mandated OTS discount. The settlement amount depends on the lender's approved policy and the specific circumstances of the account.
Before accepting an OTS, carefully review the settlement amount, payment schedule, credit-reporting implications, legal status and collateral conditions. Always obtain the agreement and final settlement confirmation in writing.
Published on : 23rd september
Published by : Bhargavi
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed