

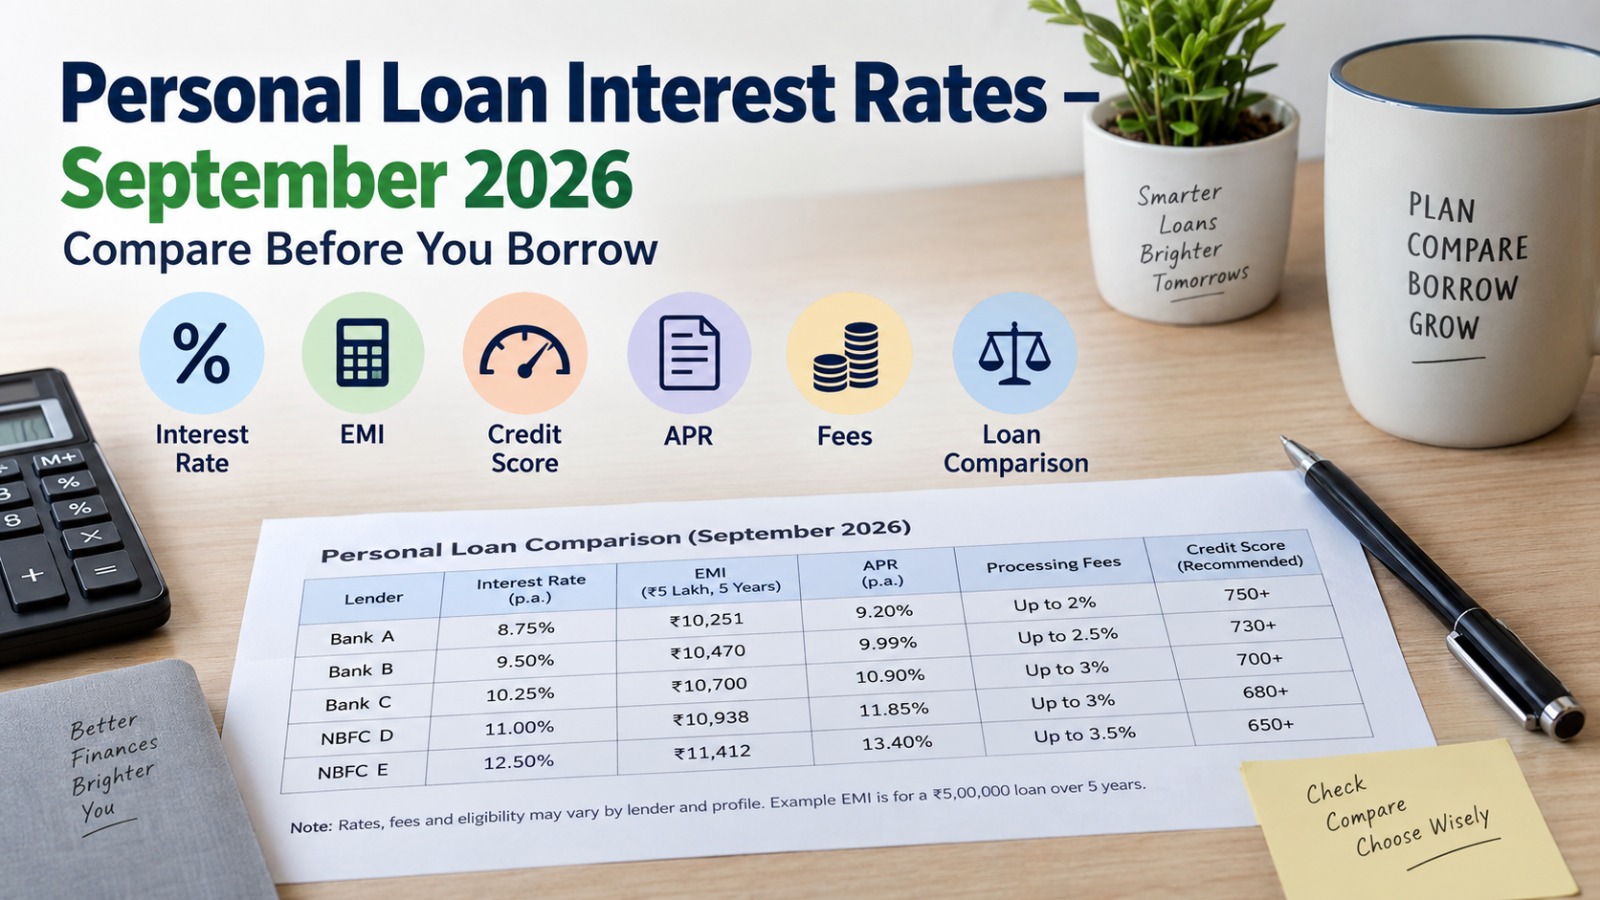
Personal loan interest rates are an important factor when deciding whether to borrow. In September 2026, advertised personal loan rates in India start around 8.75% per annum, while several major private-sector banks list starting rates around 9.99%. However, the final rate depends on factors such as credit history, income, employment profile, existing debt and lender policies.
Personal Loan Interest Rates in September 2026
Recent September 2026 data shows the following indicative rates:
| Bank/Lender | Indicative Interest Rate |
|---|---|
| Bank of Maharashtra | 8.75%–13.55% |
| HSBC Bank | 9.75% onwards |
| Axis Bank | 9.99% onwards |
| HDFC Bank | 9.99% onwards |
| ICICI Bank | 9.99% onwards |
| IDFC FIRST Bank | 9.99% onwards |
| Kotak Mahindra Bank | 9.99% onwards |
| SBI | 10.00% onwards |
| Bank of Baroda | 10.15%–18.00% |
| IndusInd Bank | 10.35% onwards |
These are published/indicative rates, not guaranteed rates for every applicant. Processing fees and other charges can also vary.
What Determines Your Personal Loan Interest Rate?
1. Credit Score
A strong credit history may help borrowers qualify for more competitive pricing. Lenders also consider repayment history and existing credit obligations.
2. Income and Employment
Stable income and employment can influence the lender's assessment of repayment capacity.
3. Existing EMIs
If you already have several loans or high monthly obligations, the lender may offer different terms or a lower eligible loan amount.
4. Loan Amount and Tenure
A longer tenure can reduce the monthly EMI but may increase the total interest paid over the life of the loan.
5. Lender's Risk Assessment
Banks and NBFCs use their own credit policies and risk-based pricing. Therefore, two lenders can offer different rates to the same borrower.
Don't Compare Only the Interest Rate
A low advertised interest rate does not necessarily mean the lowest overall borrowing cost.
Before accepting a personal loan, check:
- Interest rate
- APR
- Processing fee
- GST and applicable charges
- Prepayment or foreclosure conditions
- Late-payment or penal charges
- Loan tenure
- Total interest payable
- Net amount actually disbursed
The RBI requires regulated entities to provide borrowers with a Key Facts Statement (KFS) containing important information about the loan and its overall cost.
Example: ₹5 Lakh Personal Loan
For illustration, a ₹5 lakh loan for five years at 8.75% would have an EMI of roughly ₹10,319. At 9.99%, the EMI would be about ₹10,621.
The actual EMI and total cost can differ depending on the lender's calculation method, fees and final loan terms.
How to Compare Personal Loans in September 2026
Use this simple checklist:
- Compare the final interest rate offered to you.
- Check the APR and KFS.
- Calculate the total interest over the full tenure.
- Compare processing and other fees.
- Check prepayment and foreclosure conditions.
- Make sure the EMI fits comfortably within your monthly budget.
- Apply only through the lender or a verified lending platform.
Key Takeaways
- Personal loan rates in September 2026 start around 8.75% in recent published comparisons.
- Several major private banks list starting rates around 9.99%.
- Your actual rate can depend on credit score, income, debt and lender assessment.
- Don't compare loans based only on the headline interest rate.
- Always check the KFS, APR, fees, EMI and total repayment amount before accepting a loan.
FAQs
What are personal loan interest rates in September 2026?
Recent published comparisons show rates starting around 8.75%, while several major private banks quote starting rates around 9.99%.
Does a higher credit score guarantee a lower rate?
No. Credit score is one factor. Income, employment, existing debt and lender-specific policies can also affect pricing.
Is 9.99% a guaranteed personal loan rate?
No. A starting or advertised rate does not guarantee that every applicant will receive that rate.
What is APR?
APR represents the annualized cost of borrowing and can help borrowers understand the loan cost beyond the headline interest rate.
What is a KFS?
A Key Facts Statement provides important loan information, including key costs and terms, in a standardized format.
Should I choose a longer loan tenure?
A longer tenure may reduce the monthly EMI but can increase the total interest paid.
What should I check before taking a personal loan?
Check the interest rate, APR, processing fee, EMI, total repayment, prepayment conditions and other charges.
Published on : 22th September
Published by : Shibam Nath
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed