

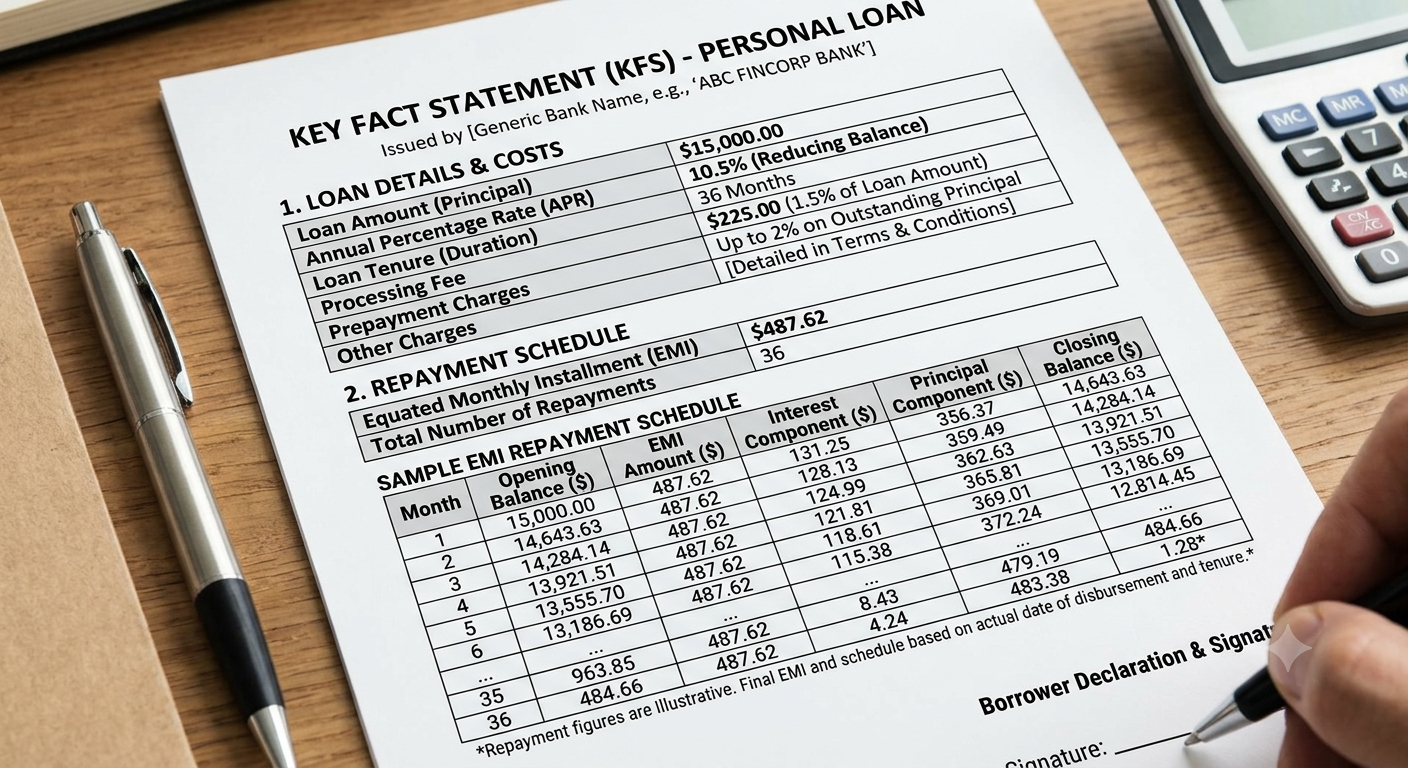
When applying for a personal loan, understanding the loan amount, interest rate, processing fees, repayment schedule, and other charges is essential. One important document borrowers should review before accepting a loan is the Key Facts Statement (KFS).
A Personal Loan KFS provides a clear summary of the key terms and costs associated with a loan. It helps borrowers understand their financial obligations, compare loan offers, and make informed borrowing decisions. For anyone planning to apply for a personal loan online, reviewing the KFS carefully can help prevent confusion about repayment and hidden costs.
What Is a Personal Loan KFS?
KFS stands for Key Facts Statement. It is a standardised document provided by a regulated lender that explains the important details of a loan in a clear and easy-to-understand format.
For applicable retail term loans, the Reserve Bank of India (RBI) requires lenders to provide a KFS so borrowers can understand the loan's pricing and essential conditions before entering into the agreement.
The KFS generally includes information such as the sanctioned loan amount, annual percentage rate (APR), repayment schedule, applicable fees, and other relevant charges.
Why Is the KFS Important for Personal Loan Borrowers?
The KFS helps borrowers understand the overall cost of borrowing rather than focusing only on the advertised interest rate.
Key benefits include:
-
Transparency: Understand the loan's main terms and applicable charges.
-
Cost comparison: Compare the APR and charges across eligible loan offers.
-
Better financial planning: Review repayment amounts and schedules before accepting a loan.
-
Reduced confusion: Check which fees apply and when they may be payable.
-
Informed decisions: Evaluate whether the loan fits your budget and repayment capacity.
Key Details Included in a Personal Loan KFS
A KFS usually contains the following information:
|
KFS detail |
What it means |
|---|---|
|
Loan amount |
Amount sanctioned by the lender |
|
Interest rate |
Rate charged on the borrowed amount |
|
APR |
Annual cost of credit, including interest and applicable charges |
|
Processing fee |
Fee charged for processing the loan |
|
EMI details |
Repayment amount and schedule |
|
Loan tenure |
Period allowed for repayment |
|
Other charges |
Applicable third-party charges, penalties or fees, as disclosed |
|
Repayment schedule |
Breakdown of principal and interest payments |
According to the RBI's April 15, 2024 circular, the KFS must include an APR calculation and an amortisation schedule for applicable loans. The rules apply to new retail and MSME term loans sanctioned on or after October 1, 2024.
What Is APR in a Personal Loan KFS?
Annual Percentage Rate (APR) represents the annual cost of credit, including the interest rate and applicable charges associated with the loan. It gives borrowers a broader view of borrowing costs than the interest rate alone.
For example, two lenders may advertise similar interest rates but charge different processing fees. Comparing their APRs and other loan terms can help you understand which offer may be more economical.
Always compare loans with similar amounts and repayment tenures for a more meaningful comparison.
How to Read Your Personal Loan KFS Before Applying
Follow these steps before accepting a personal loan offer:
-
Verify the loan amount: Confirm the amount sanctioned and the amount you will actually receive after applicable deductions.
-
Check the interest rate and APR: Understand the borrowing cost and all disclosed charges.
-
Review the EMI schedule: Make sure the monthly repayment fits your income and expenses.
-
Examine processing fees: Check applicable fees, taxes and third-party charges.
-
Read the repayment terms: Understand the due dates, tenure and applicable late-payment charges.
-
Check the validity period: Under the RBI framework, the KFS validity period is at least three working days for loans with a tenure of seven days or more, and one working day for shorter-tenure loans.
-
Keep a copy: Save the KFS and loan agreement for future reference.
The lender should explain the KFS in a language you understand and obtain your acknowledgement that you have understood its contents.
Common Mistakes to Avoid
Borrowers sometimes focus only on the interest rate and overlook other important loan conditions. Avoid these common mistakes:
-
Accepting a loan without checking the APR.
-
Ignoring processing fees and applicable taxes.
-
Overlooking the EMI schedule and repayment dates.
-
Assuming every loan app is directly operated by a regulated lender.
-
Accepting unclear terms without asking for an explanation.
-
Sharing OTPs or banking passwords with unauthorised individuals.
Before applying, verify the actual regulated lender behind the loan offer and carefully read all loan documents.
How Vizzve Helps Borrowers Make Informed Decisions
At Vizzve, borrowers can use educational resources to understand personal loans, repayment obligations, processing fees and other borrowing considerations. Learning how to read a KFS can help you evaluate loan offers more confidently.
Before choosing any personal loan, review the lender's terms, check the total borrowing cost, and ensure the EMI is affordable. Loan approval and disbursal remain subject to the lender's eligibility criteria and verification process.
Conclusion
A Personal Loan KFS is an important document that helps borrowers understand the costs, repayment schedule and key conditions of a loan before accepting the offer. By reviewing the APR, processing fees, EMI details and other applicable charges, you can make a more informed borrowing decision.
Remember: Never accept a personal loan based on the advertised interest rate alone. Read the KFS carefully and borrow only what you can comfortably repay.
Published on : 29th October 2026
Published by : Yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed