

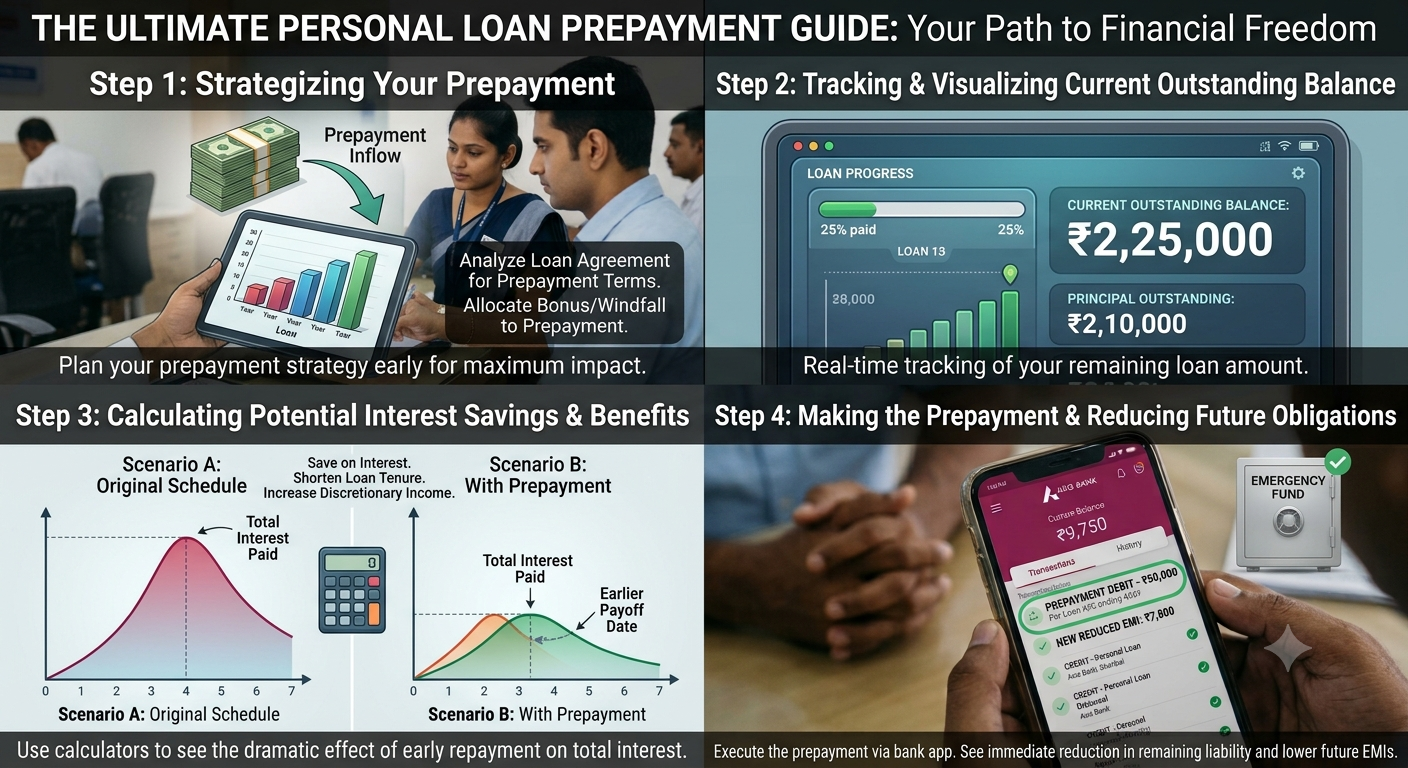
A personal loan can help you manage medical expenses, home repairs, education costs and other financial needs. However, repaying the loan before the scheduled tenure ends may help you reduce your interest burden. This process is known as personal loan prepayment.
Before making an early payment, it is important to understand the benefits, possible charges and conditions set by your lender. A well-planned prepayment strategy can help you manage debt while keeping enough money available for emergencies.
What Is Personal Loan Prepayment?
Personal loan prepayment means paying back part or all of your outstanding loan amount before the original repayment schedule is completed.
There are generally two types of prepayment:
-
Part-prepayment: You pay an additional amount towards the outstanding principal while continuing your regular EMIs.
-
Full prepayment or foreclosure: You repay the entire outstanding loan amount before the end of the agreed tenure.
The availability of these options depends on your loan agreement, lender policies and applicable regulations.
Benefits of Personal Loan Prepayment
Prepaying a personal loan can offer several advantages when planned carefully.
1. Save on Interest Costs
When you reduce your outstanding principal earlier, you may reduce the interest payable over the remaining loan tenure. The actual savings depend on the interest rate, outstanding balance, remaining tenure and applicable charges.
2. Reduce Your Debt Burden
Early repayment can help you become debt-free sooner and reduce the number of financial commitments you need to manage.
3. Improve Monthly Cash Flow
If you fully close your personal loan, you will no longer need to pay its regular EMIs after the closure takes effect. This can free up money for savings and other financial goals.
4. Simplify Financial Planning
Having fewer active loans can make budgeting easier and help you focus on building an emergency fund or working towards long-term goals.
Important: Prepayment does not automatically improve your credit score. Its effect depends on your overall credit history, account reporting and other credit-related factors.
Personal Loan Prepayment Charges
Some personal loans may have prepayment or foreclosure charges, depending on the loan terms and applicable rules. These charges can affect whether early repayment is financially beneficial.
Before prepaying, check:
-
Whether part-prepayment or full foreclosure is allowed.
-
Whether any lock-in period applies.
-
The applicable prepayment or foreclosure charges.
-
Whether taxes apply to those charges.
-
The outstanding principal and interest payable.
-
The lender's official foreclosure statement.
Do not assume that every lender charges the same fee or that all loans can be prepaid under identical conditions. Review your agreement and confirm the applicable requirements with your lender.
When Is Personal Loan Prepayment Worth It?
Prepayment may be worth considering when you have additional funds and can reduce your borrowing costs without affecting your financial security.
For example, suppose you receive a bonus at work. You could use part of it to reduce your outstanding personal loan balance, provided your lender permits prepayment and the potential interest savings exceed the associated costs.
However, avoid using all your savings to close a loan if doing so would leave you without money for essential expenses or emergencies.
Part-Prepayment vs Full Prepayment
| Feature | Part-Prepayment | Full Prepayment |
|---|---|---|
| Meaning | Repay part of the outstanding principal | Repay the entire outstanding loan |
| Loan status | Loan remains active | Loan closes after the lender completes the process |
| EMI impact | May reduce the EMI or tenure, depending on lender terms | Regular EMIs end after closure |
| Interest savings | May reduce future interest | May eliminate future interest on the repaid balance |
| Best consideration | Reducing debt while retaining regular repayments | Becoming debt-free earlier |
After part-prepayment, ask your lender whether the amount will reduce your EMI, shorten your tenure or be applied according to another contractual method.
How to Prepay a Personal Loan: Step-by-Step Guide
Step 1: Check Your Outstanding Loan Balance
Review your latest loan statement or contact your lender to confirm the outstanding principal and remaining tenure.
Step 2: Review the Loan Agreement
Check the rules for part-prepayment, foreclosure, minimum payment amounts, lock-in periods and applicable charges.
Step 3: Calculate Potential Savings
Compare the interest you may save against any prepayment fees and the cost of using your available funds.
Step 4: Request an Official Quote
Ask the lender for a prepayment calculation or foreclosure statement showing the amount payable and any applicable charges.
Step 5: Make the Payment Through an Official Channel
Use the lender's authorised payment method and retain the payment confirmation.
Step 6: Obtain Written Confirmation
For full prepayment, request confirmation that the loan has been closed. Keep the closure statement and check your credit report later to ensure the account status is updated correctly.
Common Mistakes to Avoid
-
Using your entire emergency fund to repay the loan.
-
Ignoring foreclosure charges or other applicable fees.
-
Assuming prepayment will automatically improve your credit score.
-
Paying without obtaining an official outstanding balance.
-
Sending money to an unauthorised agent or personal account.
-
Failing to obtain written confirmation after full repayment.
A careful review can help you avoid unnecessary expenses and repayment-related confusion.
Frequently Asked Questions
1. What is personal loan prepayment?
It is the repayment of part or all of a personal loan before the scheduled end of its tenure.
2. Does personal loan prepayment reduce interest?
It may reduce future interest because the outstanding principal is repaid earlier. Actual savings depend on the loan terms and applicable charges.
3. Can I prepay my personal loan after a few EMIs?
This depends on your lender's conditions, including any minimum tenure or lock-in period and applicable regulations.
4. Are personal loan prepayment charges mandatory?
Not for every loan. Charges depend on the applicable rules and the specific loan terms.
5. Is part-prepayment better than full prepayment?
It depends on your financial position. Part-prepayment can reduce debt while preserving some savings, whereas full prepayment can close the loan sooner.
6. Does prepayment improve my CIBIL score?
Not necessarily. Credit scores depend on multiple factors, including repayment history, outstanding debt and the information reported by lenders.
Conclusion
Personal loan prepayment can help reduce future interest costs and bring you closer to becoming debt-free. However, the decision should be based on your outstanding balance, potential interest savings, applicable charges and available savings.
Before making an early repayment, compare the financial benefits with the costs and ensure that you retain enough money for emergencies. At Vizzve, responsible borrowing means understanding your loan terms and choosing repayment options that support your long-term financial well-being.
Published on : 28th October 2026
Published by : Yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed