

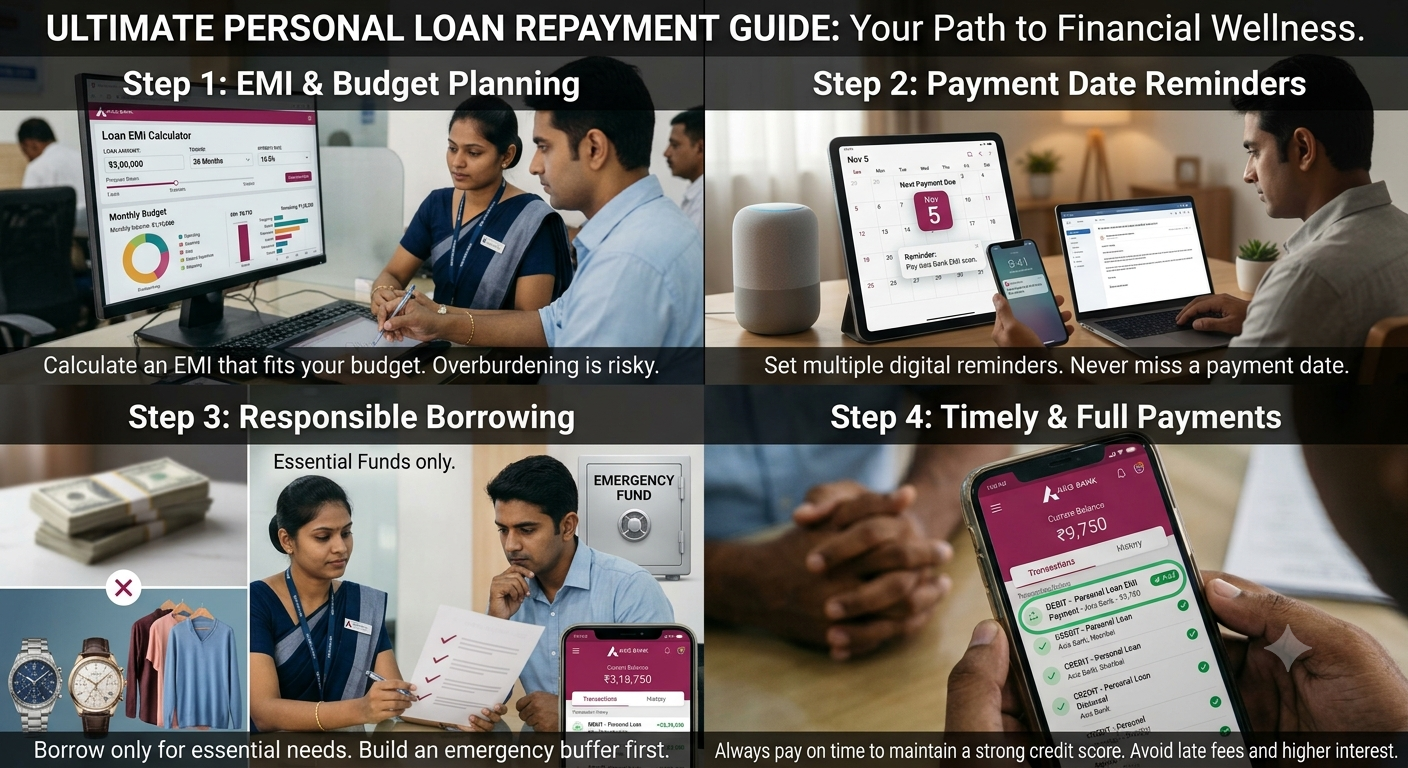
Personal loan repayment is the process of returning the borrowed amount to the lender, along with the applicable interest and charges, according to the agreed repayment schedule.
Most personal loans are repaid through Equated Monthly Instalments (EMIs). Each EMI generally includes a portion of the principal amount and interest, calculated according to the loan terms.
Your monthly EMI depends on factors such as:
-
The loan amount.
-
The applicable interest rate.
-
The repayment tenure.
-
The lender's repayment schedule and terms.
Before accepting a loan, review the EMI amount and ensure it fits comfortably within your monthly budget.
How Does Personal Loan Repayment Work?
The repayment process generally follows these steps.
1. Review Your Repayment Schedule
Check the loan agreement for the EMI amount, due date, tenure, interest rate and total repayment obligation.
2. Set Up a Repayment Method
Depending on the lender, you may be able to use an authorised automatic debit facility or another approved payment method.
3. Maintain Sufficient Bank Balance
Keep enough money in your designated account before the EMI due date if you use automatic debit. This can help prevent failed payments.
4. Pay EMIs on Time
Make repayments according to the agreed schedule. Late or missed payments may lead to additional charges and negatively affect your credit history.
5. Monitor Your Loan Balance
Review your loan statements and payment confirmations periodically to track outstanding principal and remaining instalments.
How to Manage Personal Loan EMIs Effectively
Good repayment planning can reduce financial stress and help you avoid unnecessary costs.
Create a monthly budget: Include your EMI alongside rent, groceries, utility bills, insurance and other financial commitments.
Choose an affordable tenure: A longer tenure may reduce the monthly EMI but can increase the total interest paid. A shorter tenure may increase the EMI while reducing the interest cost, depending on the loan terms.
Set payment reminders: Use calendar reminders or banking alerts to avoid forgetting due dates.
Build an emergency reserve: Where possible, maintain savings for unexpected expenses so that a temporary financial setback does not disrupt repayments.
Avoid excessive borrowing: Consider existing EMIs and essential expenses before taking another loan.
What Happens If You Miss a Personal Loan EMI?
Missing an EMI can have financial consequences. Depending on your loan agreement and applicable rules, you may face:
-
Late-payment or penal charges.
-
Additional interest where contractually and legally applicable.
-
Negative reporting to credit information companies.
-
Difficulty obtaining credit in the future.
If you expect difficulty making a payment, contact your lender through its official channels as early as possible. Ask whether any permitted repayment assistance or restructuring option is available. Do not ignore payment reminders or assume that a missed EMI will have no impact.
Can You Repay a Personal Loan Early?
Some lenders allow borrowers to make part-prepayments or close their loans before the scheduled end date. The availability of these options and any applicable charges depend on the loan terms and relevant regulations.
Before making an early repayment, check:
-
Whether part-prepayment or foreclosure is permitted.
-
Whether any charges apply.
-
How much interest you could save.
-
Whether sufficient emergency savings will remain after payment.
Request an updated outstanding balance or foreclosure statement from the lender before transferring funds. After full repayment, obtain confirmation of closure and retain the relevant records.
Personal Loan Repayment: Shorter vs Longer Tenure
| Factor | Shorter Tenure | Longer Tenure |
|---|---|---|
| Monthly EMI | Usually higher | Usually lower |
| Total interest | Often lower | Often higher |
| Repayment period | Shorter | Longer |
| Monthly budget pressure | May be greater | May be lower |
| Suitable for | Borrowers who can afford higher EMIs | Borrowers who need smaller monthly instalments |
The best tenure depends on your income, expenses, interest rate and repayment capacity. Compare the total repayment amount rather than choosing based only on the EMI.
Tips to Maintain a Healthy Credit Profile
Your repayment behaviour can influence your credit history and credit score. Follow these practical steps:
-
Pay every EMI by its due date.
-
Keep track of all active loans and credit card obligations.
-
Avoid taking new debt when your existing repayments are difficult to manage.
-
Review your credit report periodically for errors.
-
Check that closed loans are correctly reported after repayment.
Consistent repayment habits can support a stronger credit profile over time, although credit score changes depend on multiple factors.
Frequently Asked Questions
1. What is personal loan repayment?
It is the process of repaying the principal, interest and applicable charges according to the loan agreement.
2. Can I change my personal loan EMI date?
Some lenders may permit a due-date change, subject to their policies and approval. Contact your lender to confirm the available options.
3. Does missing an EMI affect my CIBIL score?
A missed or delayed payment may negatively affect your credit report and score, depending on reporting and other circumstances.
4. Is early personal loan repayment beneficial?
It may reduce future interest costs, but any applicable prepayment charges and the remaining loan terms should be considered.
5. What should I do if I cannot afford my EMI?
Contact your lender promptly to discuss possible options. Avoid taking another high-cost loan without evaluating whether you can afford the additional repayment.
6. How can I avoid missing EMI payments?
Set reminders, maintain sufficient funds before the due date and monitor payment confirmations regularly.
Conclusion
Personal loan repayment is an important part of responsible borrowing. By selecting an affordable EMI, maintaining a realistic budget, paying on time and understanding early repayment conditions, borrowers can manage their financial commitments more effectively.
Published on : 28th October 2026
Published by : Yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed