

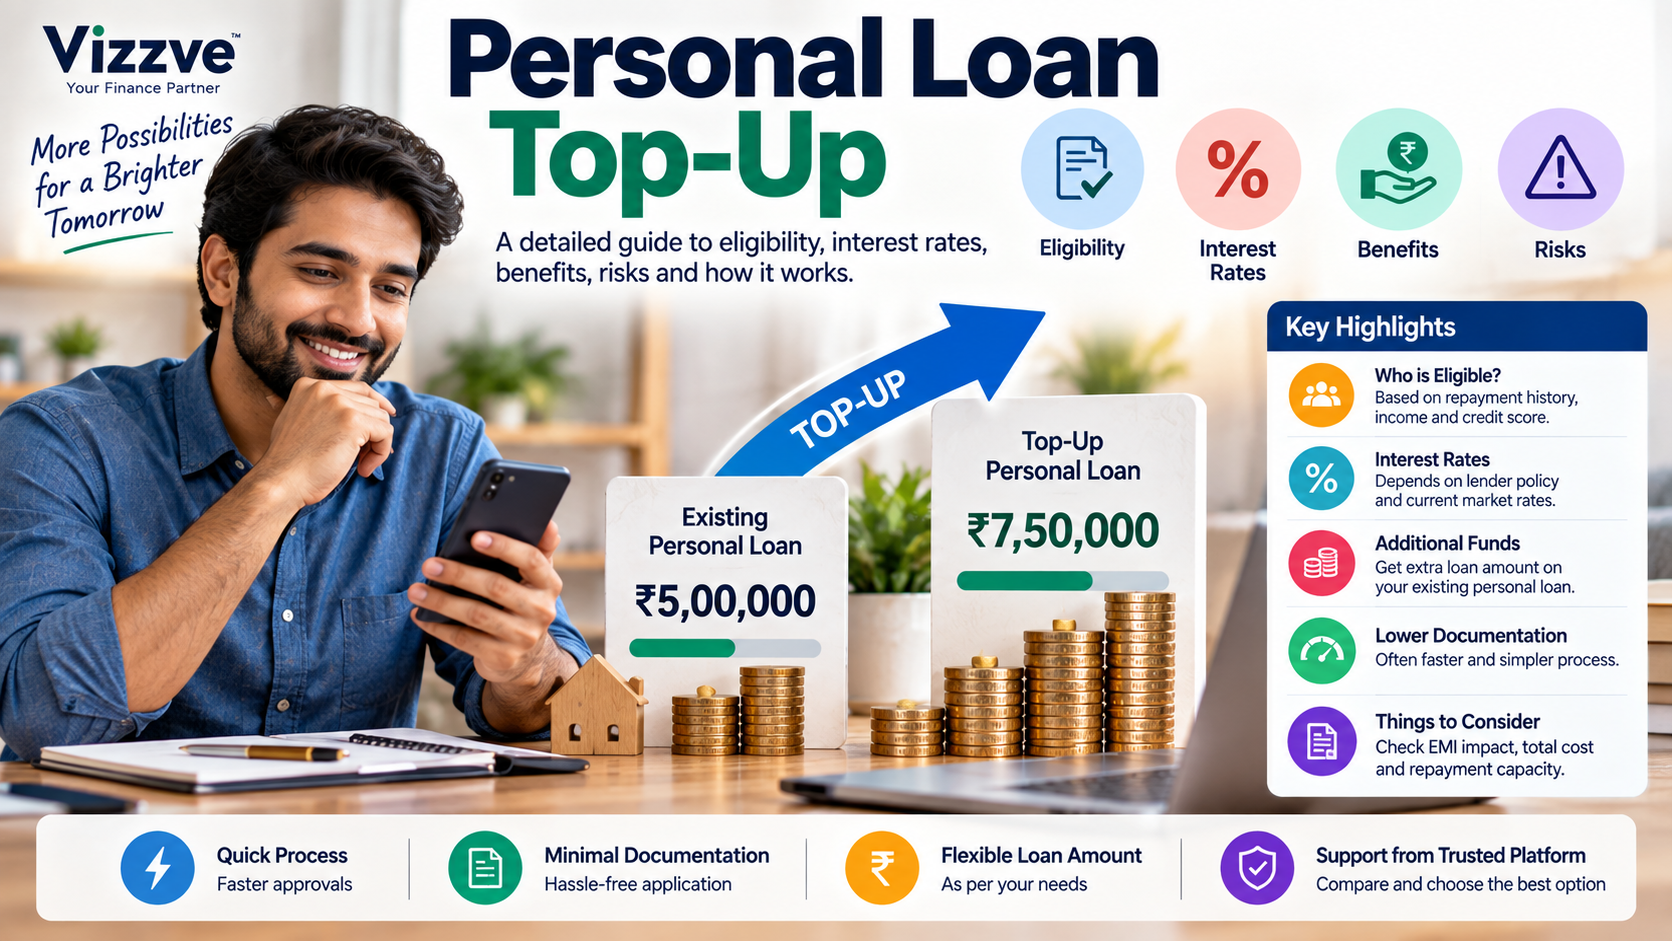
A personal loan top-up allows an existing borrower to access additional funds from a lender while continuing with an existing personal-loan relationship. Instead of applying for an entirely separate loan, the borrower may receive additional credit subject to the lender's eligibility rules, repayment history, income, outstanding balance and credit profile.
Top-up loans can be useful when a borrower needs additional money for an urgent expense, education, medical needs, home improvement, debt consolidation or another legitimate financial requirement.
However, a top-up is still new borrowing. A lower monthly EMI does not necessarily mean a lower overall cost. Borrowers should compare the interest rate, processing fees, remaining tenure, revised EMI and total repayment before accepting an offer.
There is also a wider funding-cost issue to understand. When lenders face higher funding costs, the economics of new lending can change. Higher borrowing costs for a lender can put pressure on its net interest margin (NIM) and may influence the pricing of fresh loans or top-up facilities.
As of July 2026, the RBI's published policy-rate data showed a 5.25% policy repo rate, with the Standing Deposit Facility at 5.00% and Marginal Standing Facility at 5.50%.
A personal loan top-up is an additional amount offered to an existing personal-loan borrower by the same lender, subject to eligibility and credit assessment.
The lender generally considers:
- Existing repayment history
- Outstanding loan balance
- Credit score and credit profile
- Current income
- Existing EMI obligations
- Debt-to-income or repayment capacity
- Employment or business stability
- Internal lender policy
- Current funding and credit conditions
A top-up may be convenient because the borrower already has an established relationship with the lender. But borrowers should compare the total cost of the top-up, not just the additional cash received.
What Is a Personal Loan Top-Up?
A personal loan top-up is an additional borrowing facility linked to an existing personal loan.
For example, suppose a borrower originally takes a ₹5 lakh personal loan. After making regular repayments for some time, the borrower needs another ₹1.5 lakh.
Instead of applying for an entirely separate personal loan, the existing lender may offer a top-up of ₹1.5 lakh.
The actual amount depends on the lender's assessment.
Simple Example
| Particular | Existing Loan | Top-Up |
|---|---|---|
| Original loan | ₹5,00,000 | — |
| Amount already repaid | ₹1,50,000 | — |
| Outstanding principal | ₹3,50,000 | — |
| Additional requirement | — | ₹1,50,000 |
| Potential additional borrowing | — | ₹1,50,000 |
The figures above are illustrative. Actual offers depend on lender policy and borrower eligibility.
How Does a Personal Loan Top-Up Work?
The process is generally straightforward.
Step 1: Existing loan relationship
The borrower must normally have an active personal loan with the lender.
Step 2: Repayment history is reviewed
The lender may examine whether EMIs have been paid on time.
A consistent repayment history can be an important part of the lender's assessment.
Step 3: Financial profile is assessed
The lender may review:
- Income
- Existing liabilities
- Credit history
- Employment/business profile
- Current EMI burden
- Outstanding loan balance
Step 4: Top-up amount is determined
The lender may determine an eligible additional amount based on its internal credit policy.
Step 5: Offer and pricing
The borrower receives details such as:
- Top-up amount
- Interest rate
- Tenure
- EMI
- Processing fee
- Other applicable charges
- Total repayment amount
Step 6: Acceptance and disbursal
After the borrower accepts the applicable terms and completes required formalities, the lender processes the facility.
Why Do Borrowers Choose a Personal Loan Top-Up?
A top-up can offer convenience because the borrower already has an established relationship with the lender.
Common reasons include:
- Medical expenses
- Education expenses
- Home renovation
- Wedding expenses
- Emergency financial requirements
- Business-related personal funding needs
- Debt consolidation
- Large planned purchases
However, borrowing should be based on repayment capacity rather than urgency alone.
Personal Loan Top-Up vs New Personal Loan
One of the most important decisions is whether to take a top-up or apply for a completely new personal loan.
| Factor | Personal Loan Top-Up | New Personal Loan |
|---|---|---|
| Existing lender relationship | Usually required | Not required |
| Application process | May be simpler | New application |
| Documentation | May be reduced | Usually full documentation |
| Credit assessment | Still applicable | Full assessment |
| Interest rate | Depends on lender | Depends on lender |
| Additional borrowing | Linked to existing relationship | Separate facility |
| Comparison shopping | May be limited | Easier across lenders |
| Convenience | Potentially higher | Depends on lender |
| Total cost | Must be calculated | Must be calculated |
Important: A top-up is not automatically cheaper than a new personal loan. Compare the complete cost before accepting an offer.
What Determines Personal Loan Top-Up Eligibility?
There is no single universal eligibility formula.
Each lender can apply its own underwriting standards.
Major factors include:
1. Repayment history
Timely EMI payments can strengthen the borrower's profile.
Repeated missed payments can make additional borrowing more difficult or expensive.
2. Credit profile
Credit history helps lenders assess repayment behaviour.
3. Income
Higher and stable income can support greater repayment capacity, although income alone does not guarantee approval.
4. Existing obligations
A borrower already paying multiple EMIs may have limited capacity for additional debt.
5. Outstanding loan balance
The remaining balance on the existing personal loan can influence the lender's assessment.
6. Employment stability
Lenders may consider the stability and consistency of income.
7. Internal lender policy
Existing customers may receive different offers depending on the lender's credit model and relationship history.
What Documents Are Required for a Top-Up Loan?
Documentation varies by lender and borrower profile.
Potential requirements include:
- PAN card
- Aadhaar or other identity/address documents
- Salary slips
- Bank statements
- Income documents
- Employment details
- Existing loan information
- Additional KYC documents where required
Existing customers may sometimes have a simpler documentation process because the lender already holds information about the borrower.
Personal Loan Top-Up Interest Rates
The interest rate is one of the most important factors when evaluating a top-up.
The rate can depend on:
- Credit profile
- Income
- Loan amount
- Existing repayment history
- Tenure
- Lender's pricing policy
- Market conditions
- Funding costs
- Risk assessment
For NBFCs, RBI guidance states that interest-rate models take factors such as cost of funds, margin and risk premium into account, with the applicable rate and risk-grading approach communicated to borrowers.
This means changes in a lender's funding environment can become relevant to loan pricing.
How Higher Funding Costs Can Affect Personal Loan Top-Ups
This is where the broader funding pressures issue becomes important.
Financial institutions raise money through multiple channels, including:
- Bank borrowings
- Bonds and debentures
- Commercial paper
- Deposits, where permitted
- Securitisation
- Other market-based funding
If the cost of these sources rises, the lender's overall cost of funds can increase.
The basic chain is:
Higher market/policy rates → Higher funding costs → Margin pressure → Loan pricing pressure
The effect will not necessarily be identical across every lender.
Some institutions have diversified funding sources, strong liquidity or longer-duration liabilities that may reduce the speed at which higher market rates affect their average funding cost.
What Is NIM and Why Does It Matter?
NIM means Net Interest Margin.
For a lender, it broadly measures the spread between interest earned on assets and interest paid on funding, relative to interest-earning assets.
A simplified illustration:
NIM ≈ Interest income yield − Cost of interest-bearing funds
For example:
| Scenario | Lending Yield | Funding Cost | Illustrative Spread |
|---|---|---|---|
| Scenario A | 15% | 8% | 7% |
| Scenario B | 15% | 9% | 6% |
| Scenario C | 15% | 10% | 5% |
If lending yields remain unchanged while funding costs rise, the spread can narrow.
This is why analysts monitor NIM when assessing financial institutions.
Why Higher Funding Costs Matter for Borrowers
A lender facing higher funding costs may have several options.
It could:
- Absorb some of the additional cost.
- Improve operational efficiency.
- Reprice new loans.
- Adjust credit-risk pricing.
- Change product mix.
- Seek alternative funding sources.
- Reduce the pace of certain loan growth.
The actual response depends on the institution's balance sheet, competition and pricing strategy.
Therefore, borrowers should not assume that every increase in central-bank or market rates will immediately translate into the same increase in their personal-loan rate.
India's NBFC Funding Environment
India's NBFC sector continues to expand, creating substantial funding requirements.
ICRA estimated that NBFC-Retail AUM, excluding HFCs, could grow 18–20% year-on-year in FY2027. It also projected credit costs of around 2.1–2.3% during FY2027 and highlighted macroeconomic risks.
Earlier, ICRA estimated that NBFC-Retail would require approximately ₹4.1–₹4.3 trillion of incremental funding in FY2027, excluding refinancing of maturing debt.
These numbers illustrate why access to reasonably priced funding is strategically important for lenders.
Securitisation as an Alternative Funding Channel
Securitisation has also become an important funding mechanism for non-bank lenders.
ICRA reported that securitisation volumes reached approximately ₹61,000 crore in Q1 FY2027, an increase of around 19% year-on-year. NBFCs and HFCs recorded approximately 27% growth over Q1 FY2026, with smaller entities increasingly adopting securitisation as a funding tool.
This illustrates an important point:
NBFC funding is not dependent on a single source of capital.
Diversification can help lenders manage changing market conditions, although every funding source has its own cost and risk characteristics.
Personal Loan Top-Up: Advantages
Potential Benefits
- Convenient for existing borrowers
- May require less documentation
- Can provide additional funds without starting an entirely separate relationship
- Potentially faster processing
- Useful for planned or emergency expenses
- Existing repayment history may be considered
- Can simplify loan management
Personal Loan Top-Up: Disadvantages
Potential Risks
- Adds to total debt
- Increases overall interest outgo
- May extend the repayment period
- Processing fees may apply
- Interest rates can vary between lenders
- Easy access can encourage excessive borrowing
- Consolidating debt without changing spending habits may not solve the underlying problem
Pros and Cons at a Glance
| Pros | Cons |
|---|---|
| Convenient | Additional debt |
| Potentially faster processing | More interest payable |
| Existing relationship | Fees may apply |
| May require fewer documents | Could increase EMI |
| Useful for genuine financial needs | Can extend repayment burden |
| Simple loan management | Not always the cheapest option |
How to Calculate the Real Cost of a Top-Up
Do not focus only on the EMI.
Consider:
Total repayment = Total principal + Total interest + applicable charges
For example, imagine a borrower receives a ₹2 lakh top-up.
If the interest rate is 14% and the tenure is three years, the EMI will depend on the lender's repayment structure.
The borrower should compare:
- Principal received
- Interest rate
- Monthly EMI
- Number of EMIs
- Processing fee
- GST on applicable charges
- Prepayment terms
- Total repayment
The lowest EMI may not produce the lowest total cost.
Step-by-Step Guide Before Accepting a Top-Up
Step 1: Identify the exact financial need
Ask:
How much money do I actually need?
Avoid borrowing more simply because the lender offers a larger amount.
Step 2: Check your existing loan
Review:
- Outstanding principal
- Current interest rate
- Remaining tenure
- Current EMI
- Repayment history
Step 3: Check your credit profile
Review your credit report for errors and understand your current debt obligations.
Step 4: Compare the top-up offer
Look at the complete cost rather than the headline interest rate.
Step 5: Calculate the new EMI
Make sure the revised monthly obligation fits comfortably within your income.
Step 6: Read the Key Facts Statement
For applicable retail and MSME term loans, RBI's framework requires a standardized Key Facts Statement containing important loan information and the overall cost structure.
Step 7: Check fees and conditions
Review:
- Processing fees
- Late-payment charges
- Prepayment/foreclosure conditions
- Insurance, if applicable
- Other applicable charges
Step 8: Borrow only what you can repay
A top-up should strengthen financial flexibility rather than create an unsustainable EMI burden.
What Borrowers Should Check in a Top-Up Offer
| Checkpoint | Why It Matters |
|---|---|
| Interest rate | Determines borrowing cost |
| APR/overall cost | Gives a broader cost picture |
| Processing fee | Raises effective borrowing cost |
| Tenure | Longer tenure can increase total interest |
| EMI | Determines monthly affordability |
| Total repayment | Shows overall cash outflow |
| Prepayment rules | Important if you expect early repayment |
| Late charges | Helps avoid unexpected costs |
| Reset mechanism | Important for floating-rate loans |
| Lender identity | Confirms who is actually providing the loan |
Floating Interest Rates and Personal Loans
Borrowers should understand whether their loan has a fixed or floating rate.
RBI's framework on EMI-based floating-rate personal loans requires regulated entities to communicate the impact of benchmark-rate changes and applicable options when rates change. RBI guidance also refers to disclosure of the annualized rate/APR and relevant loan information in the Key Facts Statement.
For a borrower, this means it is important to understand:
- What benchmark affects the rate?
- When can the rate reset?
- Can EMI change?
- Can tenure change?
- How will changes be communicated?
Is a Personal Loan Top-Up Better Than Taking a New Loan?
There is no universal answer.
The right comparison depends on the borrower's individual numbers.
Compare these five things:
- Interest rate
- Total repayment
- Processing charges
- EMI affordability
- Remaining tenure
A borrower should choose based on the overall cost and repayment capacity, not simply the convenience of an existing relationship.
Real-World Financial Planning Example
Consider a borrower who already has an EMI of ₹12,000 per month and is offered a top-up that would increase the total monthly obligation to ₹17,000.
Before accepting it, the borrower should ask:
- Is monthly income stable?
- Are rent and household expenses rising?
- Are there other outstanding loans?
- Is there an emergency fund?
- Can the additional ₹5,000 EMI be maintained even during a temporary income disruption?
This is the practical side of responsible borrowing.
A lender may approve a loan, but the borrower still needs to determine whether the repayment fits the household budget.
Expert Commentary: Why Funding Costs Matter
From a lending-business perspective, the key issue is the relationship between asset yields, funding costs, operating expenses and credit losses.
If funding costs rise while loan yields remain unchanged, NIM can come under pressure. If lenders increase loan pricing to compensate, borrowers may face higher borrowing costs.
However, the transmission is not automatic or uniform.
A lender with diversified liabilities, strong liquidity, efficient operations and stable credit performance can have a different cost structure from another lender with greater dependence on short-term or market-sensitive funding.
This is why borrowers and investors should look beyond a single headline interest-rate number.
Key Takeaways
- A personal loan top-up provides additional borrowing to an existing borrower.
- Eligibility depends on lender policy, repayment history, income and credit profile.
- A top-up is not automatically cheaper than a new personal loan.
- Always compare total repayment, not just EMI.
- Higher lender funding costs can put pressure on NIM.
- Funding conditions can influence the pricing of new loans and top-ups.
- RBI's framework emphasizes transparency around loan pricing and key loan information.
- ICRA expects continued NBFC-Retail growth, which also implies significant funding requirements.
- Securitisation is becoming an increasingly important funding route for NBFCs and HFCs.
- Borrow only an amount that comfortably fits your repayment capacity.
Frequently Asked Questions
1. What is a personal loan top-up?
A personal loan top-up is additional borrowing offered to an existing personal-loan customer, subject to the lender's eligibility and credit assessment.
2. Can I get a top-up on an existing personal loan?
Potentially, yes. The lender may consider your repayment history, outstanding balance, income, credit profile and internal eligibility criteria.
3. Is a personal loan top-up the same as a new loan?
Not necessarily. A top-up is generally linked to an existing loan relationship, while a new personal loan is a separate application and facility.
4. Is a top-up loan cheaper than a personal loan?
Not automatically. Compare the interest rate, fees, tenure and total repayment before making a decision.
5. Does a top-up increase my EMI?
It can. Depending on how the facility is structured, your total monthly repayment may increase.
6. Can a top-up extend my loan tenure?
It may, depending on the lender's terms and how the additional borrowing is structured.
7. What documents are needed for a personal loan top-up?
Requirements vary. The lender may request KYC documents, income proof, bank statements and other information depending on the borrower profile.
8. Does credit score matter for a top-up?
Yes. Credit history can form part of the lender's assessment, although each lender uses its own underwriting criteria.
9. Why do lenders care about funding costs?
Funding is a major component of a lender's cost structure. When funding becomes more expensive, it can put pressure on margins if loan yields do not adjust at the same pace.
10. What is NIM in banking and NBFCs?
NIM, or Net Interest Margin, broadly measures the difference between interest earned on lending assets and interest paid on funding relative to interest-earning assets.
11. Can higher interest rates affect personal loan top-ups?
They can influence lending economics and pricing, although the impact depends on the lender's funding mix, pricing policy and competitive environment.
12. Should I take the maximum top-up amount offered?
Not necessarily. Borrow only what you genuinely need and can comfortably repay.
13. What is more important: EMI or total repayment?
Both matter, but total repayment shows the broader financial cost. A lower EMI achieved through a longer tenure can result in higher overall interest.
14. What should I check before accepting a top-up?
Check the interest rate, APR/overall cost, EMI, tenure, processing fees, prepayment terms, late-payment charges and total repayment.
15. Where can I compare loan options?
Borrowers can explore available loan options through platforms that connect customers with lending partners, while independently reviewing the final lender's terms before accepting an offer.
Internal Linking Suggestions
For a finance website, consider linking this article to:
- Personal Loan Eligibility Guide
- Personal Loan EMI Calculator
- How to Improve Your Credit Score
- Personal Loan Interest Rates in India
- Emergency Loan Options in India
- How to Reduce Personal Loan Interest
- Loan Against Property vs Personal Loan
- Debt Consolidation Guide
- How to Build an Emergency Fund
- Responsible Borrowing Guide
External Linking Suggestions
Use authoritative sources for supporting information:
- Reserve Bank of India — policy rates, lending regulations and borrower-protection guidance.
- ICRA Research — NBFC sector, funding and securitisation research.
- Vizzve Financial — loan comparison and application platform.
Published on : 24th september
Published by : Shanlee JV
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed