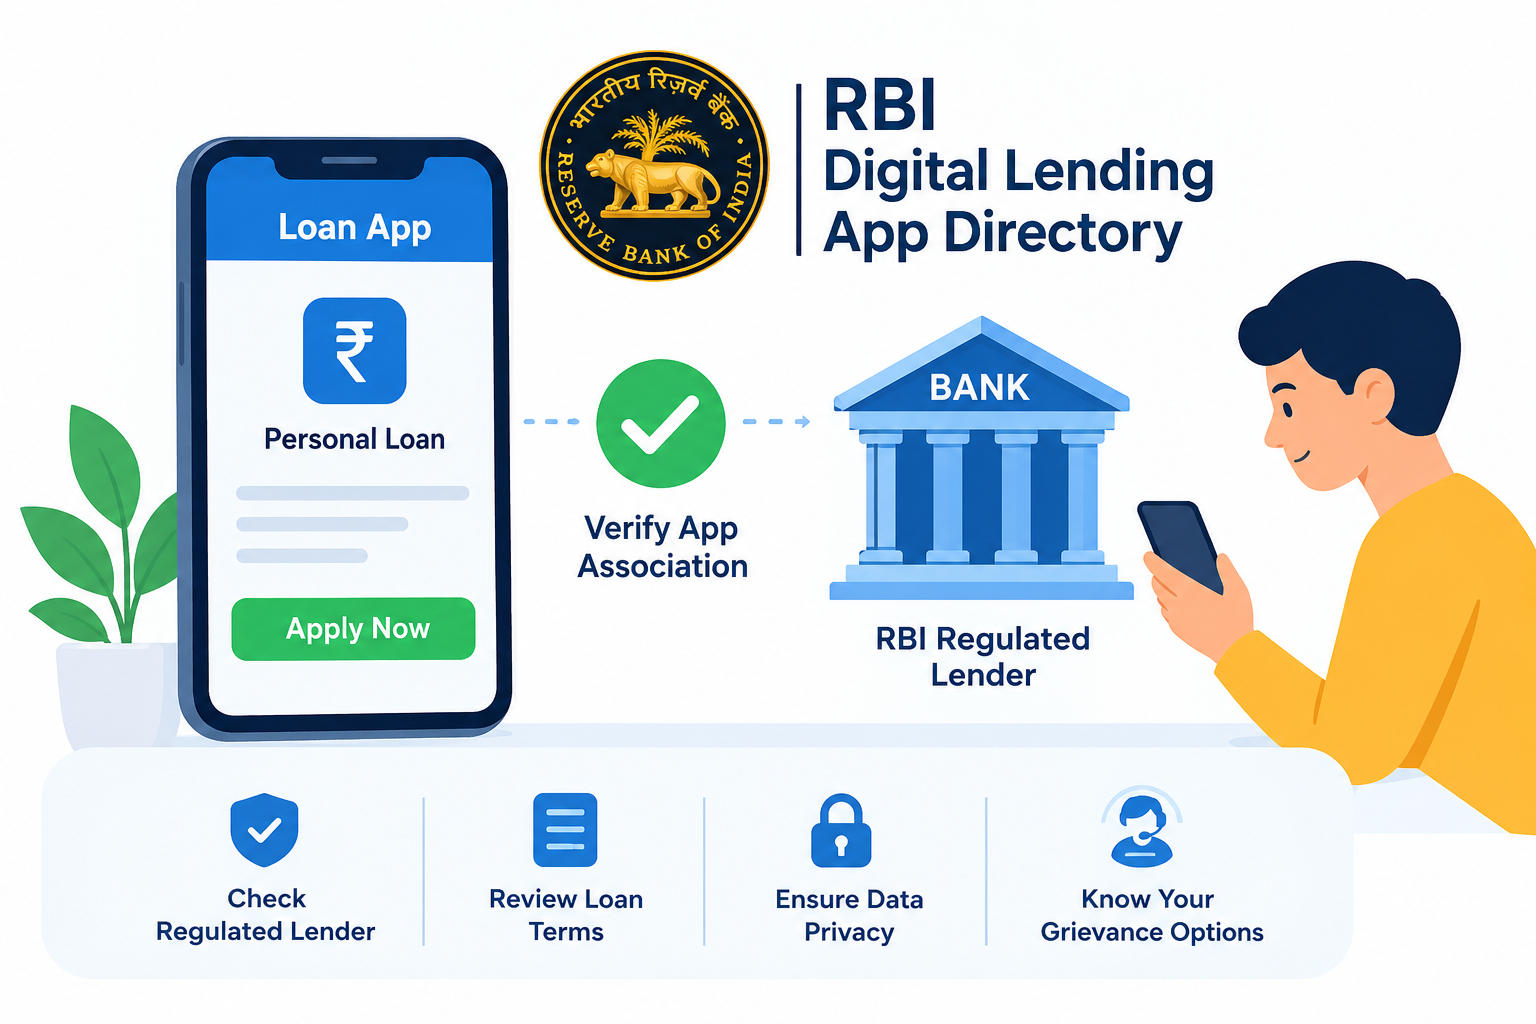
RBI Digital Lending App Directory
Vizzve Admin
Introduction
The RBI Digital Lending App Directory is an important tool for borrowers who use mobile apps to access loans in India. The Reserve Bank of India (RBI) operationalised its public directory of Digital Lending Apps (DLAs) on July 1, 2025. The directory is designed to help customers verify whether a digital lending app claims an association with a bank or other RBI-regulated entity.
The directory is particularly useful because borrowers may encounter loan apps offering quick approvals, instant disbursals and minimal documentation. Checking the app's association with a regulated entity before borrowing can provide an additional verification step.
What Is the RBI Digital Lending App Directory?
The RBI Digital Lending App Directory is a public listing of digital lending apps deployed by RBI-regulated entities (REs).
It helps borrowers check the association claimed by a digital lending app with a regulated entity. RBI has clarified that the information in the directory is based on data submitted by regulated entities and is made available on an “as is” basis, without further validation by RBI. The directory can also be updated when regulated entities add or remove apps.
Why Was the Directory Introduced?
The directory was introduced as part of measures to improve transparency and consumer protection in digital lending.
Key objectives include:
- Helping borrowers verify an app's claimed association with an RBI-regulated entity
- Improving transparency in digital lending
- Supporting customers in identifying potentially unauthorised loan apps
- Strengthening consumer awareness
- Reducing risks associated with fraudulent digital lending platforms
The Government stated in March 2026 that the directory has been operational since July 1, 2025.
How to Check a Loan App in the RBI DLA Directory
Borrowers can use the RBI website's “DLAs deployed by Regulated Entities” directory to verify an app.
Step 1: Identify the Loan App
Note the exact name of the mobile application or digital lending platform.
Step 2: Find the App in the RBI Directory
Search for the app in RBI's published DLA directory.
Step 3: Check the Associated Regulated Entity
Look at the bank, NBFC or other RBI-regulated entity associated with the app.
Step 4: Match the Information
Compare the information shown in the RBI directory with the information provided by the loan app, including the lender's name.
Step 5: Review the Loan Terms
Even when an app appears in the directory, borrowers should review:
- Interest rate
- Annual Percentage Rate (APR)
- Processing fees
- Penal charges
- Repayment schedule
- Key Fact Statement
- Privacy policy
- Grievance-redressal details
Is an App on the RBI Directory Automatically Safe?
Not necessarily.
The directory is primarily intended to help customers verify an app's claimed association with a regulated entity. RBI has stated that the data is submitted by regulated entities and published on an as-is basis without further validation by the Reserve Bank.
Therefore, borrowers should not treat directory presence as a substitute for reading the loan agreement or checking the lender's terms.
What Information Should Borrowers Check?
| Information |
Why It Matters |
| App name |
Confirms the identity of the application |
| Regulated entity |
Identifies the bank/NBFC associated with lending |
| APR |
Helps understand the overall cost of borrowing |
| Fees and charges |
Shows additional borrowing costs |
| Repayment schedule |
Helps plan EMI payments |
| Privacy policy |
Explains how personal information is handled |
| Grievance mechanism |
Provides a route for complaints |
| Key Fact Statement |
Summarises important loan terms |
RBI's digital lending framework includes requirements relating to transparency, data collection, privacy and disclosure of the overall cost of credit.
RBI Digital Lending Apps and Borrower Safety
Borrowers should be particularly careful with apps that:
- Promise loans without proper documentation
- Ask for unnecessary access to contacts or personal data
- Hide the identity of the actual lender
- Demand unusual upfront payments
- Use threatening recovery practices
- Do not clearly explain interest rates and fees
- Provide no clear grievance-redressal mechanism
RBI has previously cautioned the public about unauthorised digital lending platforms and advised customers to verify the credentials of entities offering loans through apps.
What If a Loan App Is Not Found in the Directory?
If an app cannot be found, borrowers should not automatically assume that it is fraudulent. However, they should pause before sharing sensitive information or accepting a loan.
Check:
- The actual lender's name.
- Whether the lender is an RBI-regulated entity.
- Whether the lender confirms its association with the app.
- The loan agreement and Key Fact Statement.
- The app's privacy and grievance policies.
For personal loan apps, Google Play's current India policy also requires apps to be on the RBI's DLA list before they can submit such apps for review.
How the RBI DLA Directory Differs From a Loan App Rating
The RBI directory should not be interpreted as a rating or endorsement of loan apps.
Its primary purpose is verification of an app's claimed association with a regulated entity. RBI's own description specifically says the directory is intended to help customers verify such associations.
What Borrowers Should Do Before Taking a Digital Loan
A simple checklist can help:
- Verify the app through the RBI DLA directory.
- Identify the actual regulated lender.
- Read the Key Fact Statement.
- Check the APR and total repayment amount.
- Understand all fees and charges.
- Review the privacy policy.
- Avoid unnecessary permissions.
- Keep copies of loan documents and payment receipts.
- Use official complaint channels if a dispute arises.
What to Do If You Encounter a Fraudulent Loan App
The Government has highlighted the National Cybercrime Reporting Portal and helpline 1930 for reporting cyber incidents, including illegal loan apps.
If money has been lost through suspected digital fraud, prompt reporting can help create an official record and facilitate appropriate action.
RBI Digital Lending App Directory: Key Takeaways
- The RBI DLA Directory became operational on July 1, 2025.
- It lists digital lending apps deployed by RBI-regulated entities.
- Its main purpose is to help customers verify an app's claimed association with a regulated entity.
- RBI publishes the submitted information on an as-is basis.
- Directory presence should not replace careful review of loan terms.
- Borrowers should check the lender, APR, fees, privacy policy and grievance mechanism before accepting a loan.
- Suspected cyber fraud can be reported through the National Cybercrime Reporting Portal or 1930.
Frequently Asked Questions
1. What is the RBI Digital Lending App Directory?
It is a public RBI directory containing digital lending apps deployed by RBI-regulated entities.
2. When did the RBI DLA Directory become operational?
The directory became operational on July 1, 2025.
3. Why should I check a loan app in the RBI directory?
It can help you verify whether the app claims an association with an RBI-regulated entity.
4. Does RBI approve every app listed in the directory?
The directory is based on information submitted by regulated entities. RBI has stated that the information is published on an as-is basis without further validation by the Reserve Bank.
5. Is an RBI-listed app automatically safe?
No. Borrowers should still review the lender, loan terms, charges, privacy policy and grievance mechanism.
6. What is a DLA?
DLA stands for Digital Lending App.
7. What should I check before taking an online loan?
Check the lender's identity, APR, fees, repayment terms, Key Fact Statement, privacy policy and complaint mechanism.
8. What if a loan app is not listed?
Verify the actual lender independently before providing personal information or accepting a loan.
9. Can digital lending apps collect personal data?
Digital lending rules include requirements concerning need-based data collection, explicit consent and privacy practices.
10. Where can I report cyber fraud involving a loan app?
Cyber incidents can be reported through the National Cybercrime Reporting Portal or by calling 1930.
11. What is the difference between a DLA and an LSP?
A DLA is the digital application or interface used for lending-related services, while an LSP can provide technology or other services to a regulated lender in the lending process.
12. Should I compare only the interest rate?
No. Consider the APR, processing charges, other fees, repayment schedule and total cost of the loan.
13. Why is the regulated lender important?
The regulated lender is the entity responsible for the lending relationship and relevant regulatory obligations.
14. Can the RBI directory change?
Yes. RBI has stated that the list can be updated when regulated entities add or delete DLA information.
15. Is the RBI DLA Directory useful for preventing fraudulent loan apps?
It provides an additional verification mechanism, but borrowers should also independently examine the lender and loan documentation.
Conclusion
The RBI Digital Lending App Directory provides borrowers with a useful way to verify the association between a digital lending app and an RBI-regulated entity. However, checking an app in the directory should be only one part of the borrowing process.
Before taking a digital loan, borrowers should verify the lender, review the Key Fact Statement, compare the APR and charges, understand the repayment terms, and check the app’s privacy and grievance-redressal practices. Taking these precautions can help borrowers make informed decisions and reduce the risks associated with unauthorised or misleading digital lending platforms.
By using the RBI DLA Directory along with careful financial checks, borrowers can approach digital loans with greater awareness and caution.
Published on : 1st October
Published by :MONISHA
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed
Disclaimer: This article may include third-party images, videos, or content that belong to their respective owners. Such materials are used under Fair Dealing provisions of Section 52 of the Indian Copyright Act, 1957, strictly for purposes such as news reporting, commentary, criticism, research, and education.
Vizzve and India Dhan do not claim ownership of any third-party content, and no copyright infringement is intended. All proprietary rights remain with the original owners.
Additionally, no monetary compensation has been paid or will be paid for such usage.
If you are a copyright holder and believe your work has been used without appropriate credit or authorization, please contact us at grievance@vizzve.com. We will review your concern and take prompt corrective action in good faith... Read more

