

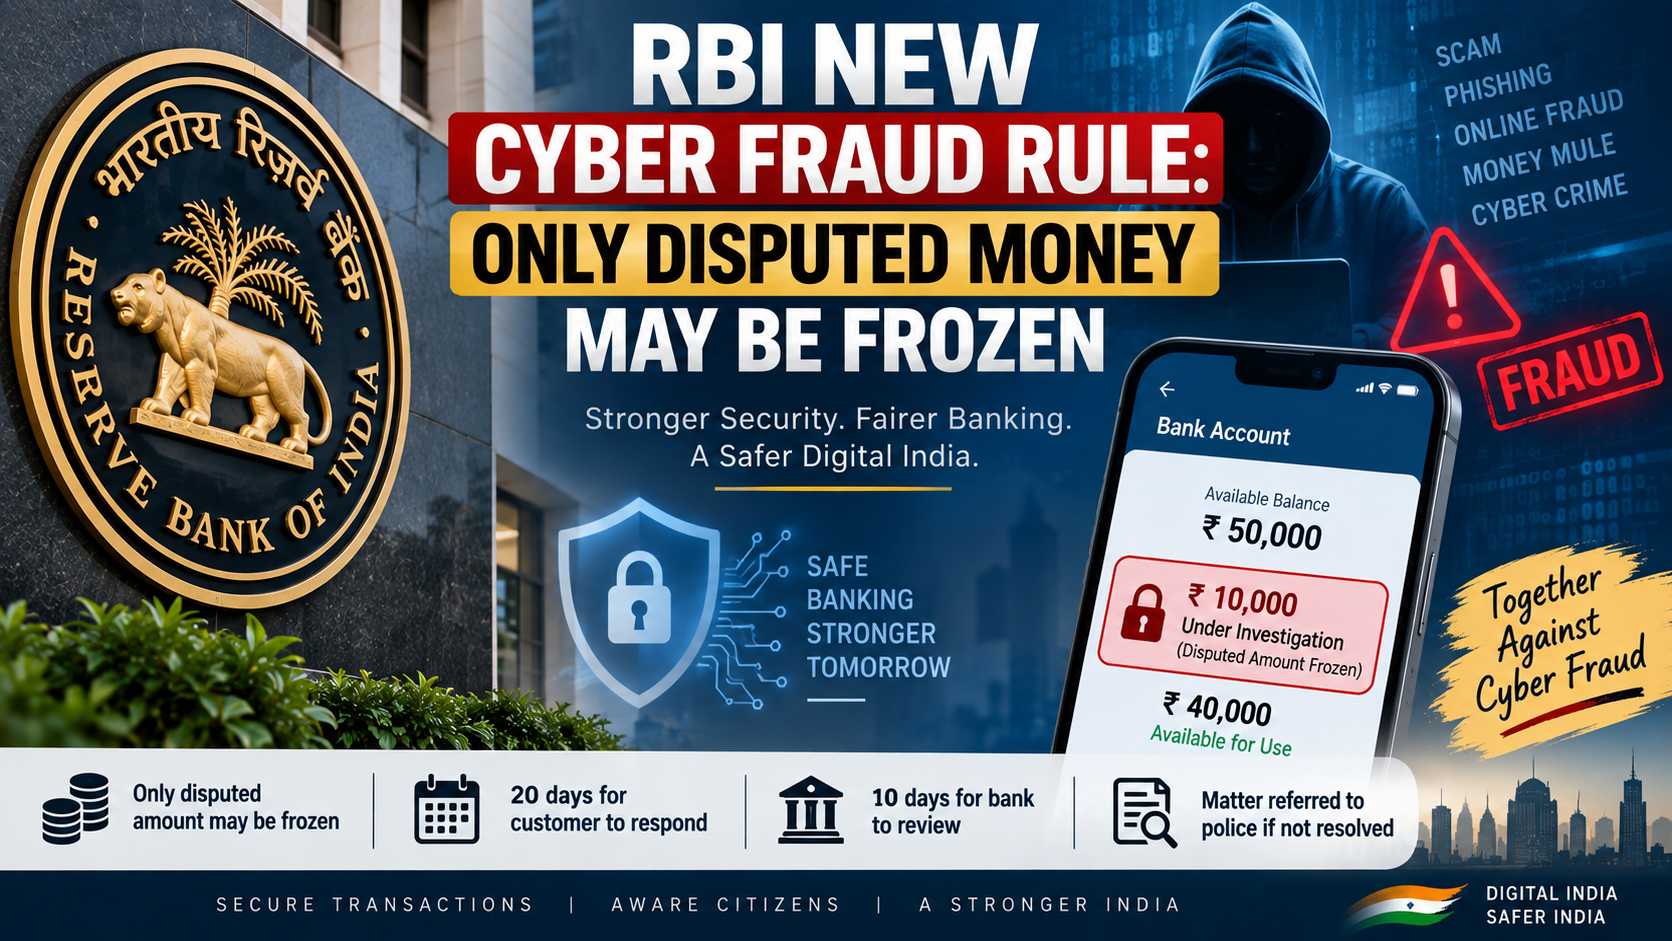
The Reserve Bank of India (RBI) has proposed a new framework that could significantly change how banks handle accounts linked to cyber fraud and money-mule activity.
Under the proposed system, banks would generally place a temporary hold on the specific disputed amount, instead of automatically freezing the customer's entire bank account. The move is aimed at protecting genuine customers whose accounts may be connected to a suspicious transaction without blocking access to their legitimate money.
The proposal comes after the Supreme Court's August 4, 2026 direction asking RBI to prescribe a Standard Operating Procedure for temporary debit holds involving money-mule activity and cyber-enabled fraud.
What Is RBI's New Cyber Fraud Proposal?
The proposed RBI framework focuses on making bank-account restrictions more targeted.
If an unusual transaction of ₹1,000 or more is flagged as potentially connected to cyber fraud or a money-mule account, the bank would temporarily hold the amount under investigation rather than automatically blocking the entire account.
This is important because an account may contain both legitimate money and a relatively small amount that is under investigation.
For example, if ₹5,000 is suspected to be linked to a cyber-fraud transaction but the account contains ₹2 lakh of legitimate funds, the proposed approach would focus on the disputed ₹5,000 rather than automatically blocking the entire ₹2 lakh.
Why Is This Change Important?
In recent years, people have faced situations where their entire bank account was frozen after a suspicious or disputed transaction appeared in their account.
This can create serious problems for genuine account holders. Salary payments, household expenses, business payments, EMIs and other important transactions may be affected when access to an entire account is restricted.
Several High Courts have also raised concerns about blanket account freezes in cybercrime cases. The Rajasthan High Court, for example, said that where the disputed amount is identifiable, the ordinary approach should be to preserve that amount rather than freeze the entire account, unless there are reasons for a wider restraint.
The proposed RBI framework moves in a similar direction by encouraging a more targeted approach.
How Will the New Process Work?
The proposed framework sets out a process for banks and customers.
Step 1: Suspicious Transaction Is Identified
Banks would use AI-based transaction monitoring systems to identify unusual transactions. These may include transfers that are sudden, disproportionate to a customer's declared profile or connected with known cyber-fraud networks.
Step 2: Only the Disputed Amount May Be Held
Instead of automatically freezing the complete account, the bank would temporarily restrict the amount suspected to be connected with the cyber-fraud transaction.
This means the customer's remaining legitimate balance could generally continue to be used, subject to applicable legal restrictions.
Step 3: Customer Gets 20 Days
Under the proposal, the account holder would get 20 calendar days to explain the transaction and establish its legitimacy.
The customer could provide documents relating to identity, the purpose of the transaction or the source of the funds.
Step 4: Bank Reviews the Explanation
After receiving the customer's response, the bank would have 10 calendar days to examine the explanation and supporting documents.
If the explanation is satisfactory, the temporary hold would have to be lifted immediately.
Step 5: Case Can Move to Law Enforcement
If the customer does not respond within the 20-day period, or the explanation does not remove the suspicion, the bank would refer the matter to the jurisdictional police through the NCRP/CFCFRMS portal.
The bank would not simply be allowed to keep the funds frozen indefinitely. Law enforcement would then have 30 days from the referral to issue a formal statutory restraint order.
What Happens to the Rest of the Money?
This is one of the most important aspects of the proposed framework.
Suppose a person has ₹1 lakh in their account and ₹10,000 is suspected to be linked to a cyber-fraud case.
Under the proposed targeted approach, the disputed ₹10,000 could be placed on hold while the remaining legitimate balance is generally allowed to remain accessible, subject to the applicable legal process.
The objective is to prevent innocent customers from losing access to their entire savings simply because one transaction is being investigated.
What Does "Money Mule" Mean?
A money mule is generally a person or account used to receive, transfer or move money connected with criminal activity.
Fraudsters may use other people's bank accounts to move money obtained through scams. Sometimes an account holder may knowingly participate, while in other situations a person may become involved without fully understanding the source or purpose of the funds.
The RBI's proposed framework specifically addresses bank accounts and transactions associated with money-mule activity and cyber-enabled financial fraud.
Role of AI in Detecting Cyber Fraud
Another major feature of the proposal is the use of AI-based transaction monitoring.
Banks would use technology to identify unusual patterns, including transactions that are significantly different from a customer's normal profile or transactions associated with known cyber-fraud networks.
The use of technology could help banks identify suspicious activity faster and potentially prevent fraudulent funds from being moved further through the banking system.
However, automated detection also needs appropriate safeguards so that genuine transactions are not unnecessarily blocked.
When Will the New RBI Framework Start?
The proposed directions are currently draft amendments, and RBI has invited comments from stakeholders and the public.
The draft framework is scheduled to take effect from April 1, 2027, although banks can adopt the measures earlier. RBI has said that final directions will be issued after considering the feedback received during the consultation process.
Therefore, customers should understand that this is not yet a final RBI rule.
How Is This Different From an Entire Account Freeze?
The key difference is proportionality.
Earlier concern
A cyber-fraud complaint involving a particular transaction could sometimes result in restrictions affecting the entire bank account.
Proposed approach
The RBI framework seeks to focus the temporary hold on the specific amount connected with the suspected transaction, while allowing legitimate funds to remain usable where legally possible.
This could provide greater protection to genuine customers while still allowing authorities to investigate suspicious funds.
What Should Bank Customers Do?
Even with the proposed safeguards, customers should remain careful when receiving or transferring money.
Some useful precautions include:
- Do not share your OTP, PIN or banking passwords.
- Avoid accepting money from unknown people into your account.
- Be careful with UPI and online payment requests.
- Keep transaction records and payment proofs.
- Report suspicious transactions immediately.
- Respond quickly if your bank asks for information about a transaction.
- Maintain documents showing the source of significant funds.
If your account is restricted, contact your bank and ask for details about the transaction or amount under hold. If the issue involves a cybercrime investigation, follow the official grievance and legal process rather than relying on unofficial intermediaries.
Why This Could Be Good News for Genuine Customers
The biggest benefit of the proposed framework could be that one disputed transaction does not automatically affect a customer's entire financial life.
A person may need their bank account every day to pay rent, salaries, EMIs, school fees, utility bills and other expenses. A targeted hold could help balance two objectives: protecting potentially disputed funds while reducing unnecessary disruption to legitimate banking activity.
The recent court directions and RBI's draft proposal both reflect growing concern about disproportionate account freezes in cyber-fraud investigations.
Conclusion
The RBI's proposed cyber-fraud framework could bring an important change to India's banking system.
Instead of automatically freezing an entire account when a suspicious transaction is detected, banks would generally focus on the disputed amount, while customers would get an opportunity to explain and prove the legitimacy of the transaction.
The proposal also introduces specific timelines, including 20 days for the customer to respond, 10 days for the bank to assess the explanation and 30 days for law enforcement to issue a formal restraint order after referral.
However, it is important to remember that these are proposed RBI directions, not final rules yet. The draft is scheduled to take effect from April 1, 2027, subject to the final directions issued after the consultation process.
For bank customers, the proposed change could mean a more balanced system—stronger action against cyber fraud while providing better protection for legitimate money and genuine account holders.
FAQs
1. What is RBI's new cyber fraud rule?
RBI has proposed a framework under which banks would generally place a temporary hold on the disputed amount linked to suspected cyber fraud instead of automatically freezing the entire account.
2. Is the new RBI rule already effective?
No. It is currently a draft proposal. The proposed directions are scheduled to take effect from April 1, 2027, although banks may adopt them earlier.
3. How much money can be temporarily frozen?
The proposed framework focuses on the specific disputed transaction amount linked to the suspected fraud, rather than automatically freezing the entire account.
4. What happens if my transaction is genuine?
Customers would get 20 calendar days to provide documents or information explaining the transaction. If the bank finds the explanation satisfactory, the hold would have to be lifted immediately.
5. Will my entire bank account be frozen?
The proposed framework aims to avoid unnecessary blanket freezes and focus on the disputed amount. However, wider restrictions may still apply where required under law and based on the circumstances of a case.
6. Why is RBI introducing this framework?
The proposal aims to improve the fight against cyber fraud and money-mule activity while reducing unnecessary hardship for genuine account holders.
7. Can banks use AI to detect cyber fraud?
Yes. The proposed framework requires banks to use AI-based transaction monitoring to identify unusual or potentially fraudulent transactions.
8. What should I do if my bank account is frozen?
Contact your bank, ask for details of the restriction and provide legitimate documents supporting the transaction. If the matter has been referred to law enforcement, follow the applicable official process.
Published on : 15th September
Published by : SMITA
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed