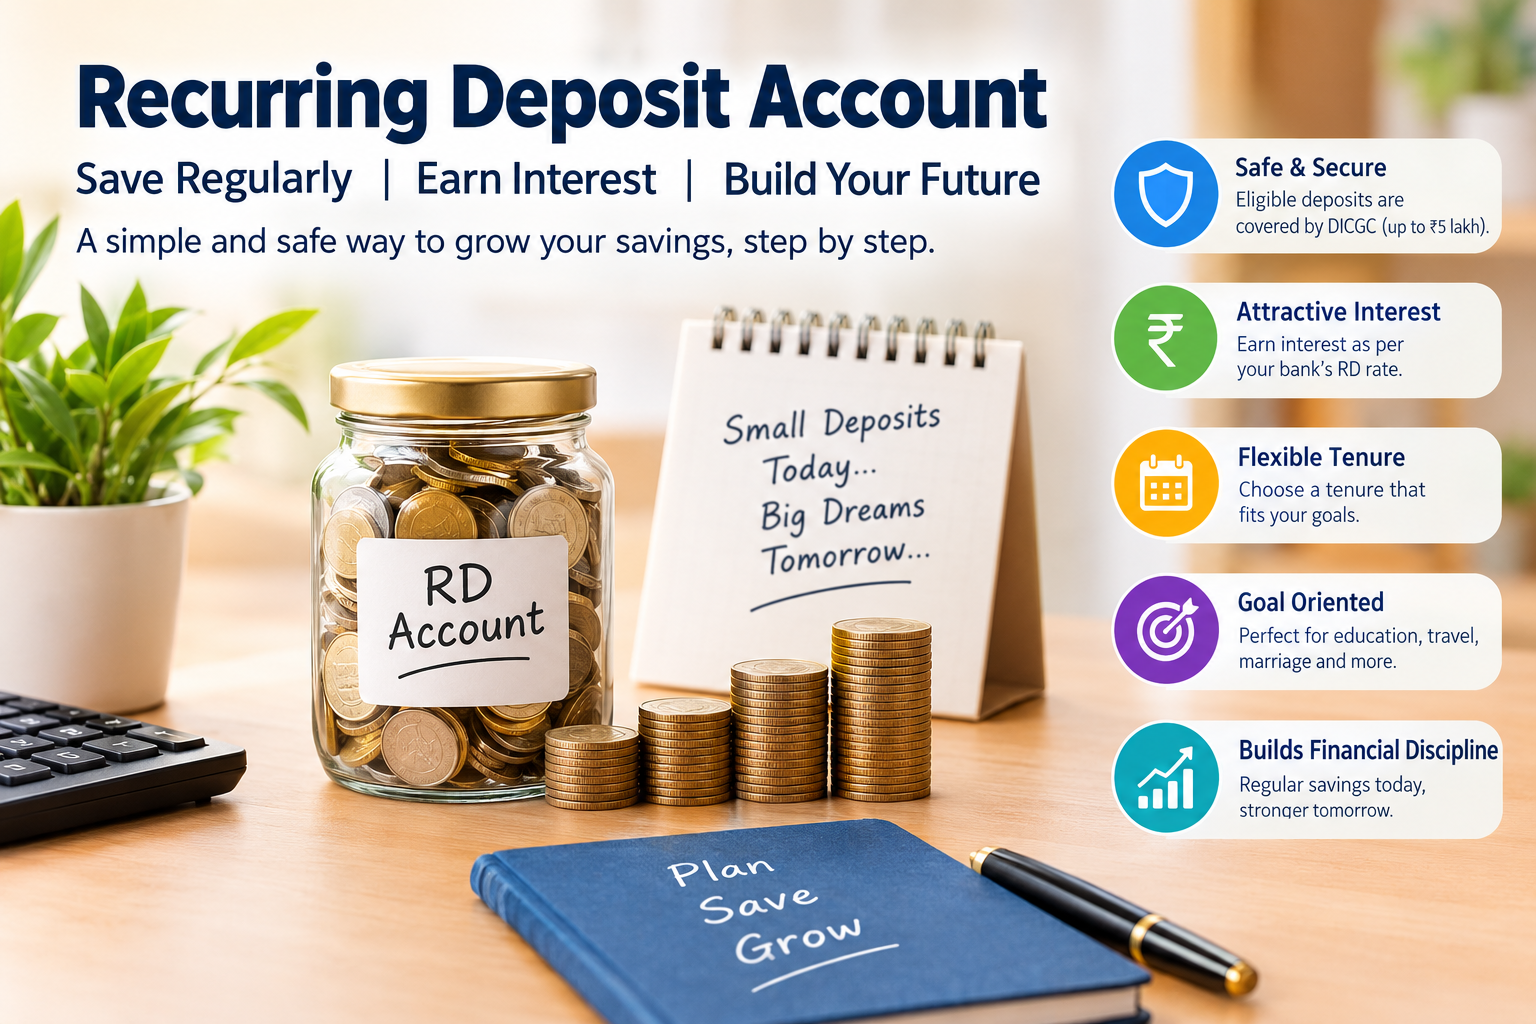
Saving money regularly can be difficult when there is no clear structure. A Recurring Deposit Account, commonly called an RD account, provides a simple way to turn monthly savings into a lump sum over a predetermined period.
Instead of depositing a large amount at one time, an RD generally allows a customer to deposit a fixed amount at regular intervals, usually monthly. The bank pays interest according to the applicable deposit terms, and the accumulated amount is paid at maturity subject to the account's conditions.
For people who want disciplined savings without directly taking market-linked investment risk, a recurring deposit can be a useful banking product to understand.
Quick answer: A recurring deposit is a term-deposit product in which you regularly deposit a predetermined amount for a fixed tenure and receive the accumulated principal plus applicable interest at maturity. RBI's deposit framework treats recurring deposits as a form of term deposit.
Important: Interest rates, minimum monthly deposits, tenure options, missed-installment rules, premature-closure conditions and other features can differ between banks. Always check the bank's latest RD terms before opening an account.
AI Answer Box: What Is a Recurring Deposit Account?
A Recurring Deposit Account (RD) is a bank deposit account designed for regular savings. The customer deposits a fixed amount periodically for a selected tenure. The bank pays interest according to the applicable RD rate and terms, and the accumulated amount is generally paid at maturity.
In simple words:
Monthly deposit + bank interest + fixed tenure = maturity amount
For example, if someone deposits ₹5,000 every month for 24 months, the total amount deposited before considering interest would be:
₹5,000 × 24 = ₹1,20,000
The final maturity amount would depend on the bank's applicable RD interest rate, compounding method and account terms.
Recurring deposits fall within the broader category of term deposits under RBI's deposit regulations.
What Is a Recurring Deposit Account?
A recurring deposit is a structured savings product offered by banks and certain other financial institutions.
The basic concept is straightforward:
- Choose an RD amount.
- Select an available tenure.
- Deposit the specified amount regularly.
- Earn interest according to the applicable rate.
- Receive the maturity proceeds according to the account terms.
Unlike a savings account, where money can generally be deposited and withdrawn as needed, an RD is designed around a predetermined savings commitment.
How Does an RD Account Work?
Suppose you decide to save ₹3,000 every month for 24 months.
Your total deposits would be:
₹3,000 × 24 = ₹72,000
The bank calculates interest according to the applicable RD methodology. Because deposits are made over time rather than all at once, the interest calculation is different from simply putting ₹72,000 into a fixed deposit on day one.
The exact maturity value should therefore be obtained from the bank's current RD calculator or deposit schedule.
Key Features of a Recurring Deposit
| Feature | Recurring Deposit |
|---|---|
| Deposit pattern | Regular instalments |
| Common frequency | Monthly |
| Tenure | Selected according to bank's available options |
| Interest | Based on applicable RD rate |
| Market-linked? | Generally no |
| Maturity | Principal plus applicable interest |
| Risk profile | Deposit-product risk rather than equity-market risk |
| Premature closure | Subject to bank's terms |
| Deposit insurance | Eligible bank deposits are covered subject to DICGC rules |
| Tax treatment | Interest may be taxable depending on taxpayer and applicable rules |
RBI regulations classify recurring deposits as term deposits.
Why Do People Choose a Recurring Deposit?
An RD is primarily about financial discipline.
Instead of waiting until the end of the month to see what money is left, an individual can set aside a predetermined amount as part of a savings plan.
Common reasons for opening an RD include:
- Building an emergency reserve gradually
- Saving for education
- Planning for a future purchase
- Creating a travel fund
- Saving for annual expenses
- Developing a regular savings habit
- Setting aside money for short- or medium-term goals
An RD can be particularly straightforward for someone who prefers predictable deposits rather than monitoring market prices.
Recurring Deposit Interest Rate: How Does It Work?
The RD interest rate is determined by the bank according to its deposit-rate framework and applicable regulations.
RBI requires scheduled commercial banks to disclose their deposit rates and follow their approved deposit-interest policies. Rates must be transparent and cannot simply be negotiated individually with customers.
Why RD rates matter
A higher interest rate can increase the maturity value, but the rate should never be considered in isolation.
Before opening an RD, compare:
- Interest rate
- Tenure
- Minimum monthly deposit
- Premature closure rules
- Missed-payment charges
- Senior-citizen benefits, if applicable
- Tax implications
- Bank's overall deposit terms
Do not rely on an old interest-rate article when opening an RD. Bank rates can change, so verify the rate on the bank's official website or current rate card.
How Is RD Interest Calculated?
RD interest calculation is not as simple as applying the annual rate to the entire amount deposited.
Why?
Because the deposits are made gradually.
If you deposit ₹5,000 each month for 12 months:
- The first ₹5,000 remains invested for much longer.
- The second ₹5,000 remains invested for a shorter period.
- The final ₹5,000 is invested for the shortest period.
Therefore, each instalment has a different interest-accrual period.
Example
Suppose:
- Monthly deposit = ₹5,000
- Tenure = 12 months
- Total principal deposited = ₹60,000
The final maturity value will be:
₹60,000 + applicable interest
The exact interest amount depends on the bank's RD calculation methodology and current rate.
For an accurate result, use the bank's official RD maturity calculator rather than assuming that the entire ₹60,000 earned interest for the full 12 months.
Recurring Deposit Maturity Amount
The maturity amount is the amount payable when the RD completes its agreed tenure, subject to the account's terms.
It generally consists of:
Total deposits + interest earned
Simple example
| Particular | Amount |
|---|---|
| Monthly deposit | ₹5,000 |
| Tenure | 24 months |
| Total deposits | ₹1,20,000 |
| Interest | Depends on bank/rate |
| Maturity amount | ₹1,20,000 + applicable interest |
This example is intended to explain the structure rather than represent a particular bank's current maturity quote.
Recurring Deposit vs Fixed Deposit
Both RDs and FDs are term-deposit products, but their deposit patterns are different.
| Feature | Recurring Deposit | Fixed Deposit |
|---|---|---|
| Initial investment | Regular instalments | Lump sum |
| Saving style | Monthly | One-time |
| Suitable for | Regular savers | People with available lump sums |
| Interest | Based on applicable RD rate | Based on applicable FD rate |
| Maturity | After selected tenure | After selected tenure |
| Monthly commitment | Usually required | Usually not required |
| Goal | Build savings gradually | Deploy existing savings |
Which structure fits a particular goal?
If you receive a salary every month and want to save a fixed amount, an RD structure may be convenient.
If you already have a lump sum that you do not need immediately, an FD may be a more natural product to compare.
This is a product-structure comparison, not a guarantee that one will produce a higher return.
RD vs SIP: What's the Difference?
Recurring deposits and Systematic Investment Plans are often compared because both involve regular contributions.
However, they work very differently.
| Factor | RD | SIP |
|---|---|---|
| Product type | Bank deposit | Investment route, commonly into mutual funds |
| Return | Deposit interest | Market-linked returns |
| Capital value | Not market-linked in the same way | Can rise or fall |
| Regular contribution | Yes | Yes |
| Market risk | Generally lower than market-linked investments | Present |
| Return certainty | Interest rate is specified by product terms | Returns are not guaranteed |
| Goal | Predictable savings | Market-linked wealth accumulation |
An investor should understand the difference between saving and investing before choosing between these structures.
Benefits of a Recurring Deposit Account
1. Encourages Financial Discipline
An RD creates a regular savings habit.
Instead of relying entirely on leftover income, the depositor commits to a predetermined contribution.
2. Simple to Understand
The product is relatively straightforward:
Deposit regularly → earn interest → receive maturity proceeds.
3. Useful for Goal-Based Saving
An RD can be used for goals with a known time horizon, such as:
- School or college expenses
- Annual insurance premiums
- Travel
- Electronics or household purchases
- Planned family expenses
- Short- to medium-term savings goals
4. Less Exposure to Market Price Movements
Unlike market-linked products, a conventional bank RD is not directly dependent on daily stock-market movements.
That can make the structure easier to plan around for people who value predictability.
5. Deposit Insurance May Apply
Eligible deposits in insured banks, including recurring deposits, are covered by DICGC deposit insurance subject to the applicable rules and limits.
DICGC currently provides insurance of up to ₹5 lakh per depositor per bank, covering principal and accrued interest, subject to the "same right and same capacity" aggregation rules.
Disadvantages of a Recurring Deposit
An RD is not perfect for every financial goal.
Potential limitations include:
- Fixed contribution commitment
- Premature closure may affect interest
- Interest income can have tax implications
- Returns may be lower than some market-linked investments over long periods
- Monthly instalment requirements may be inconvenient when cash flow is irregular
- Bank-specific penalties or conditions may apply
The important point is to read the product terms before opening the account.
Pros and Cons of Recurring Deposit
| Pros | Cons |
|---|---|
| Encourages regular saving | Requires regular deposits |
| Easy to understand | Premature closure can affect returns |
| Suitable for goal-based saving | Interest is subject to taxation where applicable |
| Not directly linked to equity-market movements | May not suit long-term wealth creation alone |
| Maturity amount can be planned | Rates vary between banks |
| Eligible bank deposits can have DICGC cover | Insurance has a ₹5 lakh limit per depositor per bank |
How to Open a Recurring Deposit Account
Opening an RD is generally straightforward.
Step 1: Choose a Bank
Compare banks based on:
- Current RD interest rate
- Tenure options
- Minimum monthly deposit
- Digital account-opening facilities
- Premature withdrawal policy
- Missed-instalment rules
- Customer service
Step 2: Decide Your Monthly Amount
Choose an amount that you can comfortably maintain throughout the tenure.
A smaller sustainable contribution is generally more practical than selecting an amount that creates financial pressure.
Step 3: Select the Tenure
Choose the tenure according to your financial goal.
For example:
Goal date → required savings → monthly contribution → suitable tenure
Step 4: Submit Required Information
The bank may request standard KYC and account information depending on the method of opening the RD.
Step 5: Set Up the Payment
Many banks allow customers to automate recurring deposits from their linked savings account.
Step 6: Track the RD
Keep track of:
- Monthly instalments
- Maturity date
- Interest rate
- Nominee details
- Account statements
- Bank communications
What Happens If You Miss an RD Instalment?
The consequences depend on the bank's terms.
A missed instalment may lead to:
- A penalty or charge
- The account becoming irregular
- Changes in maturity proceeds
- Restrictions or closure under certain circumstances
Because policies vary, customers should check the bank's specific RD rules before opening the account.
Practical tip: Keep enough balance in the linked account before the scheduled instalment date if you have enabled automatic payment.
Can You Withdraw an RD Before Maturity?
This depends on the bank's RD terms.
Since an RD is a term deposit, premature closure can affect the interest payable. RBI's current deposit framework allows banks to have policies covering penalties for premature withdrawal, and the relevant penalty components must be communicated to depositors when the deposit is accepted.
Before closing an RD early, check:
- Whether premature closure is permitted
- Applicable penalty
- Interest rate applicable after premature closure
- Minimum period required for interest
- Whether the bank offers another option for your situation
Is Recurring Deposit Interest Taxable?
Interest earned from an RD can have tax implications.
The tax treatment depends on the taxpayer's circumstances and the applicable income-tax rules.
For example, the Income Tax Department states that resident senior citizens can claim a deduction of up to ₹50,000 on eligible interest from deposits under Section 80TTB, subject to the applicable conditions.
Tax rules can change, so taxpayers should verify the rules applicable to the relevant financial year.
Important distinction
TDS and income-tax liability are not exactly the same thing.
A bank may deduct TDS when applicable, but taxpayers still need to consider their total taxable income and applicable tax rules while filing their return.
Is an RD Covered by DICGC Insurance?
Yes, eligible recurring deposits with insured banks are covered by DICGC.
DICGC explicitly lists recurring deposits among the deposit types covered by its insurance scheme.
The current insurance ceiling is:
₹5 lakh per depositor per insured bank
This includes principal plus accrued interest and applies according to DICGC's aggregation rules. Deposits held in different branches of the same bank are generally aggregated when determining the insurance limit.
This does not mean every financial product is automatically insured. DICGC specifically distinguishes eligible bank deposits from products such as mutual funds, stocks, bonds, ETFs and cryptocurrencies.
How to Choose the Right RD
Instead of looking only at the advertised interest rate, use a broader checklist.
RD comparison checklist
1. Interest rate
Check the current rate on the bank's official website.
2. Tenure
Match the maturity date with your financial goal.
3. Monthly commitment
Choose an instalment you can maintain comfortably.
4. Premature closure
Understand the financial consequences before opening the account.
5. Missed instalments
Read the bank's rules on delayed payments.
6. Tax treatment
Consider whether the interest affects your taxable income.
7. Deposit insurance
Check whether the bank is insured and understand the DICGC limit.
Real-World Savings Example
Consider someone who wants to accumulate money for a planned expense two years from now.
Instead of trying to save a large amount at the end, they decide to deposit ₹4,000 every month into an RD.
Over 24 months:
₹4,000 × 24 = ₹96,000
The final amount will be higher than the deposited principal if interest is payable under the account's terms.
The practical advantage is the savings habit: the goal is divided into manageable monthly contributions.
This illustrates why RDs can be useful for people who prefer a structured approach to saving.
Expert Commentary: What Should Savers Check?
A useful way to evaluate an RD is to treat it as a financial commitment rather than simply an interest-rate product.
Before opening one, consider:
- Can you comfortably make every instalment?
- Does the maturity date match your goal?
- Could you need the money earlier?
- Have you compared the bank's current terms?
- Have you considered taxation?
- Is the deposit amount within a level you are comfortable holding with one bank?
RBI's deposit framework emphasizes transparency around deposit rates and premature-withdrawal policies, making the bank's current terms an important part of the decision.
Recurring Deposit for Different Financial Goals
| Financial Goal | RD Use Case |
|---|---|
| Emergency savings | Can help build a reserve gradually |
| Travel fund | Useful for a fixed future date |
| Education expenses | Can support planned monthly saving |
| Festival expenses | Suitable for short-term goal planning |
| Gadget purchase | Can spread saving over several months |
| Annual premium | Can build funds ahead of payment |
| Long-term wealth creation | Usually requires comparison with other investment options |
An RD should generally be viewed as one component of a broader financial plan rather than a universal solution.
Common Mistakes to Avoid When Opening an RD
Mistake 1: Choosing an Unaffordable Instalment
A monthly amount should fit comfortably into your regular budget.
Mistake 2: Ignoring the Maturity Date
Do not select a tenure without checking when you actually need the money.
Mistake 3: Looking Only at the Interest Rate
A slightly higher rate may not compensate for inconvenient withdrawal or instalment conditions.
Mistake 4: Not Reading Premature-Closure Rules
Understand the financial impact before committing.
Mistake 5: Forgetting Tax Implications
Interest income may have tax consequences depending on your circumstances.
Mistake 6: Assuming All Deposits Are Insured Without Limits
DICGC insurance has a ceiling and aggregation rules.
Key Takeaways
- A Recurring Deposit Account helps people save a fixed amount regularly.
- RD is classified as a type of term deposit under RBI's deposit framework.
- The maturity amount consists of the deposits plus applicable interest.
- RD interest depends on the bank, tenure and product terms.
- Interest rates should be checked using the bank's current official rate card.
- Premature closure may affect the interest received and may involve a penalty under the bank's policy.
- Eligible recurring deposits with insured banks are covered by DICGC up to ₹5 lakh per depositor per bank, including principal and accrued interest, subject to applicable rules.
- RD interest can have tax implications.
- Senior citizens may have specific tax provisions applicable to eligible deposit interest.
- An RD can be useful for disciplined, goal-based saving.
Vizzve Financial Promotion
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
For readers considering borrowing alongside their savings plans, it is important to compare the total cost of a loan, including interest and applicable charges, before making a borrowing decision.
Frequently Asked Questions About Recurring Deposit Accounts
1. What is a recurring deposit account?
A recurring deposit account is a term-deposit product where a customer deposits a predetermined amount at regular intervals for a selected tenure and earns interest according to the applicable bank terms.
2. Is an RD better than keeping money in a savings account?
The two products serve different purposes. A savings account provides greater liquidity, while an RD is designed around regular contributions and a fixed tenure. The appropriate choice depends on the purpose of the money.
3. Is RD interest guaranteed?
The applicable deposit rate is specified according to the bank's product terms. However, customers should check the exact rate and conditions before opening the RD.
4. Can I open an RD online?
Many banks provide online RD-opening facilities for eligible existing customers. Availability and requirements vary between banks.
5. Can I close an RD before maturity?
Premature closure may be possible depending on the bank's rules. It can affect the interest payable and may involve a penalty.
6. What happens if I miss an RD instalment?
The consequences depend on the bank's terms and may include charges or other account-level consequences.
7. Is RD interest taxable?
RD interest can be taxable depending on the taxpayer's circumstances and applicable income-tax rules.
8. Is an RD covered by DICGC insurance?
Eligible recurring deposits in insured banks are covered by DICGC subject to the applicable ₹5 lakh insurance ceiling and aggregation rules.
9. Does DICGC insurance cover interest as well as principal?
Yes. DICGC states that the insurance covers principal and accrued interest up to the maximum eligible amount of ₹5 lakh.
10. Is an RD the same as an FD?
No. An RD generally involves regular instalments, while an FD normally involves placing a lump sum for a fixed tenure.
11. Can I increase my RD instalment every month?
The ability to change the instalment depends on the bank's product design. A customer should check the specific RD terms.
12. Can I take a loan against an RD?
Availability of loans or advances against deposits depends on the bank's policies and the specific deposit terms. Customers should check directly with their bank.
13. How much should I deposit in an RD every month?
There is no universal amount. A sensible instalment is one that fits comfortably within your monthly budget while matching your savings goal and tenure.
14. Is RD suitable for beginners?
An RD can be easy for beginners to understand because it provides a structured savings schedule and predetermined deposit terms. However, investors should still compare it with other options based on their goals.
15. How can I calculate my RD maturity amount?
You can use your bank's official RD calculator by entering the monthly deposit, applicable interest rate and tenure. The resulting amount depends on the bank's calculation methodology and product terms.
Conclusion
A Recurring Deposit Account is a simple financial product built around one powerful idea: save regularly instead of waiting to save what is left over.
For someone with a predictable monthly income and a defined savings goal, an RD can provide a structured route toward accumulating money over a selected period.
However, choosing an RD should involve more than simply searching for the highest interest rate. Compare the current rate, tenure, monthly commitment, premature-closure rules, missed-instalment conditions, taxation and deposit-insurance coverage.
Always verify the latest terms directly with the bank before opening an account because rates and product conditions can change.
Plan your finances carefully
If you are also exploring borrowing options for a planned expense, Vizzve Financial offers personal-loan support with a focus on quick processing, low documentation and an easy application experience.
Apply at www.vizzve.com.
Internal Linking Suggestions
For a finance website, consider linking this article internally to:
- Personal Loan Guide
- How to Improve Your Credit Score
- Personal Loan Eligibility
- Loan EMI Calculator Guide
- Fixed Deposit vs Recurring Deposit
- Savings Account Guide
- Emergency Fund Planning
- How to Manage Monthly Expenses
- Personal Finance Planning
- Loan Interest Rate Guide
Use descriptive anchor text such as "recurring deposit vs fixed deposit" rather than generic anchors like "click here."
External Linking Suggestions
For authoritative references, link to:
- RBI's Master Direction – Interest Rate on Deposits for deposit regulations.
- RBI's FAQs on Interest Rate on Deposits for explanations of premature withdrawal and other deposit rules.
- DICGC's Guide to Deposit Insurance for deposit-insurance coverage.
- Income Tax Department resources for current tax provisions relating to deposit interest.
SEO Summary Box
Topic: Recurring Deposit Account
Primary Intent: Informational
Target Audience: Indian savers, salaried professionals, students, families and first-time depositors
Core Question: What is a recurring deposit account and how does it work?
Main Benefits: Regular savings, disciplined contributions, predictable deposit structure
Main Considerations: Interest rate, tenure, taxation, premature closure and bank-specific conditions
Current Regulatory Reference: RBI deposit framework and DICGC deposit-insurance rules
DICGC Insurance Limit: Up to ₹5 lakh per depositor per insured bank, subject to applicable aggregation rules
Published on : 16 th september
Published by : Sumanth Arumulla
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed