

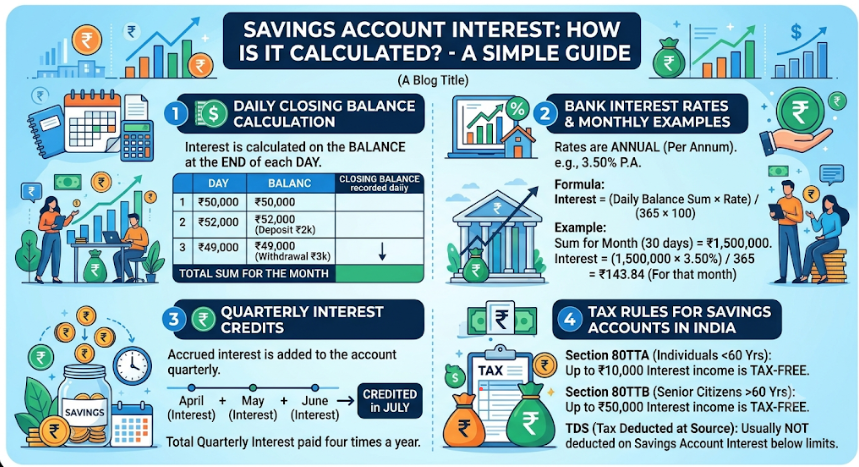
Introduction
A savings account is one of the most common ways to keep money safe and accessible. Whether you receive your salary, save for monthly expenses or maintain an emergency fund, a savings account helps you manage everyday finances.
But have you ever wondered how banks calculate the interest credited to your account?
Many people assume that interest is calculated only on the balance available at the end of the month. However, Indian banks generally use a daily balance-based calculation method. This means the amount you earn depends on your closing balance each day and the interest rate applicable to your account.
For example, if you maintain ₹50,000 in your savings account and your bank offers an annual interest rate of 3%, you can earn approximately ₹123.29 over 30 days, assuming the balance remains unchanged and a 365-day calculation basis is used.
The actual amount depends on your bank's interest rate, daily balances, calculation method and crediting schedule.
In this guide, we explain how savings account interest is calculated in India, how to calculate it manually, when banks credit interest, how withdrawals affect earnings and what you should know about taxation.
AI Answer Box: How Is Savings Account Interest Calculated?
Savings account interest in India is generally calculated using the daily closing balance method.
Banks calculate interest on the eligible balance at the end of each day using the applicable annual interest rate. The daily interest amounts are added together for the relevant period.
Basic formula:
Interest = Daily Closing Balance × Annual Interest Rate × Number of Days ÷ 365
For example:
-
Daily closing balance: ₹50,000
-
Annual interest rate: 3%
-
Number of days: 30
-
Approximate interest: ₹123.29
Banks generally credit savings account interest quarterly or at shorter intervals, depending on their policy and applicable RBI directions.
The actual interest may differ if your balance changes, the bank uses different rate slabs or the applicable day-count convention differs.
1. What Is Savings Account Interest?
Savings account interest is the amount a bank pays you for maintaining money in an eligible savings deposit account.
When you deposit money into a savings account, the bank uses the funds as part of its banking operations, subject to applicable regulations. In return, it pays interest according to its published savings deposit interest rate and account conditions.
Why do banks pay interest?
Savings accounts encourage people to maintain deposits in the banking system.
The interest earned can help customers:
-
Earn a return on money kept for everyday needs.
-
Maintain emergency savings.
-
Save for short-term financial goals.
-
Earn some income without locking money into a fixed deposit.
-
Manage regular income and expenses.
However, savings account interest rates are generally lower than many fixed deposit rates. The main advantage of a savings account is convenient access to money.
2. How Is Savings Account Interest Calculated in India?
Indian banks generally calculate savings account interest using the daily product method.
Under this method, the bank considers the closing balance at the end of each day rather than using only one balance for the entire month.
The Reserve Bank of India's deposit directions describe daily product interest calculation for savings deposits. Interest is credited at quarterly or shorter intervals under the relevant directions. Individual banks publish their applicable interest rates and account terms.
Understanding the daily closing balance method
Suppose you have ₹40,000 in your savings account.
-
On Day 1, your closing balance is ₹40,000.
-
On Day 2, you deposit another ₹10,000.
-
On Day 3, your balance becomes ₹50,000.
-
On Day 4, you withdraw ₹5,000.
The bank calculates interest based on the eligible closing balance for each day.
This means the interest amount changes when your account balance changes.
Savings account interest formula
A simplified formula for a constant daily balance is:
Interest = (Principal × Annual Interest Rate × Number of Days) ÷ 365
Where:
-
Principal = Eligible daily closing balance
-
Annual interest rate = Bank's applicable yearly rate
-
Number of days = Number of days the balance is maintained
-
365 = Illustrative day-count basis
For an account with changing daily balances, calculate interest separately for each day's closing balance and add the results.
Example: Interest on ₹50,000
Assume:
| Particulars | Amount |
|---|---|
| Savings account balance | ₹50,000 |
| Annual interest rate | 3% |
| Number of days | 30 |
| Calculation basis | 365 days |
Calculation:
₹50,000 × 3 × 30 ÷ (100 × 365)
Approximate interest = ₹123.29
This is an illustration, not a guaranteed bank payout. Actual bank calculations may use the applicable day-count convention and rounding rules.
3. Savings Account Interest Calculation Examples
Let's understand how interest changes depending on the balance maintained in the account.
The following examples assume a constant balance, a 3% annual interest rate and a 365-day calculation basis.
| Savings balance | Annual interest rate | Period | Approximate interest |
|---|---|---|---|
| ₹10,000 | 3% | 30 days | ₹24.66 |
| ₹25,000 | 3% | 30 days | ₹61.64 |
| ₹50,000 | 3% | 30 days | ₹123.29 |
| ₹75,000 | 3% | 30 days | ₹184.93 |
| ₹1,00,000 | 3% | 30 days | ₹246.58 |
These figures are before tax and are provided only to explain the calculation.
Example 2: What happens when your balance changes?
Suppose you maintain:
-
₹50,000 for 15 days.
-
₹70,000 for the next 15 days.
-
Annual interest rate: 3%.
The calculation is:
First 15 days:
₹50,000 × 3 × 15 ÷ 36,500 = ₹61.64
Next 15 days:
₹70,000 × 3 × 15 ÷ 36,500 = ₹86.30
Total approximate interest:
₹61.64 + ₹86.30 = ₹147.94
This shows why depositing money earlier can increase the interest earned, provided the additional balance remains in the account.
4. Does Savings Account Interest Depend on Daily Balance or Monthly Balance?
Savings account interest is generally based on daily closing balances, not simply the final balance at the end of the month.
Here is the difference:
| Factor | Daily closing balance method | Month-end balance method |
|---|---|---|
| Balance considered | Each day's closing balance | Balance on a selected month-end date |
| Deposits | Affect interest from applicable days | May not reflect earlier daily balances |
| Withdrawals | Affect interest from applicable days | May not reflect earlier daily balances |
| Calculation | Daily interest amounts are added | Uses one selected balance |
| General banking approach in India | Daily product method | Not the standard savings interest method |
Why does the daily balance method matter?
Imagine two customers maintain ₹50,000 at the end of the month.
-
Customer A maintained ₹50,000 throughout the month.
-
Customer B deposited ₹50,000 only during the last few days.
Although their final balances are identical, Customer A would generally earn more interest for that month because the money remained in the account for more days.
5. When Do Banks Credit Savings Account Interest?
Savings account interest is generally credited quarterly or at shorter intervals, depending on the applicable regulatory directions and the bank's policy.
Quarterly interest means the bank accumulates interest for a three-month period and credits it to your savings account.
Common quarterly crediting periods
Some banks use schedules such as:
| Quarter | Example interest credit period |
|---|---|
| April–June | June or July |
| July–September | September or October |
| October–December | December or January |
| January–March | March or April |
These are illustrative periods. The actual credit date depends on the bank.
Does interest get credited every month?
Not necessarily.
A bank may calculate interest daily but credit the accumulated amount quarterly. Daily calculation and quarterly crediting are two different things.
How can you check whether interest has been credited?
You can check through:
-
Mobile banking application.
-
Internet banking.
-
Bank account statement.
-
Passbook.
-
Bank SMS or email alerts, where available.
Look for transaction descriptions such as savings interest, interest credit or SB interest.
6. What Factors Affect Savings Account Interest?
Several factors influence how much interest you receive.
1. Account balance
A higher eligible daily closing balance generally earns more interest at the same rate.
For example, ₹1,00,000 earns approximately twice as much interest as ₹50,000 when both balances remain unchanged for the same period at the same rate.
2. Bank interest rate
Different banks may offer different savings account interest rates.
The rate can depend on the bank's policy, account category and balance slab.
3. Number of days
Money maintained for a longer period can earn more interest than money deposited for only a few days.
4. Balance slabs
Some banks may offer different interest rates for different balance ranges.
For example, the rate applicable to a smaller balance may differ from the rate offered on the portion of a larger balance above a specified threshold.
Always check the bank's latest interest rate schedule.
5. Account type
Savings account categories may have different terms and features.
Examples include:
-
Regular savings accounts.
-
Salary savings accounts.
-
Basic Savings Bank Deposit Accounts.
-
Senior citizen-focused savings products, where offered.
-
Digital savings accounts.
The applicable interest rate and conditions should be confirmed with the bank.
7. How Do Different Savings Account Interest Rates Compare?
The following table demonstrates how the annual interest rate changes the approximate interest earned on ₹1,00,000 maintained for 30 days.
| Annual interest rate | Approximate interest for 30 days |
|---|---|
| 2.5% | ₹205.48 |
| 3% | ₹246.58 |
| 3.5% | ₹287.67 |
| 4% | ₹328.77 |
| 5% | ₹410.96 |
| 6% | ₹493.15 |
Illustrative calculation using a 365-day basis. These are not current rate quotations from specific banks.
Why should you compare interest rates?
Even a small difference in annual interest rates can affect your earnings when you maintain a larger balance over a longer period.
However, do not choose a bank based only on the highest advertised rate.
Also compare:
-
Minimum balance requirements.
-
Service charges.
-
ATM and transaction facilities.
-
Digital banking services.
-
Customer support.
-
Deposit protection coverage.
-
Terms for higher balance slabs.
8. Savings Account vs Fixed Deposit: Which Earns More Interest?
Savings accounts and fixed deposits serve different financial purposes.
A savings account offers convenient access to money, while a fixed deposit generally offers a fixed interest rate for a chosen period.
| Comparison factor | Savings account | Fixed deposit |
|---|---|---|
| Main purpose | Everyday savings | Planned savings |
| Interest rate | Usually lower | Often higher |
| Access to funds | Generally easy | Subject to premature withdrawal terms |
| Interest calculation | Generally daily balance-based | Depends on deposit type and bank terms |
| Interest credit | Often quarterly or shorter intervals | Depends on payout or cumulative option |
| Lock-in | Usually no fixed maturity | Fixed tenure |
| Suitable for | Emergency and daily expenses | Money not needed immediately |
When should you choose a savings account?
A savings account may be suitable when:
-
You need regular access to money.
-
You are building an emergency fund.
-
You receive salary or business income.
-
You have upcoming monthly expenses.
-
You want to keep money available for unexpected needs.
When should you consider a fixed deposit?
A fixed deposit may be worth comparing when:
-
You have money that you do not need immediately.
-
You want a predictable interest rate for a selected period.
-
You can maintain the deposit until maturity.
-
You have compared premature withdrawal conditions.
Practical tip: Keep emergency money accessible. Consider fixed deposits for savings that can remain untouched for the selected tenure.
9. Pros and Cons of Earning Interest Through a Savings Account
Advantages
-
Money remains accessible for everyday use.
-
Interest is earned on eligible balances.
-
Suitable for emergency savings.
-
Convenient digital banking facilities.
-
No need to lock money for a fixed period.
-
Interest is calculated based on daily closing balances under the general daily product method.
Disadvantages
-
Interest rates may be lower than fixed deposits.
-
Inflation can reduce the purchasing power of savings.
-
Higher balances may earn different rates depending on bank policy.
-
Some accounts have minimum balance requirements or service charges.
-
Interest may be taxable depending on the customer's tax position.
10. How to Calculate Savings Account Interest Manually
You do not always need an online calculator to estimate your savings account interest.
Follow these simple steps.
Step 1: Check your bank's interest rate
Find the current savings deposit interest rate on your bank's official website or rate card.
Step 2: Check your daily closing balance
Identify the closing balance for each day of the interest period.
Step 3: Apply the formula
For each day:
Daily interest = Daily closing balance × Annual rate ÷ (100 × 365)
Step 4: Add the daily interest amounts
Calculate the interest for all days and add the amounts together.
Step 5: Check the credited amount
Compare your estimate with the interest credited in your bank statement. Small differences may arise due to the bank's day-count convention, applicable rate slabs and rounding.
Quick calculation example
Suppose your account has:
-
Balance: ₹30,000
-
Annual interest rate: 3%
-
Period: 90 days
Approximate interest:
₹30,000 × 3 × 90 ÷ 36,500
Interest = ₹221.92 approximately
The actual amount may differ according to the bank's calculation and applicable terms.
11. How Can You Earn More Savings Account Interest?
You cannot control every factor affecting your bank's interest rate, but you can manage your savings habits.
Maintain a healthy account balance
Keeping money in your account for more days can increase the interest earned, assuming the same rate applies.
Deposit money earlier
If you already have money available for savings, depositing it earlier rather than waiting until the end of the month can increase the number of interest-earning days.
Compare different bank rates
Check the official interest rate cards of different banks. Look at the rate applicable to your actual balance rather than only the highest advertised slab.
Avoid unnecessary withdrawals
Withdrawals reduce the daily closing balance and may reduce interest for the remaining days.
However, do not avoid essential withdrawals merely to earn a small amount of additional interest.
Check account charges
A higher interest rate may not necessarily mean a better account if the account has costly conditions or charges.
Keep emergency savings separate
Maintain money for emergencies in an accessible account rather than locking all your savings into a fixed deposit.
12. Is Savings Account Interest Taxable in India?
Yes. Savings account interest is generally taxable as income under the applicable income-tax rules.
However, eligible taxpayers may claim deductions subject to the conditions in the relevant tax law.
As of November 2026, the Income-tax Act, 2025 is in force from April 1, 2026.
Deduction under Section 153 of the Income-tax Act, 2025
The provision provides:
-
For an individual who is not a senior citizen, and for an eligible Hindu Undivided Family (HUF), a deduction of up to ₹10,000 on eligible savings account interest.
-
For a resident senior citizen, a deduction of up to ₹50,000 on eligible interest from deposits, including savings and time deposits.
These deductions are subject to the statutory conditions. Tax treatment can also depend on the applicable tax regime and the taxpayer's circumstances.
Example
Suppose an eligible non-senior individual earns ₹8,000 in savings account interest during the tax year.
The potential deduction under Section 153 may cover the full ₹8,000, subject to the applicable conditions.
If the interest is ₹15,000, the deduction limit for eligible savings account interest is ₹10,000, so the remaining amount may be taxable.
Important: Do not assume that all savings interest is tax-free. Check the current tax rules, applicable regime and eligibility before filing your return.
13. Common Mistakes People Make About Savings Account Interest
Many account holders misunderstand how savings interest works.
Here are some common mistakes to avoid.
-
Checking only the month-end balance: Interest generally depends on daily closing balances.
-
Assuming all banks offer the same rate: Banks publish their own rates and conditions.
-
Ignoring balance slabs: Higher balances may be subject to different rates.
-
Confusing calculation with crediting: Interest may be calculated daily but credited quarterly.
-
Ignoring tax rules: Savings interest may need to be reported for tax purposes.
-
Comparing only the advertised rate: Account charges and conditions also matter.
-
Assuming a savings account is an investment substitute: It is primarily designed for accessible savings, not necessarily long-term wealth creation.
14. RBI Guidelines and Important Banking Facts
The Reserve Bank of India regulates banking activities and issues directions concerning deposit interest and customer protection.
Important points for savings account holders include:
-
Banks must disclose their applicable deposit interest rates.
-
Savings interest is generally calculated using daily closing balances under the daily product method.
-
The interest rate can vary between banks and account categories.
-
Banks credit savings deposit interest at quarterly or shorter intervals under applicable directions.
-
Banks must follow the relevant regulatory requirements for their category.
The RBI's 2025 deposit directions for Local Area Banks, updated as of October 1, 2026, specify daily product calculation for domestic savings deposits and quarterly or shorter interest crediting. Other bank categories have their own applicable RBI directions, so customers should check the rules relevant to their bank.
Key Takeaways
-
Savings account interest is generally calculated using daily closing balances.
-
The annual interest rate and number of days determine how much interest you earn.
-
Deposits and withdrawals can change your daily interest calculation.
-
Banks generally credit interest quarterly or at shorter intervals.
-
Different banks may offer different interest rates and balance slabs.
-
Savings accounts provide liquidity, while fixed deposits may offer higher returns.
-
Savings account interest is generally taxable, subject to applicable deductions.
-
Compare rates, fees and account conditions before choosing a savings account.
Frequently Asked Questions (FAQs)
1. How is savings account interest calculated in India?
Savings account interest is generally calculated on the daily closing balance. Banks apply the applicable annual interest rate to each day's eligible balance and add the daily interest amounts.
2. What is the formula for savings account interest?
A simplified formula is:
Interest = Principal × Annual Interest Rate × Number of Days ÷ 36,500.
This assumes a 365-day calculation basis and a constant balance.
3. Is savings account interest calculated daily or monthly?
Interest is generally calculated daily using the closing balance. However, the bank may credit the accumulated interest quarterly or at shorter intervals.
4. How much interest will I earn on ₹50,000 in a savings account?
At an illustrative annual interest rate of 3%, ₹50,000 maintained for 30 days earns approximately ₹123.29 using a 365-day basis. Actual earnings depend on the bank's rate and calculation method.
5. When do banks credit savings account interest?
Many banks credit savings interest quarterly. Some may credit it at shorter intervals, depending on their policy and applicable RBI directions.
6. Does withdrawing money reduce savings account interest?
Yes. A withdrawal reduces the closing balance for the applicable day and may reduce the interest earned for the remaining period.
7. Do all banks offer the same savings account interest rate?
No. Banks determine their savings deposit rates according to their policies and applicable regulations. Customers should check the latest rate card.
8. Is savings account interest taxable?
Generally, yes. Savings account interest is taxable under the applicable income-tax provisions, although eligible taxpayers may claim deductions subject to conditions.
9. Can I earn interest on a zero-balance savings account?
An eligible zero-balance savings account may earn interest if the bank's product terms provide for it. Check the account's interest conditions.
10. Is savings account interest compounded?
Interest is generally calculated daily and credited periodically. Once credited, the amount becomes part of the account balance and may earn interest in subsequent periods, subject to the bank's calculation method.
11. What is the difference between savings account interest and fixed deposit interest?
Savings account interest is generally calculated on daily balances and offers easy access to money. Fixed deposits have a chosen tenure and may offer a higher contracted interest rate, subject to their terms.
12. Can I calculate savings account interest without a calculator?
Yes. Use the formula: balance × annual rate × number of days ÷ 36,500 for a constant balance and a 365-day basis. For changing balances, calculate each day's interest separately and add it.
13. Does a higher savings balance always earn a higher interest rate?
Not necessarily. Some banks use balance slabs and may apply different rates to different portions of the balance. Check the bank's official rate schedule.
14. Can savings account interest rates change?
Yes. Banks may revise their savings deposit rates according to their policies and applicable regulatory requirements. Check the latest published rate before estimating future earnings.
15. Is it better to keep money in a savings account or a fixed deposit?
A savings account is generally more suitable for everyday expenses and emergency funds. A fixed deposit may suit money that you can keep invested for a chosen period. The right option depends on liquidity needs, returns and financial goals.
Conclusion
Understanding how savings account interest is calculated can help you manage your money more effectively.
In India, savings account interest is generally calculated using the daily closing balance method. This means the amount you earn depends on your balance each day, the applicable annual interest rate and the number of days your money remains in the account.
Instead of checking only the interest rate, compare the bank's balance slabs, account charges, crediting schedule and other conditions. Maintain an emergency fund, plan withdrawals carefully and understand the tax treatment of your interest income.
Small savings habits can make a difference over time.
Published on : 16th November
Published by : Reddy kumar
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed