

Introduction
Investing a fixed amount every month has become an increasingly familiar part of personal finance in India.
Instead of waiting for the "right" market level or trying to invest a large amount at once, many investors are choosing to put a predetermined amount into mutual funds at regular intervals.
This approach is known as a Systematic Investment Plan, or SIP.
The latest industry numbers show just how large the trend has become.
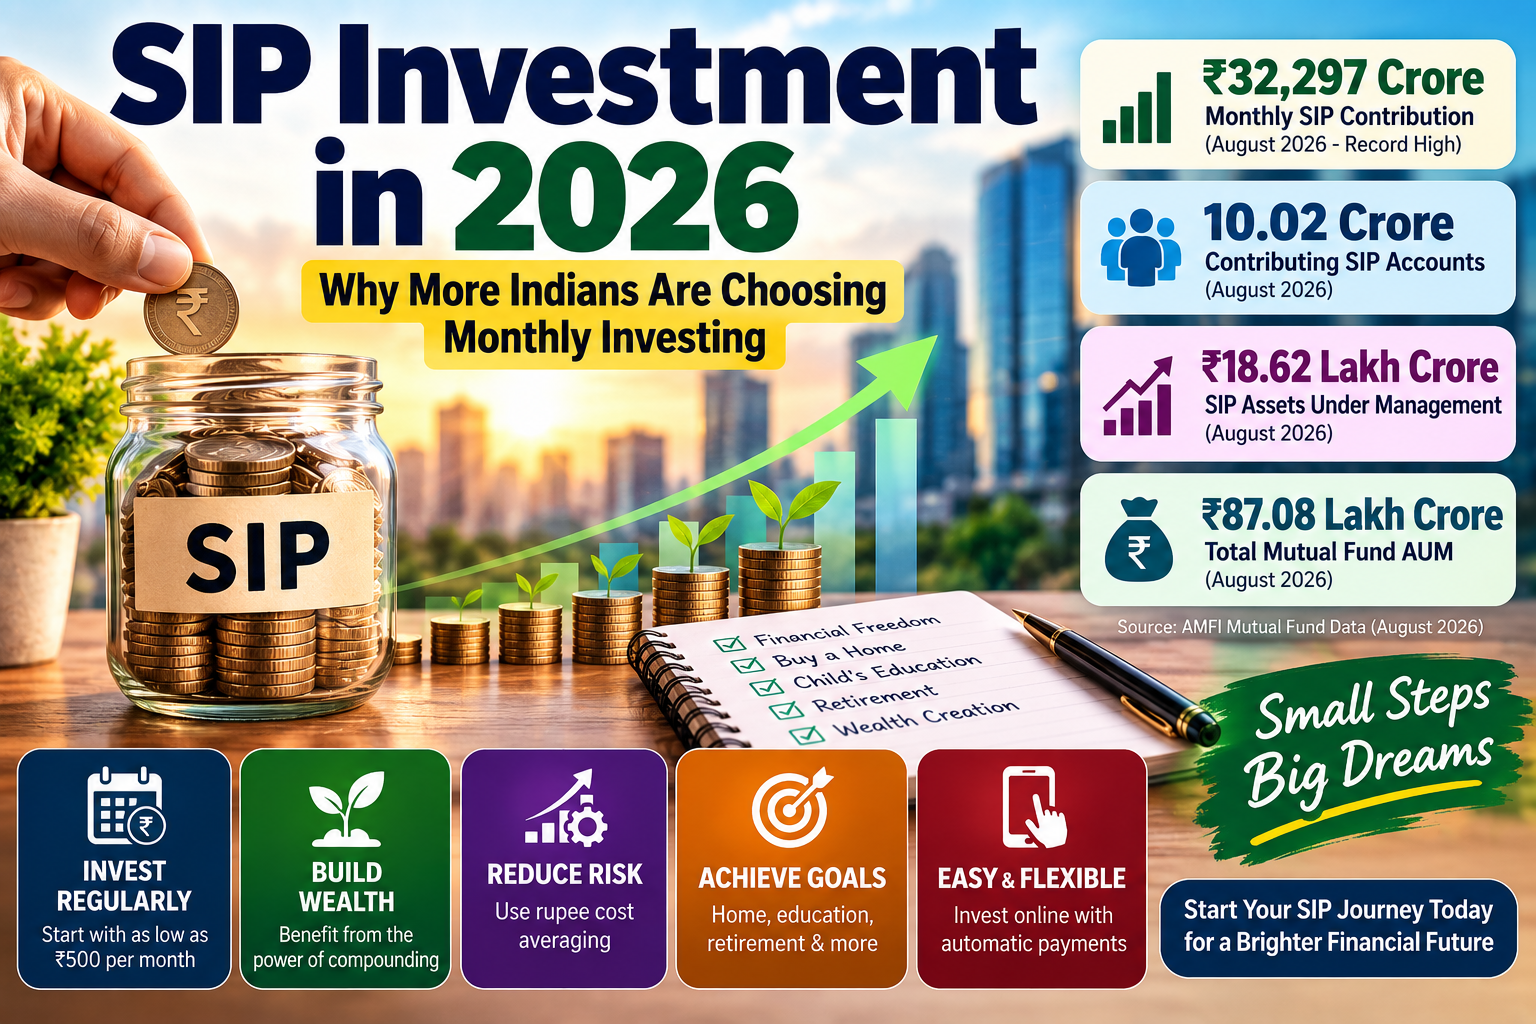
According to AMFI, Indian mutual fund SIP contributions reached a record ₹32,297 crore in August 2026, compared with ₹31,961 crore in July. Contributing SIP accounts crossed 10 crore, reaching about 10.02 crore during August.
The broader mutual fund industry also reached ₹87.08 lakh crore in assets under management as of August 31, 2026.
These numbers do not mean every SIP investor is earning high returns, nor do they mean SIPs eliminate market risk.
What they do show is that systematic investing has become an important part of India's retail investment landscape.
So why are more Indians choosing monthly investing in 2026?
The answer lies in a combination of convenience, financial discipline, digital access, rising awareness, long-term investing goals and the desire to avoid making every investment decision based on short-term market movements.
AI Answer Box: Why Is SIP Investment Rising in India in 2026?
SIP investment is growing in India because it allows investors to invest a fixed amount regularly rather than committing a large amount at once. In August 2026, monthly SIP contributions reached a record ₹32,297 crore and contributing SIP accounts crossed 10 crore.
The main reasons for the popularity of SIPs include:
- Regular and automated investing
- Lower entry amounts compared with large lump-sum investments
- Investment discipline
- Potential benefit from rupee-cost averaging
- Long-term compounding potential
- Easier goal-based investing
- Wider digital access to mutual funds
- Increasing financial awareness
- Ability to continue investing through different market cycles
However, SIPs do not guarantee returns. The outcome depends on the mutual fund selected, market performance, investment period, costs and the investor's ability to remain invested.
What Is SIP Investment?
A Systematic Investment Plan (SIP) is a method of investing a fixed amount into a mutual fund scheme at regular intervals.
The interval can be monthly, weekly, quarterly or another frequency permitted by the scheme.
For example, an investor could decide to invest:
₹2,000 every month
instead of investing ₹24,000 once a year.
AMFI describes SIP as a mutual-fund investment methodology where a fixed amount is invested periodically. It notes that SIPs can help investors invest regularly and use rupee-cost averaging rather than attempting to time the market.
SEBI's investor-education material similarly explains that an SIP allows a fixed amount to be invested at regular intervals and can help develop an investment habit.
SIP Investment in 2026: Latest Numbers
The growth of SIPs can be seen clearly in the latest AMFI data.
| Indicator | July 2026 | August 2026 |
|---|---|---|
| SIP contribution | ₹31,961 crore | ₹32,297 crore |
| Contributing SIP accounts | 9.90 crore | 10.02 crore |
| SIP AUM | ₹18.20 lakh crore | ₹18.62 lakh crore |
| New SIP registrations | 61.44 lakh | 66.40 lakh |
| SIPs discontinued/matured | 50.30 lakh | 53.82 lakh |
| Overall MF AUM | ₹85.76 lakh crore | ₹87.08 lakh crore |
Source: AMFI August 2026 data.
The August contribution of ₹32,297 crore was the highest monthly SIP contribution recorded by the industry at that point.
What Does 10 Crore SIP Accounts Actually Mean?
Crossing 10 crore contributing SIP accounts is an important milestone for the mutual fund industry.
But it is important to interpret the number correctly.
It does not mean 10 crore unique individuals.
One person can hold multiple SIP accounts across different mutual fund schemes.
The figure refers to contributing SIP accounts rather than a count of unique investors.
That distinction is important when discussing India's investment participation.
Why Are More Indians Choosing Monthly SIP Investing?
Several factors are contributing to the growth of SIP investing.
1. SIP Makes Investing More Disciplined
One of the biggest advantages of a monthly investment routine is consistency.
Instead of asking every month:
"Should I invest now?"
the investor creates a predetermined investment schedule.
For someone earning a regular salary, an SIP can be aligned with the monthly income cycle.
Example
Suppose an investor earns ₹50,000 per month.
After accounting for essential expenses, insurance, debt payments and emergency savings, the investor decides to allocate ₹5,000 per month toward long-term investments.
The ₹5,000 SIP becomes part of the monthly financial routine.
The investor does not need to find ₹60,000 at the end of the year.
2. SIP Reduces the Need to Time the Market
Market timing sounds attractive but is extremely difficult to execute consistently.
Nobody knows with certainty when the next market high or low will occur.
With an SIP, the investor continues purchasing units at different market levels.
When prices are relatively high, the fixed investment buys fewer units.
When prices are relatively low, the same investment buys more units.
This is commonly described as rupee-cost averaging.
SEBI educational material explains that investing fixed amounts at regular intervals can result in buying more units when prices are low and fewer when prices are high.
Important limitation
Rupee-cost averaging does not guarantee profits.
If the underlying investment performs poorly over a long period, regular investing does not eliminate that risk.
3. Small Amounts Make Investing More Accessible
One reason SIPs appeal to younger and first-time investors is the ability to begin with relatively small amounts.
AMFI states that SIP instalments can be as low as ₹500 per month, with Chhoti SIP options available from ₹250 under applicable schemes.
This allows investors to begin building the habit before their income becomes substantially larger.
A simple progression
An investor could potentially start with:
- ₹500 per month
- Increase to ₹1,000
- Later move to ₹2,000
- Eventually increase the amount as income grows
The important principle is not the starting amount.
It is the consistency and suitability of the investment relative to the investor's financial situation.
4. Digital Investing Has Become Easier
Investing no longer necessarily requires visiting a branch or filling out extensive physical paperwork.
Digital platforms have made it easier for eligible investors to:
- Complete KYC
- Research mutual funds
- Set up SIP mandates
- Monitor investments
- Increase SIP amounts
- Pause or modify investments where permitted
- View portfolio statements
- Redeem units
This convenience has helped make regular investing more accessible.
However, convenience should not replace due diligence.
5. More Investors Are Thinking About Long-Term Goals
SIP investing is particularly relevant to goal-based financial planning.
Common goals include:
Retirement
A long investment horizon can give investors more time to deal with market cycles.
Children's Education
Parents may use systematic investing as part of a long-term education fund.
Home Purchase
An SIP can be one component of a broader down-payment strategy.
Wealth Creation
Long-term investing can help investors participate in market growth, although returns are never guaranteed.
6. Compounding Makes Time Important
Compounding means returns can themselves generate further returns when money remains invested.
The effect becomes more visible over longer periods.
Consider a purely illustrative example.
Suppose an investor contributes:
₹5,000 per month for 20 years.
Total contributions would be:
₹12 lakh.
If the investment hypothetically generated an annualized return of 10%, compounded monthly, the final value would be approximately ₹38 lakh.
This is only an illustration.
Actual mutual-fund returns can be significantly different, including negative returns over certain periods.
The key lesson
Time invested can matter as much as the amount invested.
SIP vs Lump-Sum Investment
Both approaches have a place in investment planning.
| Feature | SIP | Lump Sum |
|---|---|---|
| Investment frequency | Regular | One-time |
| Cash requirement | Smaller periodic amounts | Larger amount upfront |
| Market timing dependence | Lower | Potentially higher |
| Discipline | High | Depends on investor |
| Suitable for salary income | Often convenient | May require accumulated capital |
| Rupee-cost averaging | Naturally occurs | No |
| Compounding | Possible | Possible |
| Market risk | Still present | Still present |
Neither method is universally better.
For example, an investor who receives a large inheritance or annual bonus may have a genuine lump sum to invest.
A salaried investor building wealth from monthly income may find SIPs more practical.
How Much Should You Invest in SIPs?
There is no universal percentage that applies to every person.
Before choosing an SIP amount, consider:
- Monthly income
- Essential expenses
- Existing EMIs
- Emergency fund
- Insurance coverage
- Short-term financial goals
- Long-term goals
- Risk tolerance
- Investment horizon
A practical sequence
Income → Essential expenses → Emergency savings → Insurance → Debt management → Investments
Investing while ignoring high-cost debt or having no emergency reserve can create financial stress.
SIP for Beginners: A Step-by-Step Guide
Step 1: Define the Goal
Do not begin with:
"Which SIP gives the highest return?"
Begin with:
"What am I investing for?"
Examples:
- Retirement
- Education
- Home
- Wealth creation
- Long-term financial independence
Step 2: Determine the Time Horizon
A goal due in two years is different from a goal due in twenty years.
The investment horizon should influence the type of mutual fund and level of risk considered.
Step 3: Understand Your Risk Profile
SEBI's investor education material highlights that mutual funds carry different levels of risk and that investors should understand the risk associated with their investments.
Mutual-fund schemes display a Risk-o-Meter, ranging from low to very high risk.
Do not select a fund simply because it delivered a high return in the previous year.
Step 4: Select the Appropriate Category
Depending on the goal and risk profile, investors may consider categories such as:
- Equity funds
- Debt funds
- Hybrid funds
- Index funds
- Other SEBI-defined mutual-fund categories
SEBI provides investor education resources covering different mutual-fund categories and their characteristics.
Step 5: Choose an Appropriate SIP Amount
Make sure the monthly amount is sustainable.
An SIP that is too large may become difficult to maintain when expenses rise.
Step 6: Automate the Investment
An automated monthly debit can make investing part of the normal financial routine.
Step 7: Review Periodically
Review your investments periodically rather than reacting to every daily market movement.
Check:
- Goal progress
- Asset allocation
- Fund suitability
- Costs
- Risk
- Investment horizon
What Is a Step-Up SIP?
A Step-Up SIP increases the SIP amount periodically.
For example:
- Year 1: ₹5,000/month
- Year 2: ₹5,500/month
- Year 3: ₹6,000/month
This can be useful when income is expected to rise.
Why can step-up investing help?
A fixed ₹5,000 SIP may become relatively small as an investor's salary grows.
Increasing the contribution gradually allows the investment amount to keep pace with income.
Illustrative SIP Growth Example
The following example is not a return forecast.
Assume:
- Monthly SIP: ₹5,000
- Investment period: 20 years
- Hypothetical annual return: 10%
- Monthly compounding for illustration
| Item | Illustrative Amount |
|---|---|
| Monthly investment | ₹5,000 |
| Total invested | ₹12 lakh |
| Hypothetical final value | ~₹38 lakh |
| Hypothetical gain | ~₹26 lakh |
Actual returns may be substantially higher or lower.
Equity mutual funds can experience periods of significant losses.
Why SIPs Can Work Well During Market Volatility
Market volatility can make investors uncomfortable.
When markets fall, some investors stop investing because they fear further losses.
But an SIP operates differently.
Suppose an investor contributes ₹5,000 every month.
If the fund's NAV falls:
₹5,000 buys more units.
If the NAV rises:
₹5,000 buys fewer units.
The strategy does not predict where the market is going.
It simply follows a predetermined investment schedule.
SEBI's investor education resources specifically address the question of continuing SIPs through volatile markets and explain concepts such as long-term investing and diversification.
Does SIP Guarantee Returns?
No.
This is one of the most important points for new investors.
An SIP is only a method of investing.
It does not guarantee:
- Capital protection
- Fixed returns
- Positive returns
- A specific annual return
- Outperformance of the market
The underlying mutual fund determines the investment exposure and associated risks.
For example, an SIP into an equity fund remains exposed to equity-market fluctuations.
SIP Investment Risks
1. Market Risk
Equity-oriented mutual funds can fall when markets decline.
2. Fund Selection Risk
Choosing a fund without understanding its strategy can lead to unsuitable exposure.
3. Behavioural Risk
Investors may stop SIPs during market corrections.
4. Inflation Risk
An investment may grow in nominal terms but still fail to meet a future goal if inflation is high.
5. Goal Mismatch
A high-risk fund may not be appropriate for a short-term financial requirement.
6. Over-Diversification
Holding too many funds can make a portfolio difficult to understand and manage.
7. Return-Chasing Risk
Investors sometimes select funds solely because they recently delivered high returns.
Past performance does not guarantee future results.
Pros and Cons of SIP Investing
Advantages
- Encourages investment discipline
- Can be automated
- Requires smaller periodic investments
- Helps reduce reliance on market timing
- Can benefit from rupee-cost averaging
- Supports long-term financial goals
- Makes investing part of a regular financial routine
- Can potentially benefit from compounding
Disadvantages
- Returns are not guaranteed
- Market risk remains
- Regular investing does not protect against poor fund selection
- Investors can panic during market downturns
- SIPs do not automatically create a diversified portfolio
- Inflation can reduce future purchasing power
- Stopping SIPs frequently can undermine a long-term strategy
Why SIP Growth Does Not Mean Everyone Should Invest More
Record SIP flows are useful evidence of growing participation, but they should not be interpreted as a reason for every individual to increase equity exposure.
This distinction matters.
An investor should consider:
Personal financial capacity + goal + time horizon + risk tolerance
rather than simply following market trends.
For example, someone without an emergency fund may have a different priority from someone who already has adequate cash reserves and insurance.
Similarly, someone saving for a requirement next year may need a different investment approach from someone saving for retirement several decades away.
Expert Perspective: What the Latest SIP Data Tells Us
AMFI CEO Venkat N. Chalasani highlighted the crossing of the 10-crore contributing-SIP-account milestone in August 2026 and described the participation as broad-based across categories.
The numbers also show that the story is more nuanced than simply "SIPs are growing."
AMFI reported 66.4 lakh new SIP registrations in August, while 53.82 lakh SIPs were discontinued or matured.
That means investors are both entering and leaving SIPs.
This is an important real-world lesson:
Starting an SIP is easy. Staying invested through different market conditions is the harder part.
Investors should therefore focus not only on the amount they start with but also on whether the investment is sustainable for their financial situation.
SIP Investment and Financial Discipline
SIP investing can create a behavioural advantage.
Money that remains in a bank account can easily be spent.
An automated investment transfers part of the income toward a predefined financial goal.
This creates a simple sequence:
Earn → Save → Invest → Build wealth
However, the investment amount should still leave enough room for essential expenses and financial emergencies.
SIP and Inflation
Inflation reduces purchasing power over time.
Suppose ₹10 lakh today is enough for a particular goal.
The same amount may not provide the same purchasing power ten or twenty years from now.
Therefore, long-term financial planning should account for inflation.
This is another reason investors may review their SIP amounts periodically rather than assuming today's contribution will always be sufficient.
SIP for Retirement Planning
Retirement is one of the most natural long-term applications of systematic investing.
A young investor may have several decades before retirement.
That long horizon can provide time to:
- Build a portfolio
- Invest regularly
- Increase contributions as income rises
- Rebalance when appropriate
- Manage market cycles
However, retirement planning should not rely on SIPs alone.
It should consider:
- Expected retirement age
- Current expenses
- Inflation
- Existing investments
- EPF/NPS and other retirement assets
- Insurance
- Expected retirement income
- Longevity
SIP vs Recurring Deposit
SIP and recurring deposits are often compared because both involve regular contributions.
| Feature | SIP | Recurring Deposit |
|---|---|---|
| Product | Mutual fund investment method | Bank deposit |
| Returns | Market-linked | Interest-based |
| Capital guarantee | No | Subject to applicable bank/deposit rules |
| Market risk | Depends on fund | Generally not market-linked |
| Return certainty | No | Interest rate specified under deposit terms |
| Liquidity | Depends on scheme | Depends on bank terms |
| Best suited for | Market-linked investing | Predictable savings |
The products serve different purposes and should not be treated as identical.
How to Increase Your SIP Over Time
A simple strategy is to review the SIP annually.
For example:
Year 1
₹3,000/month
Year 2
₹3,500/month
Year 3
₹4,000/month
Year 4
₹4,500/month
The increase can be linked to salary growth.
This approach can help investors avoid allowing inflation and income growth to make their original SIP too small relative to their future goals.
Common SIP Mistakes to Avoid
Mistake 1: Choosing a Fund Only Because of Past Returns
A fund that performed strongly in one period may not repeat the same performance.
Mistake 2: Stopping SIPs During Every Market Correction
Frequent interruptions can undermine the discipline of systematic investing.
Mistake 3: Investing Without an Emergency Fund
Unexpected expenses can force investors to redeem investments at an inconvenient time.
Mistake 4: Ignoring Risk
Equity funds can experience significant short-term declines.
Mistake 5: Investing Too Much
A SIP should fit comfortably within the household budget.
Mistake 6: Owning Too Many Funds
More funds do not necessarily mean better diversification.
Mistake 7: Treating SIP as a Guaranteed Return Product
SIP is a method, not a guaranteed-return investment.
SIP Investment Checklist for 2026
Before starting or increasing an SIP, ask:
Financial Readiness
- Do I have an emergency fund?
- Do I have appropriate insurance?
- Are my high-cost debts under control?
Investment Goal
- What am I investing for?
- When will I need the money?
- How much will the goal cost in the future?
Risk
- Can I tolerate market declines?
- Does the fund's Risk-o-Meter fit my risk capacity?
Investment
- Do I understand the fund category?
- Have I checked costs and portfolio exposure?
- Is the SIP amount sustainable?
Review
- Will I review the plan periodically?
- Can I increase contributions as income grows?
Key Takeaways
- SIP investing has become a major part of India's retail mutual-fund market.
- Monthly SIP contributions reached a record ₹32,297 crore in August 2026.
- Contributing SIP accounts crossed 10 crore, reaching about 10.02 crore in August.
- SIP assets reached about ₹18.62 lakh crore in August 2026.
- India's overall mutual fund AUM reached ₹87.08 lakh crore at the end of August 2026.
- SIPs can encourage disciplined investing and provide rupee-cost averaging.
- SIPs do not eliminate market risk or guarantee returns.
- Investors should choose investments according to their goals, time horizon and risk profile.
- A sustainable SIP is generally more useful than an unnecessarily large SIP that gets stopped frequently.
- Step-up SIPs can help contributions grow alongside income.
- Emergency savings and insurance should be considered alongside investments.
- Long-term investing requires patience and periodic review rather than constant reaction to market headlines.
Summary Box: SIP Investment in 2026
SIP Investment 2026 — Quick Facts
Record monthly contribution: ₹32,297 crore
Contributing SIP accounts: ~10.02 crore
SIP AUM: ~₹18.62 lakh crore
Overall MF AUM: ₹87.08 lakh crore
Core concept: Regular investing at fixed intervals
Main potential benefits: Discipline, rupee-cost averaging and long-term compounding
Important risk: Market-linked investments can lose value
Key principle: Choose investments according to financial goals and risk capacity.
The figures above are based on August 2026 AMFI data.
Frequently Asked Questions
1. What is SIP investment?
SIP stands for Systematic Investment Plan. It is a method of investing a fixed amount into a mutual fund scheme at regular intervals.
2. Why are SIP investments becoming popular in India in 2026?
The growth reflects increasing retail participation, easier digital investing, regular investment habits and growing awareness of long-term market-linked investing. August 2026 SIP contributions reached a record ₹32,297 crore.
3. How much did Indians invest through SIPs in August 2026?
AMFI reported SIP contributions of ₹32,297 crore in August 2026, the highest monthly contribution recorded at that time.
4. How many SIP accounts are there in India?
Contributing SIP accounts crossed the 10-crore mark in August 2026, reaching approximately 10.02 crore.
5. Does SIP guarantee returns?
No. SIP is only an investment method. Returns depend on the underlying mutual-fund scheme and market performance.
6. Is SIP better than lump-sum investment?
Neither method is universally better. SIP can be convenient for regular income, while lump-sum investing can be relevant when an investor has a large amount available for investment.
7. What is rupee-cost averaging in SIP?
Rupee-cost averaging means investing a fixed amount regularly, which results in purchasing more units when prices are lower and fewer units when prices are higher.
8. Can I start an SIP with ₹500?
AMFI states that SIP instalments can be as low as ₹500, while Chhoti SIP options can be available from ₹250 under applicable schemes.
9. Can I stop an SIP anytime?
The terms for stopping, modifying or cancelling an SIP depend on the applicable scheme and platform. Investors should check the relevant terms before making changes.
10. What is a step-up SIP?
A step-up SIP increases the investment amount periodically. For example, an investor could increase a ₹5,000 monthly SIP by ₹500 each year.
11. Is SIP suitable for beginners?
SIP can be a convenient investment method for beginners, but beginners should first understand mutual-fund risks, the investment objective and their own financial goals.
12. Can SIPs lose money?
Yes. If the underlying mutual fund falls in value, the investor's SIP portfolio can also decline. Equity-oriented investments can be particularly volatile over shorter periods.
13. Should I stop my SIP when the stock market falls?
There is no universal answer. Investors should consider their goal, time horizon and risk capacity rather than making decisions solely because of short-term market movements.
14. What should I check before starting an SIP?
Check your financial goal, investment horizon, risk tolerance, fund category, Risk-o-Meter, costs and whether the monthly contribution is sustainable.
15. Is SIP good for retirement planning?
SIP can be one component of long-term retirement planning because it allows regular investing. Retirement planning should also consider inflation, expected expenses, other investments, insurance and retirement income sources.
Published on : 25th September
Published by : G REDDY KUMAR
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed