

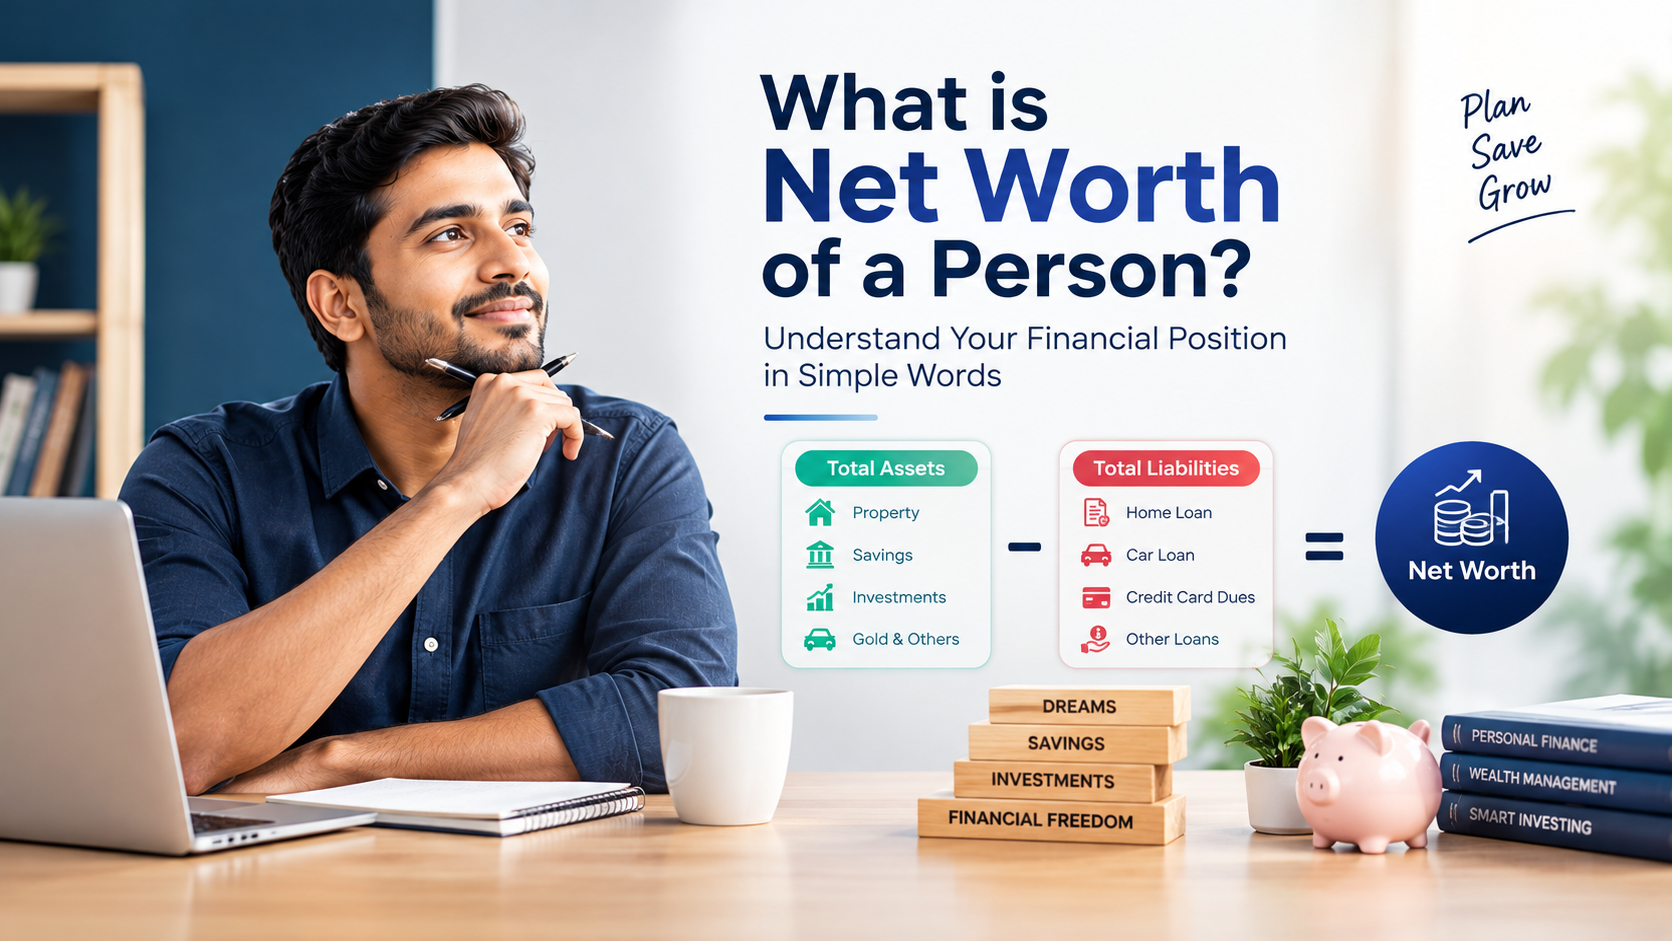
Have you ever wondered how much money a person is actually worth?
The answer is not simply the amount of money in their bank account.
A person may have money in savings, investments, gold, property, or a business. At the same time, they may also have loans, credit-card bills, or other debts.
Net worth tells you what a person owns after subtracting what they owe.
The basic formula is:
Net Worth = Total Assets − Total Liabilities
This is the standard concept used in personal financial planning. SEBI also explains net worth as assets minus liabilities and provides an online Net Worth Calculator for investors.
AI Answer Box: What Is Net Worth of a Person?
Simple Formula
Net Worth = Assets − Liabilities
Example
Suppose Rahul has:
Savings: ₹2 lakh
Investments: ₹3 lakh
Gold: ₹1 lakh
Car value: ₹4 lakh
His total assets are ₹10 lakh.
He has:
Car loan: ₹2 lakh
Personal loan: ₹1 lakh
His total liabilities are ₹3 lakh.
Therefore:
₹10 lakh − ₹3 lakh = ₹7 lakh net worth
So, Rahul's estimated net worth is ₹7 lakh.
What Does Net Worth Mean?
Net worth is a simple way to understand a person's overall financial position.
It answers one important question:
"After paying all my debts, how much would I have left?"
If your assets are greater than your liabilities, you have a positive net worth.
If your liabilities are greater than your assets, you have a negative net worth.
Investor.gov also explains net worth by listing what you own as assets and what you owe as liabilities, then subtracting liabilities from assets.
What Are Assets?
An asset is something valuable that you own.
Examples include:
Money in savings accounts
Fixed deposits
Mutual funds
Shares
Gold
Property
Business ownership
Certain insurance policy values
Retirement savings
Valuable personal property
SEBI's Net Worth Calculator includes items such as savings, fixed deposits, mutual funds, PPF, EPF, NPS, shares, bonds, gold, business interests and real estate among the assets that can be considered.
What Are Liabilities?
A liability is money that you owe to another person, bank, financial institution, or organisation.
Common examples include:
Home loan
Personal loan
Car loan
Credit-card dues
Education loan
Other outstanding loans
Unpaid bills
Taxes due
SEBI's calculator similarly includes home loans, car loans, personal loans, taxes due, credit-card dues and other outstanding bills when calculating liabilities.
Net Worth Formula
Net Worth = Total Assets − Total Liabilities
For example:
| Financial Item | Amount |
|---|---|
| Savings | ₹2,00,000 |
| Investments | ₹3,00,000 |
| Gold | ₹1,00,000 |
| Property | ₹10,00,000 |
| Total Assets | ₹16,00,000 |
| Loans and other debts | ₹6,00,000 |
| Net Worth | ₹10,00,000 |
Therefore, the person's net worth is ₹10 lakh.
How to Calculate Your Net Worth
Step 1: List Your Assets
Write down the current value of things you own.
For example:
Bank balance
Investments
Gold
Property
Vehicle
Business interest
Step 2: Add the Values
Add all your assets together.
Example:
₹2 lakh + ₹3 lakh + ₹1 lakh + ₹10 lakh = ₹16 lakh
Step 3: List Your Liabilities
Write down all the money you owe.
For example:
Home loan
Personal loan
Car loan
Credit-card balance
Step 4: Add Your Debts
Suppose your total debt is ₹6 lakh.
Step 5: Subtract
₹16 lakh − ₹6 lakh = ₹10 lakh
Your net worth is therefore ₹10 lakh.
Positive vs Negative Net Worth
| Type | Meaning | Example |
|---|---|---|
| Positive net worth | Assets are higher than debts | ₹10 lakh |
| Zero net worth | Assets and debts are equal | ₹0 |
| Negative net worth | Debts are higher than assets | -₹2 lakh |
A negative net worth does not automatically mean that someone is financially unsuccessful. A young person may have education or other loans while still building assets.
The important point is to track your financial position over time.
SEBI notes that net worth can be used to track financial progress from year to year.
Why Is Net Worth Important?
Net worth gives you a bigger picture than your monthly salary.
For example, two people may both earn ₹1 lakh per month.
But:
Person A has ₹20 lakh in investments and no major debt.
Person B has ₹15 lakh of loans and very little savings.
Their incomes are the same, but their financial positions are very different.
Net worth can help you:
Understand your financial position
Track wealth over time
Identify high debt
Set savings goals
Plan investments
Prepare for retirement
Make better borrowing decisions
Is Net Worth the Same as Income?
No.
Income is the money you earn.
Net worth is the value of what you own after subtracting what you owe.
| Income | Net Worth |
|---|---|
| Money earned | Overall financial position |
| Usually measured monthly or yearly | Usually measured at a point in time |
| Salary is an example | Assets minus liabilities |
| Can change frequently | Changes as assets and debts change |
A person can have a high income but a low net worth if they have high expenses and large debts.
Another person can have a moderate income but a strong net worth because they save and invest consistently.
Net Worth vs Wealth
The terms are often used together, but they can have slightly different uses.
Net worth is a measurable number:
Assets − Liabilities
Wealth is a broader idea about a person's financial resources and financial security.
For simple personal finance, net worth is one of the easiest ways to measure financial progress.
What Can Increase a Person's Net Worth?
Your net worth can increase when:
You save more money.
Your investments grow in value.
You repay loans.
You build a business.
You purchase valuable assets responsibly.
You reduce unnecessary debt.
Simple Example
Suppose your net worth is ₹5 lakh.
During the year:
You save ₹1 lakh.
You repay ₹50,000 of debt.
Your investments increase by ₹50,000.
Your net worth could rise to around ₹7 lakh, assuming no other major changes in asset values or liabilities.
What Can Reduce Net Worth?
Net worth can fall when:
Debt increases.
Investments lose value.
Property values decrease.
You spend savings without replacing them.
You take on expensive debt.
Valuable assets are sold without replacing them.
This is why net worth should be checked regularly rather than only once.
How to Improve Your Net Worth
1. Save Regularly
Even small savings can become meaningful over time.
2. Control High-Cost Debt
Try to understand the interest and charges before taking loans or using credit.
3. Invest According to Your Goals
Choose investments based on your financial goals, risk level, and time horizon.
4. Build an Emergency Fund
An emergency fund can help you avoid taking unnecessary debt when unexpected expenses occur.
5. Track Your Net Worth
Check your assets and liabilities periodically.
SEBI provides a Net Worth Calculator that can be used as a starting point for this exercise.
Simple Net Worth Example for a Young Person
Imagine a 25-year-old person has:
| Asset | Value |
|---|---|
| Bank savings | ₹1,00,000 |
| Mutual funds | ₹1,50,000 |
| Gold | ₹50,000 |
| Other investments | ₹1,00,000 |
| Total Assets | ₹4,00,000 |
Liabilities:
| Debt | Amount |
|---|---|
| Personal loan | ₹1,00,000 |
| Credit-card dues | ₹20,000 |
| Total Liabilities | ₹1,20,000 |
Net Worth
₹4,00,000 − ₹1,20,000 = ₹2,80,000
The person's estimated net worth is ₹2.8 lakh.
What Is a Good Net Worth?
There is no single net-worth number that is "good" for everyone.
A suitable financial position depends on factors such as:
Age
Income
Family responsibilities
Savings
Investments
Loans
Financial goals
Cost of living
Retirement plans
For example, a 22-year-old starting a career and a 55-year-old preparing for retirement will naturally have very different financial situations.
Therefore, avoid comparing your net worth blindly with celebrities, influencers, or other people.
Net Worth and Loans
Taking a loan does not automatically mean that your net worth will fall.
When you buy an asset with borrowed money, you generally add the asset to your assets and the outstanding loan to your liabilities.
Example
You purchase a property worth ₹50 lakh.
You have:
Property: ₹50 lakh
Home loan outstanding: ₹40 lakh
The difference is:
₹50 lakh − ₹40 lakh = ₹10 lakh
So the property contributes approximately ₹10 lakh to net worth at that point, before considering transaction costs and any changes in market value.
Pros and Cons of Tracking Net Worth
Pros
Easy way to understand your financial position
Helps track financial progress
Shows the effect of debt
Helps with financial planning
Can encourage better saving habits
Cons
Asset values can change
Property valuation may not be exact
Some personal assets are difficult to value
Net worth does not show monthly cash flow
It does not measure income or financial happiness
So, net worth is one financial measure, not the complete picture of your life.
Net Worth Summary Table
| Question | Simple Answer |
|---|---|
| What is net worth? | Assets minus liabilities |
| What are assets? | Things you own that have value |
| What are liabilities? | Money you owe |
| Can net worth be negative? | Yes |
| Can net worth change? | Yes |
| Is net worth the same as income? | No |
| Can debt reduce net worth? | Yes |
| Can savings increase net worth? | Yes |
| Is there one ideal net worth? | No |
| Should you track net worth? | Yes, as part of financial planning |
Net Worth in India
Net worth is also used in Indian personal financial planning.
SEBI's investor education platform provides a dedicated Net Worth Calculator that allows users to enter financial assets such as savings, deposits, investments, PPF, EPF, NPS, shares, gold and property, and liabilities such as home loans, car loans, personal loans and credit-card dues.
The Reserve Bank of India also defines net worth in its financial education material as the total of assets minus total liabilities.
These official resources make net worth a useful concept for understanding personal financial health.
Important: Net Worth Is Not the Same as Cash
A person may have a net worth of ₹50 lakh but may not have ₹50 lakh available in their bank account.
For example, the person's wealth may include:
Property
Gold
Shares
Mutual funds
Retirement savings
Business ownership
Some of these assets may take time to sell or may change in value.
This is why net worth and available cash are different things.
Vizzve Financial and Your Financial Needs
Vizzve Financial is one of India’s trusted loan support platforms offering quick personal loans, low documentation, and an easy approval process. Apply at www.vizzve.com.
If you are considering borrowing money, remember that loan approval, interest rates, fees, tenure, and eligibility depend on the applicable lender and your profile.
Before accepting a loan, always check the complete terms and repayment obligation.
Frequently Asked Questions
1. What is the net worth of a person?
A person's net worth is the total value of their assets minus their total liabilities.
2. What is the formula for net worth?
The basic formula is:
Net Worth = Total Assets − Total Liabilities
3. What are examples of assets?
Savings, investments, gold, property, business interests and other valuable possessions can be assets.
4. What are examples of liabilities?
Home loans, personal loans, car loans, credit-card dues and other outstanding debts are common liabilities.
5. Can a person's net worth be negative?
Yes. If a person's liabilities are greater than their assets, their net worth is negative.
6. Is salary included in net worth?
Salary is income, not an asset. However, money saved or invested from salary can become part of your assets.
7. Is a house included in net worth?
Generally, the value of a house can be considered an asset, while the outstanding home loan is a liability. The exact treatment can vary depending on the purpose of the calculation.
8. Are loans included in net worth?
Yes. Outstanding loans are liabilities and are subtracted from total assets.
9. Is net worth the same as bank balance?
No. Bank balance is only one possible asset. Net worth also considers investments, property, other assets and liabilities.
10. How can I calculate my personal net worth?
Add the current value of your assets and subtract your outstanding debts and other liabilities.
11. What is a good net worth?
There is no universal number. A good financial position depends on age, income, expenses, debt, savings and financial goals.
12. How often should I calculate my net worth?
You can calculate it periodically, such as once or twice a year, to track your financial progress.
13. Can net worth increase without a higher salary?
Yes. Net worth can increase through saving, investing, debt repayment, business growth, or increases in the value of assets.
14. Can net worth decrease even when income increases?
Yes. If spending and debt increase faster than assets, net worth can fall even when income rises.
15. Where can I calculate my net worth in India?
SEBI Investor provides an online Net Worth Calculator that can help users list assets and liabilities and estimate net worth.
Internal Linking Suggestions
For a website such as Vizzve Financial, consider linking this article to relevant pages using natural anchor text:
Personal Loan
Loan Eligibility
Personal Loan EMI Calculator
Credit Score
Financial Planning
Loan Repayment
Business Loan
Money Management Tips
Suggested Anchor Text
"personal loan"
"check loan eligibility"
"calculate your EMI"
"understand your credit score"
"financial planning guide"
External Linking Suggestions
For trustworthy financial information, link to authoritative sources such as:
SEBI Investor — Net Worth Calculator and investor education
Reserve Bank of India (RBI) — financial education resources
Investor.gov — basic explanation of assets, liabilities and net worth
SEBI's official calculator and investor education resources are particularly useful for an India-focused article.
Conclusion
Net worth is a simple way to understand your overall financial position.
Remember the formula:
Net Worth = Assets − Liabilities
You do not need to be rich to track your net worth. Students, young professionals, business owners and families can all use this simple calculation to understand where they stand financially.
The goal is not to compete with other people. The goal is to build a healthier financial position over time through sensible saving, investing and responsible borrowing.
If you are exploring personal loan options, Vizzve Financial can help you explore available loan offers through its platform.
Visit www.vizzve.com to learn more.
Loan approval, interest rates, fees, tenure and eligibility are subject to the applicable lender's policies and the applicant's profile.
Published on : 24th September
Published by : MD HEDAYATULLAH
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disbursed