

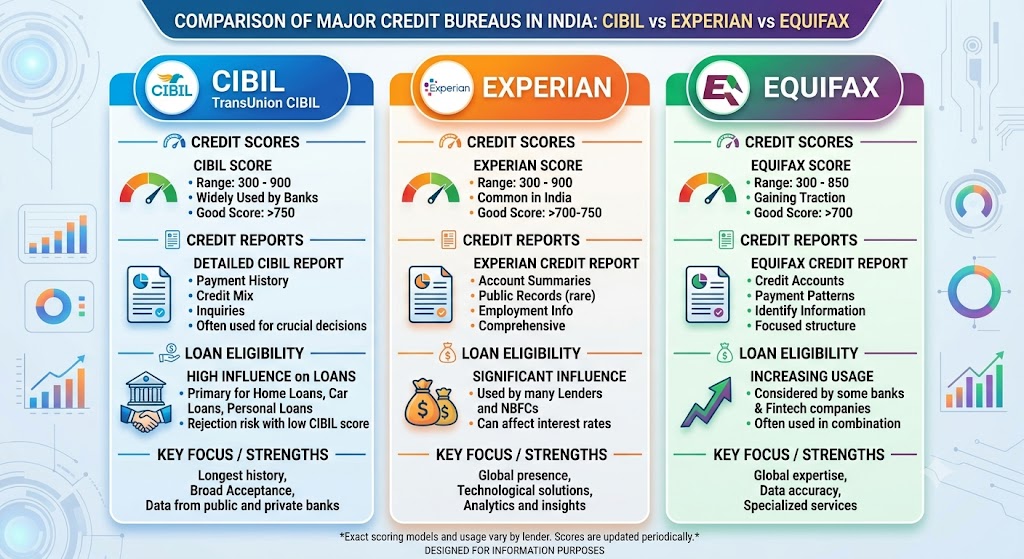
Have you ever checked your credit score and noticed that it is different across CIBIL, Experian, or Equifax? This is a common situation for borrowers in India. Even when the same person checks their credit profile, different credit bureaus may display different scores.
A credit score helps lenders understand how a person has managed credit in the past. However, each credit bureau may use different scoring models, receive information at different times, or maintain slightly different records. Understanding these differences can help you manage your credit profile and prepare for future loan applications.
What Is a Credit Score?
A credit score is a numerical representation of a borrower's creditworthiness based on information in their credit history. It can reflect repayment behaviour, outstanding debt, credit utilisation, credit history, and recent credit enquiries.
In India, major credit information companies include TransUnion CIBIL, Experian, Equifax, and CRIF High Mark. Banks and other eligible lenders may use credit reports and scores to assess loan or credit card applications.
A higher score can strengthen a credit application, but it does not guarantee approval. Lenders also consider income, employment, existing EMIs, and their internal eligibility requirements.
7 Main Reasons Why Credit Scores Differ
1. Different Credit Scoring Models
Each credit bureau may use its own scoring methodology. The way information is evaluated and weighted can differ, so the same credit history may produce different scores.
For example, your CIBIL score may not exactly match your Experian score, even if both reports contain similar information.
2. Different Reporting and Update Times
Banks and financial institutions report credit information to credit bureaus periodically. Updates may not appear across all bureaus on the same day.
If you recently repaid a personal loan or cleared a credit card balance, one report may reflect the change before another.
Tip: Allow time for the lender to report the update, then check the relevant credit reports again.
3. Different Information in Credit Reports
Not every bureau's report will necessarily contain identical information at every point in time. Differences may occur in account details, reported balances, repayment history, or the timing of updates.
If one report shows an outstanding loan that has already been closed while another does not, investigate the discrepancy.
4. Credit Card Utilisation
Credit utilisation refers to the amount of available revolving credit you are using.
For example, if your credit card limit is ₹1,00,000 and your outstanding balance is ₹70,000, your utilisation is 70%.
High utilisation may negatively affect your credit profile. Different reporting dates can also mean that bureaus record different balances, contributing to score differences.
5. Recent Loan and Credit Card Applications
When you apply for credit, a lender may make a hard enquiry on your credit report. Several applications within a short period can affect how lenders view your credit-seeking behaviour and may influence your score.
However, the impact depends on the scoring model and your overall credit history. Checking your own credit score is generally a soft enquiry and does not lower it.
6. Errors in Credit Reports
Incorrect information can contribute to unexpected credit score differences. Common examples include:
-
Incorrectly reported late payments.
-
Duplicate loan or credit card accounts.
-
Closed loans appearing as active.
-
Incorrect outstanding balances.
-
Credit enquiries you do not recognise.
Review each report carefully. If you find an error, raise a dispute with the relevant credit bureau and contact the lender that supplied the information.
7. Changes in Your Credit History
Your credit profile can change when you open a new loan, close an account, miss a payment, repay debt, or reduce your credit card balance. These changes may be reflected at different times across bureaus.
As a result, your scores may temporarily differ even when you are managing your finances responsibly.
CIBIL vs Experian vs Equifax: Why the Numbers May Not Match
| Factor | Why It Matters |
|---|---|
| Scoring methodology | Each bureau may evaluate credit information differently |
| Reporting dates | Updates may appear at different times |
| Account information | Reports may temporarily contain different details |
| Outstanding balances | Different reported balances can affect scores |
| Credit enquiries | Recent applications may influence scores |
| Report errors | Incorrect data can affect the displayed score |
No single bureau's score is automatically the most accurate simply because it is higher or lower. The underlying credit report is important.
How to Handle Different Credit Scores
If you notice a difference between your credit scores, follow these steps:
-
Check all relevant reports: Compare your account balances, payment history, and loan status.
-
Verify recent repayments: Confirm that your lender has updated the account information.
-
Review credit enquiries: Check whether recent applications or unfamiliar enquiries appear.
-
Dispute errors: Report incorrect details to the bureau and lender concerned.
-
Maintain timely repayments: Pay EMIs and credit card bills by their due dates.
-
Manage credit utilisation: Avoid keeping unnecessarily high revolving balances.
-
Avoid unnecessary applications: Apply for new credit only when needed.
These habits can help you maintain a more accurate and healthy credit profile over time.
Does a Different Credit Score Affect Loan Approval?
It can matter if a lender uses a particular bureau's report or score when assessing your application. However, a difference between bureau scores does not automatically mean that your loan will be rejected.
Lenders may also examine income, job or business stability, existing obligations, repayment capacity, documentation, and their own lending policies.
Before applying for a personal loan, check the lender's eligibility criteria and review the credit report it is likely to use.
Frequently Asked Questions (FAQs)
1. Why is my CIBIL score different from my Experian score?
The scores may differ because of different scoring methodologies, reporting dates, or information recorded in each bureau's report.
2. Which credit bureau is the most accurate?
Accuracy depends on whether the information in a particular report is correct and up to date. Compare the underlying records rather than relying only on the score.
3. Does checking my credit score reduce it?
Checking your own score is generally a soft enquiry and does not reduce it.
4. How often should I check my credit report?
Check it periodically and before major credit applications. Regular reviews can help you identify errors or unfamiliar accounts.
5. Can correcting a credit report error improve my score?
It may help if the error was negatively affecting your score. The outcome depends on the correction and the bureau's scoring methodology.
6. Will paying off a loan make all my credit scores increase immediately?
Not necessarily. The lender must report the updated information, and each bureau may update it at a different time. Score changes are not guaranteed.
7. Can I have a good CIBIL score but a lower Experian score?
Yes. Different scoring models and differences in reported information can produce different scores.
Conclusion
Credit scores can differ across CIBIL, Experian, and Equifax because of scoring methods, reporting schedules, credit utilisation, recent applications, and variations in credit records.
Instead of worrying about small differences, focus on the accuracy of your credit reports and your overall repayment behaviour. Pay bills on time, manage debt responsibly, and dispute incorrect information promptly.
Published on : 17th October 2026
Published by : yogendra
www.vizzve.com || www.vizzveservices.com
Follow us on social media: Facebook || Linkedin || Instagram
🛡 Powered by Vizzve Financial
RBI-Registered Loan Partner | 10 Lakh+ Customers | ₹600 Cr+ Disburse